By Enrico Crovini · 01 Nov 2024 · 8 MIN READ
Block Scholes x Bybit Crypto Derivatives October 30th
As the U.S. election approaches, short-tenor implied volatility has surged to multi-month highs, outperforming the far-end of the term structure and resulting in a significant inversion in the term structure. This indicates strong moves in positioning ahead of the election early next week, reminiscent of the same pattern observed prior to the ETF launch in January. ETH derivatives suggest that the second-largest cryptocurrency is likely to continue its long-standing trend of underperformance amid event risk, trailing BTC across all metrics and carrying a 10-point volatility premium over BTC.
Key Insights
Futures: The rise in futures open interest has accelerated, signaling strong demand for leveraged exposure and heightened trading activity ahead of the election. Positions in BTC are preferred over ETH.
Perpetuals: Open interest briefly dipped before sharply recovering, while funding rates remain stubbornly positive for most tokens, reflecting strong demand for leveraged long exposure.
Options: The kink in the term structure has developed into a strong inversion at the front end, reflecting increased demand for short-dated options ahead of the U.S. election.
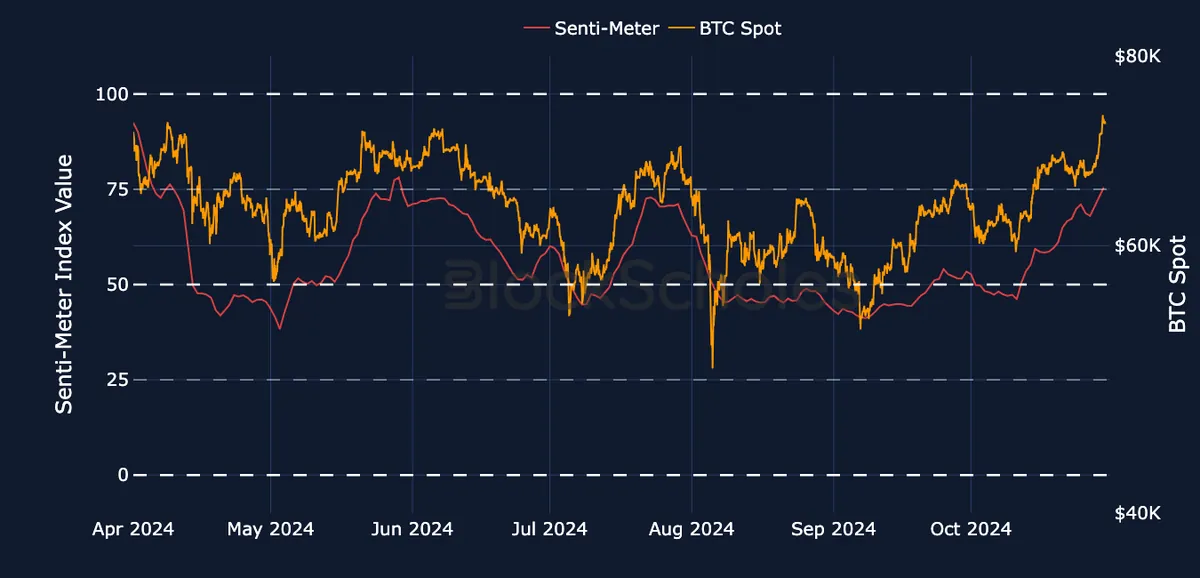
Block Scholes BTC Senti-Meter Index
Block Scholes ETH Senti-Meter Index
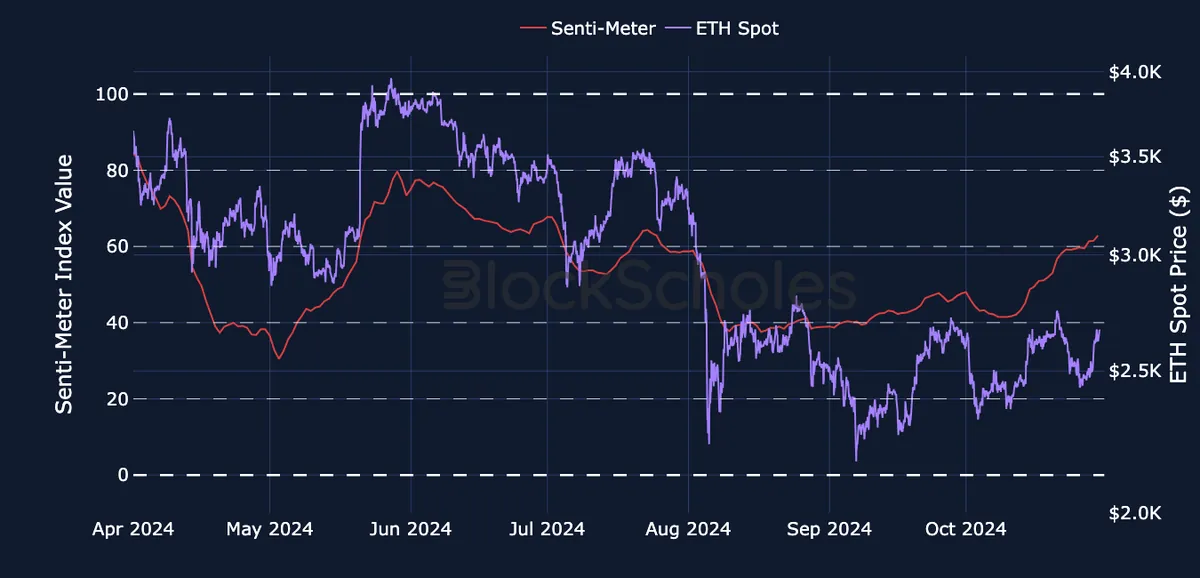
Block Scholes’ Senti-Meter index aggregates the funding rate, future-implied yield, and volatility smile skew into a single expression of sentiment in derivatives markets — see more in the methodology article here.
Macro, Tech & Regs
Macro Calendar & Recent Events
- U.S. Growth Domestic Product — Oct 30, 2024 — The U.S. economy grew at an annualized rate of 2.8% in Q3 2024. While this is a reasonable rate, it came in below expectations of 3.0%.
- China Fiscal Stimulus — Oct 30, 2024 — China’s top legislative body could approve a $1.4T fiscal stimulus package in a meeting held from Nov 4–8, 2024, in a much-anticipated wait for further stimulus in order to reach its 5% growth target.
- U.S. Personal Consumptions Expenditures (PCE) index — Oct 31, 2024 — The Fed’s preferred inflation gauge, PCE, is expected to show a 2.1% YoY and 0.2% MoM increase in prices. This should support a second rate cut by the Fed in its November meeting, to follow their 50 basis point cut in September.
- Bank of Japan (BoJ) Monetary Decision — Oct 31, 2024 — The Bank of Japan is expected to hold its interest rate steady at 0.25%, with potential hikes later in the year.
- U.S. Jobs Data — Nov 1, 2024 — The U.S. Employment Situation Summary is expected to show the U.S. economy added 110,000 jobs in October 2024, a reduction from the 254,000 added in September.
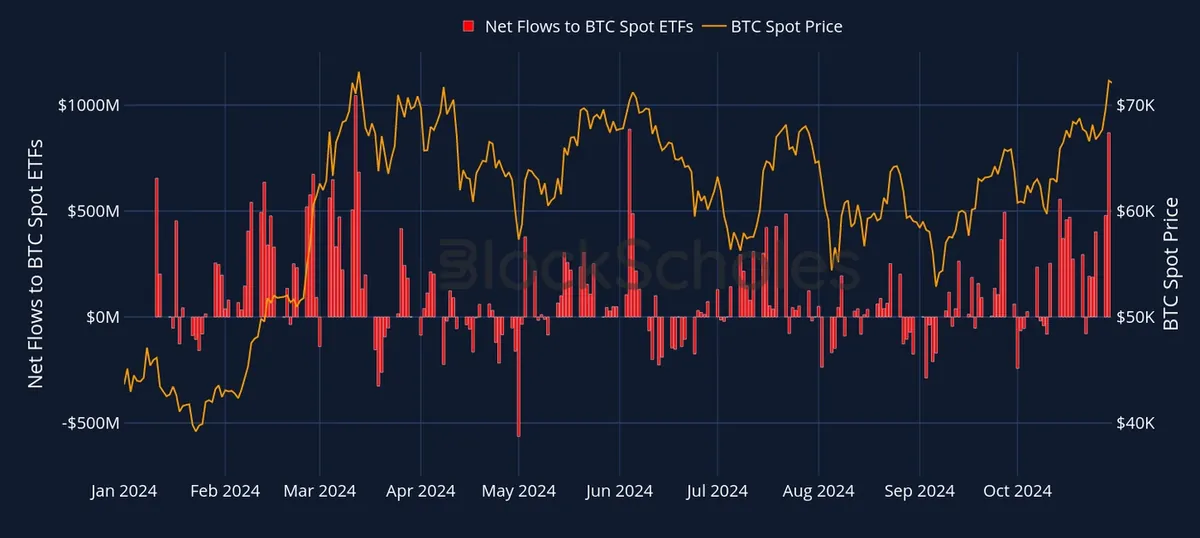
BTC Price Rally & Spot ETFs — BTC’s spot price rally fell just short of its all-time high of $73,700. This move was supported by U.S. Bitcoin Spot ETFs activity, which has continued a run that has seen more than $3B of net inflows over the past fortnight.
Trending News
- The Royal Government of Bhutan, which has been mining BTC since 2019, transferred $66M of the asset to exchanges in a potential move to sell some of its holdings. Its current total BTC holdings amount to approximately $886M.
- Alameda Research, the trading arm of bankrupt crypto exchange FTX, has initiated legal action to recover $50M in assets held in an exchange account belonging to Alameda.
Futures Open Interest Accelerates
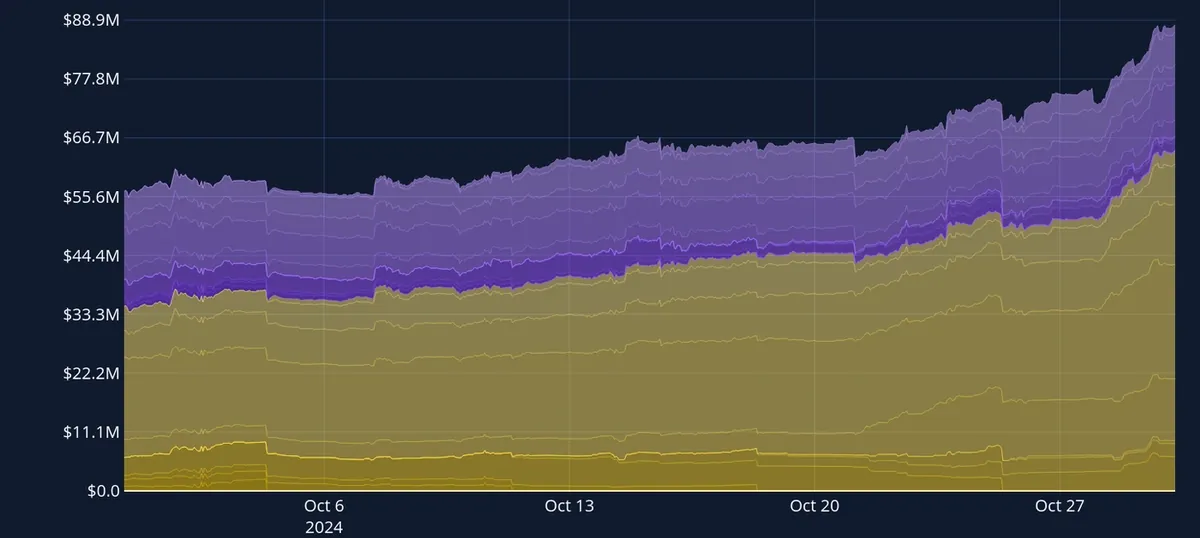
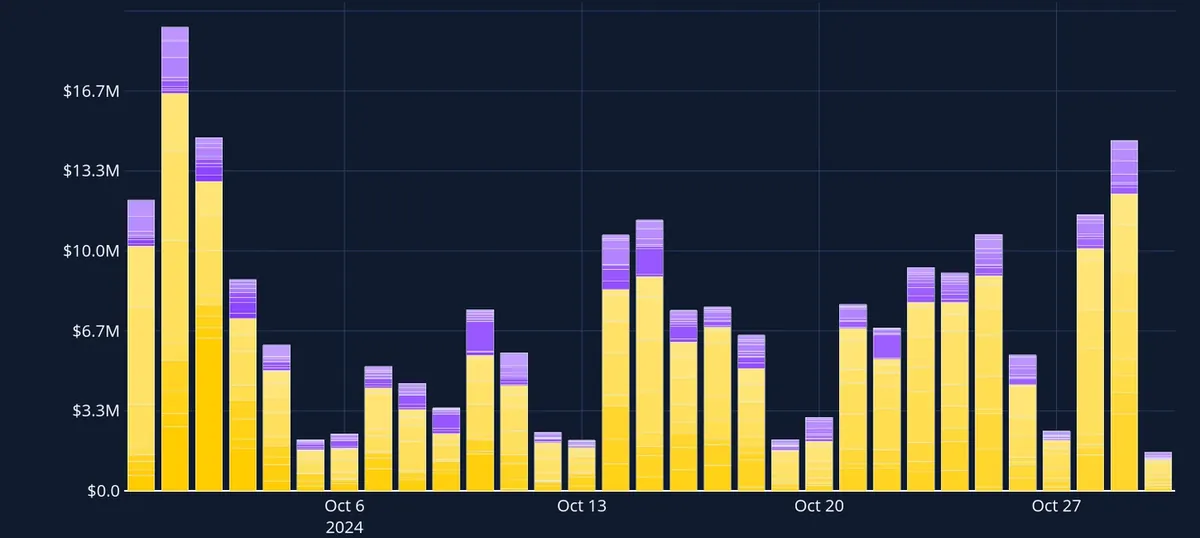
Futures open interest has seen a slight increase compared to last week. While showing general sideways movement, there has been a drop in open interest, specifically for longer tenors. Levels have quickly recovered and even surpassed previous values, caused by an increase in open interest for the November 29, 2024 expiration date for BTC futures. Trading volumes at the start of this week have been lower than last week’s, but remain above their lowest levels observed earlier in the month. This suggests a recovery in market activity despite some fluctuations in both open interest and trading volumes.
Bybit Futures Swap Open Interest
Bybit Futures Trading Volumes
Perp Open Interest Reaches Highs
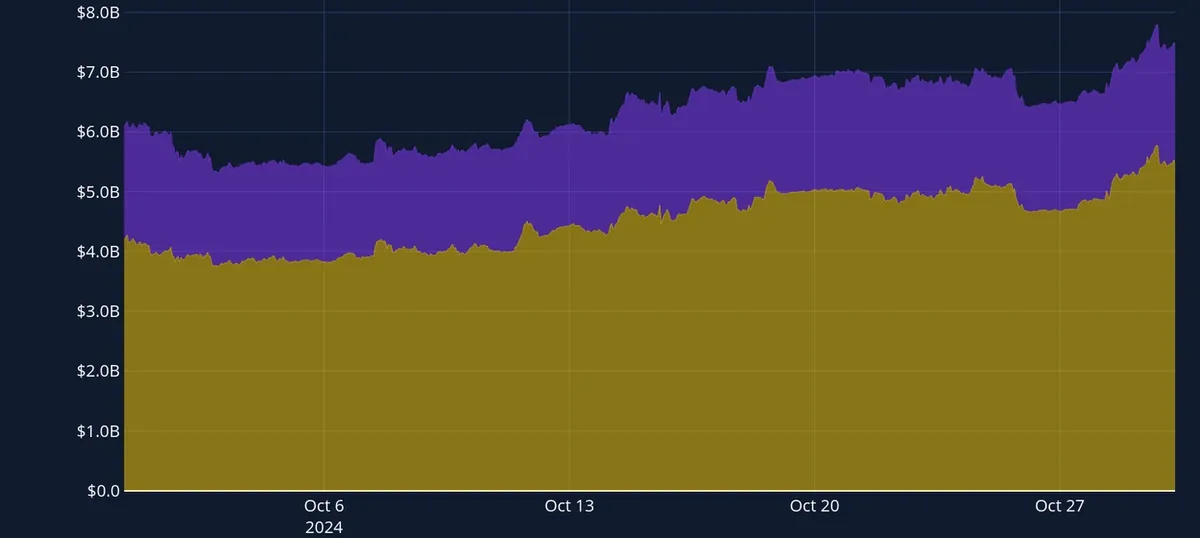
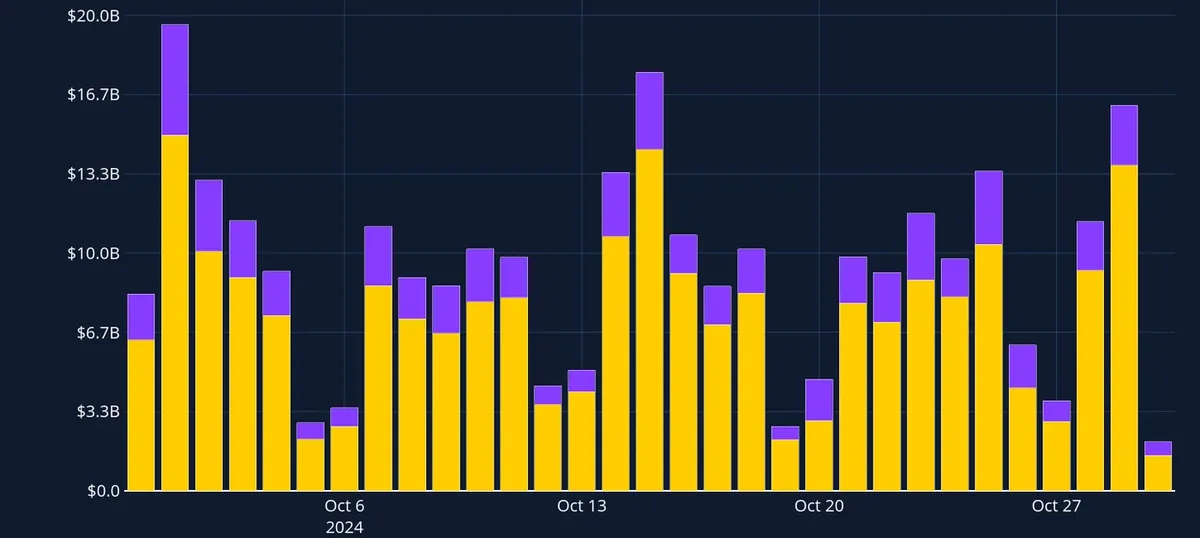
Open interest in perpetual swap markets experienced a brief decline before making a sharp recovery in tandem with spot price rallies, resulting in the highest level of open interest seen this month (October 2024). Taken alongside the positive funding rates that we’re seeing across markets, these sudden shifts indicate a robust bullish demand for leveraged long exposure, as traders actively position themselves ahead of the upcoming event risk. Additionally, while trading volumes continue to be high, they haven’t registered exceptional activity over the past week, suggesting steady engagement with perps without significant volatility.
Bybit Perp BTC & ETH Open Interest — Open interest registered quickly rising levels in the past few days, now moving sideways alongside spot price.
Bybit Perp Trading Volumes — Trade volumes are still high and levels are comparable to those seen in previous weeks, despite the increased positioning.
Funding Rates Remain Positive
Perpetual funding rates remained firmly positive, signaling that traders are still willing to pay for leveraged long exposure. For most tokens, funding has consistently been positive with minimal oscillations, reflecting stable demand. However, perpetual funding rates for SOL, TON, ADA and ATOM briefly turned negative before reverting to positive territory, indicating a momentary pullback in sentiment that quickly recovered. For example, SOL’s spot price registered negative price action around Oct 25–26, 2024 (that shows in the funding rate levels with a delay), but has since recovered.
BTC Options
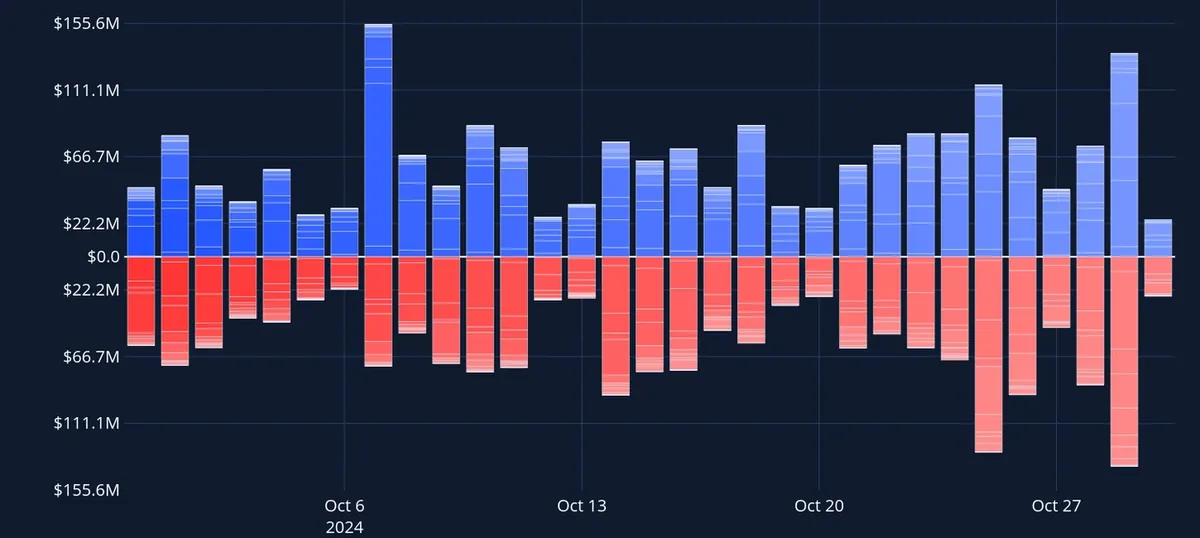
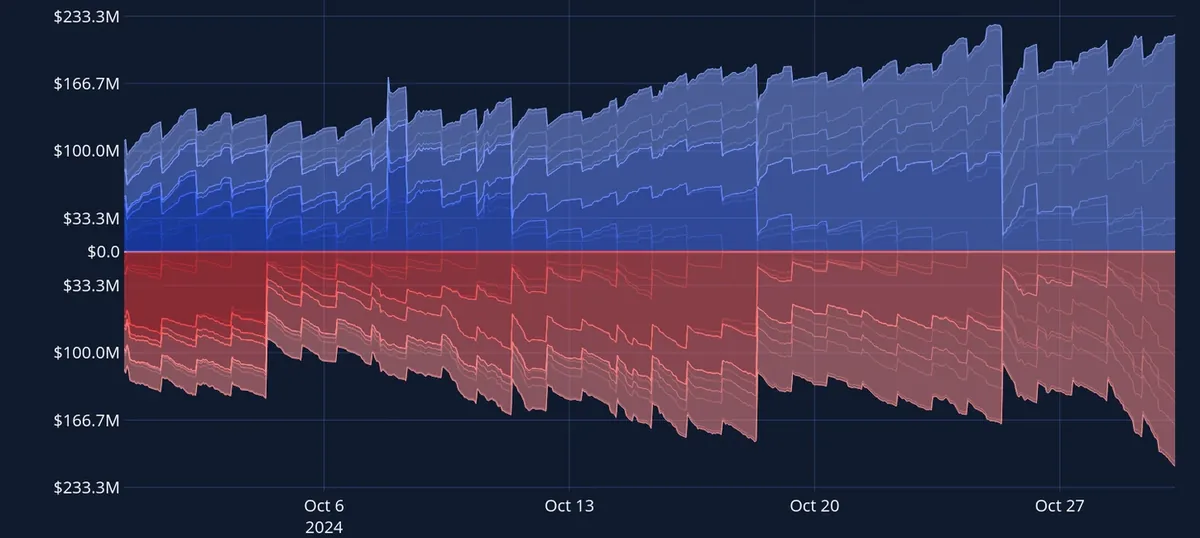
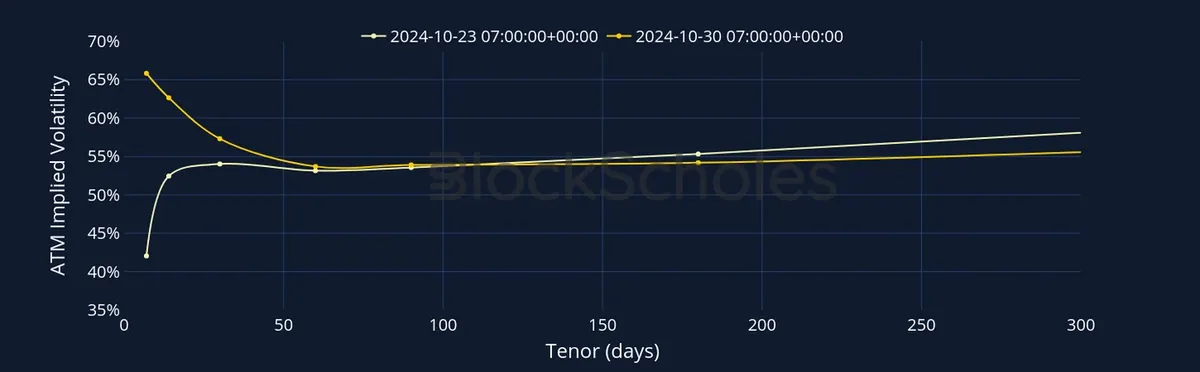
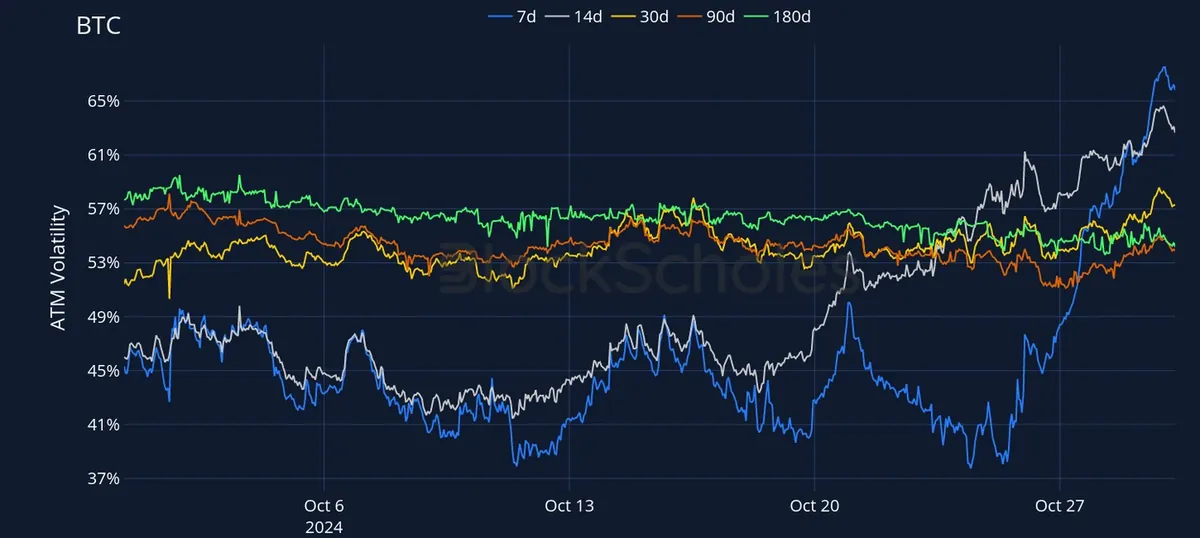
BTC’s implied volatility term structure has strongly inverted, as short-tenor implied volatility has risen sharply to trade at a 10-point premium over longer tenors. Market participants are therefore signaling enhanced expectations in options markets as the election approaches, echoing the activity that we’ve seen in futures and perpetuals. This rush to positioning mirrors the market behavior observed in January 2024 ahead of the Spot ETF releases, when demand surged for short-term exposure to volatile price action in anticipation of a known event risk. Most notably, despite bullish market indicators, open interest has registered fast rising interest for put options, which have grown to similar levels as call options.
BYBIT BTC OPTIONS VOLUMES
BYBIT BTC OPTIONS OPEN INTEREST
Volatility Term Structure Steepens
BYBIT BTC & ETH Volatility Term Structure — Volatility has increased sharply at the front end of the term structure, which is now strongly inverted.
BYBIT BTC SVI ATM IMPLIED VOLATILITY — The term structure has inverted ahead of the U.S. election event risk, similar to the positioning we saw ahead of the release of Bitcoin Spot ETFs in January 2024.
ETH Options
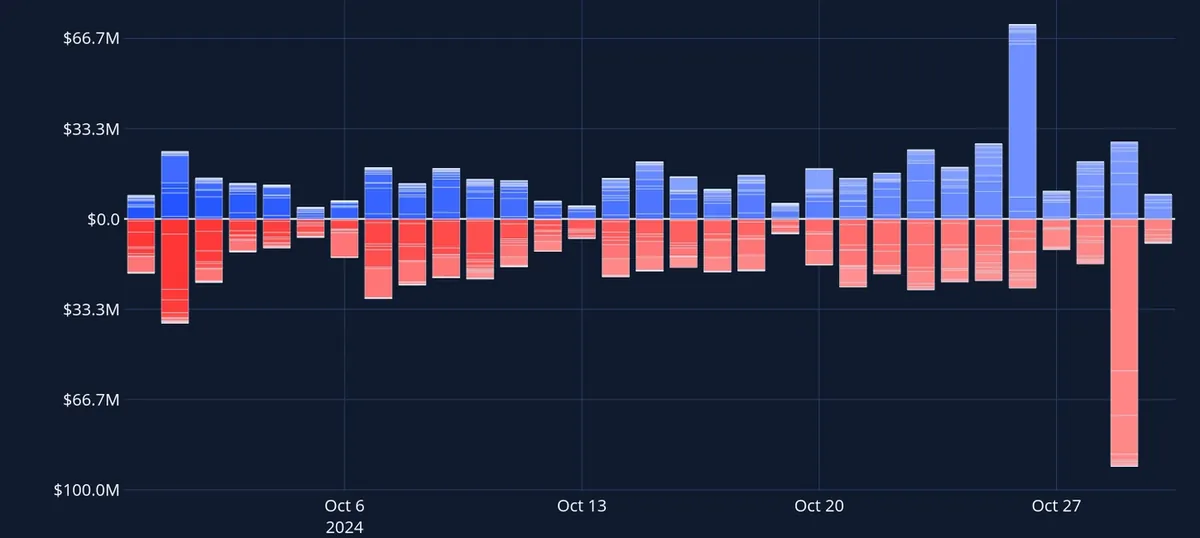
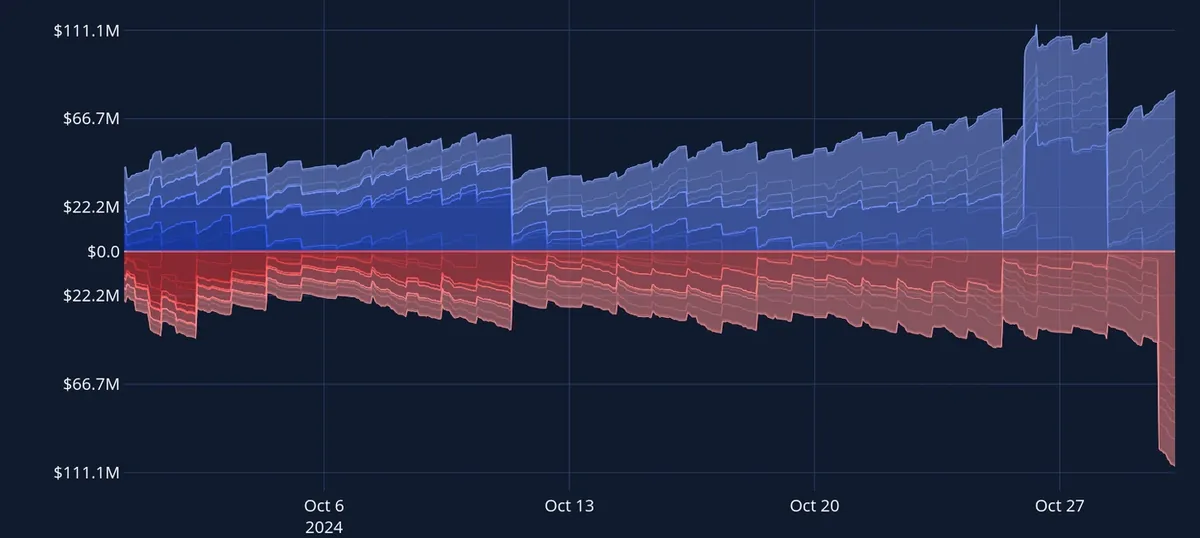
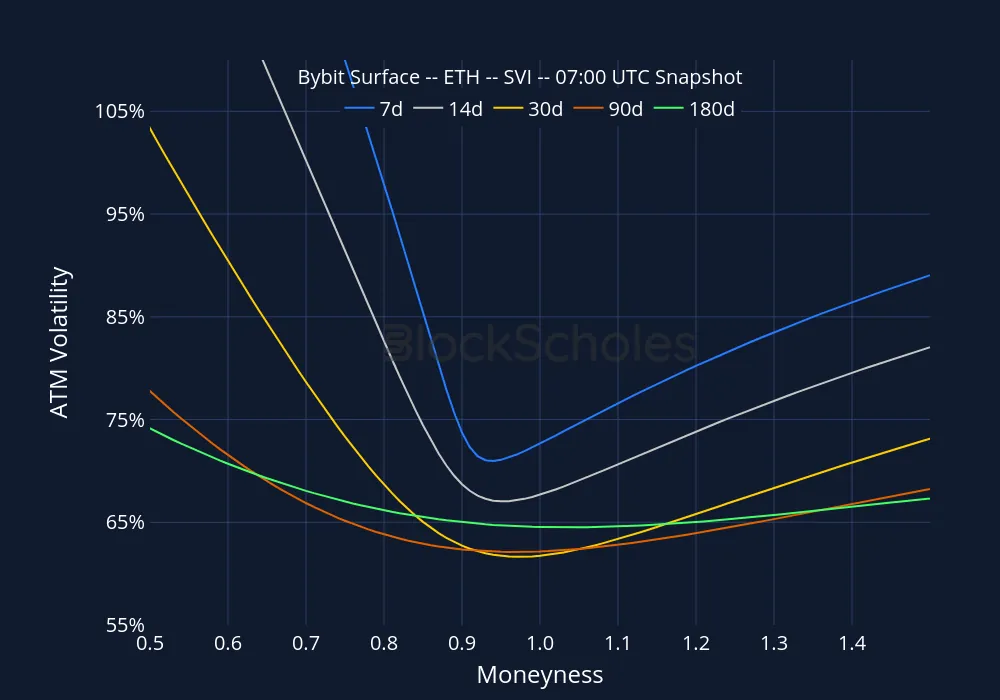
The kink in the volatility term structure near to the U.S. election has evolved into a significant inversion at the front end, mirroring the structure seen in BTC. This shift highlights increased demand for short-dated options, reflecting rising market expectations around potential election-driven turbulence. ETH has rallied alongside BTC, though remaining far below its all-time high. This steady upward drift with few pullbacks has kept realized volatility low, in stark contrast to the elevated implied volatility levels seen in the options market. Despite signs of bullishness elsewhere, we’ve seen a sharp increase in open interest for short-dated put options, whose open interest now far surpasses that of calls.
BYBIT ETH OPTIONS VOLUMES
BYBIT ETH OPTIONS OPEN INTEREST
ETH Implied Volatility Mirrors BTC’s
BYBIT ETH VOLATILITY TERM STRUCTURE — Volatility at a 14-day tenor has risen as the U.S. election premium moves forward along the term structure.
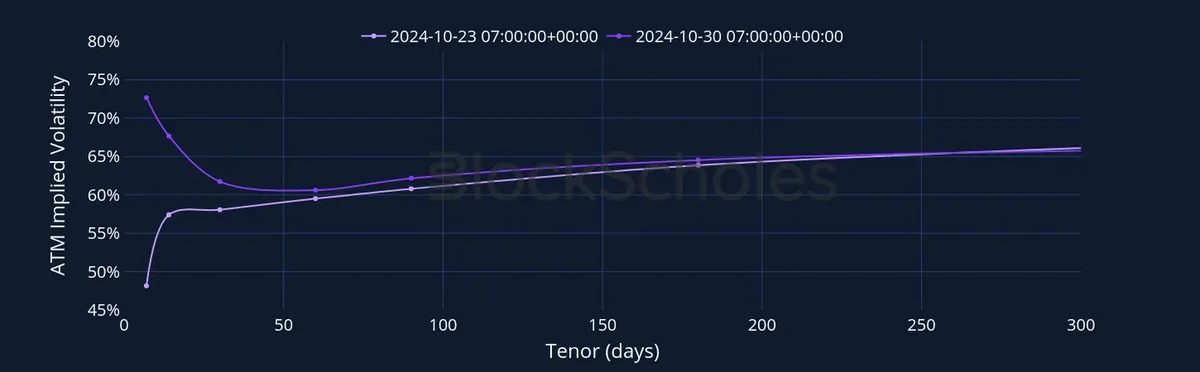
BYBIT ETH VOLATILITY TERM STRUCTURE — The 7-day tenor implied volatility growth mirrors that of BTC, rising sharply and overtaking levels at other tenors.
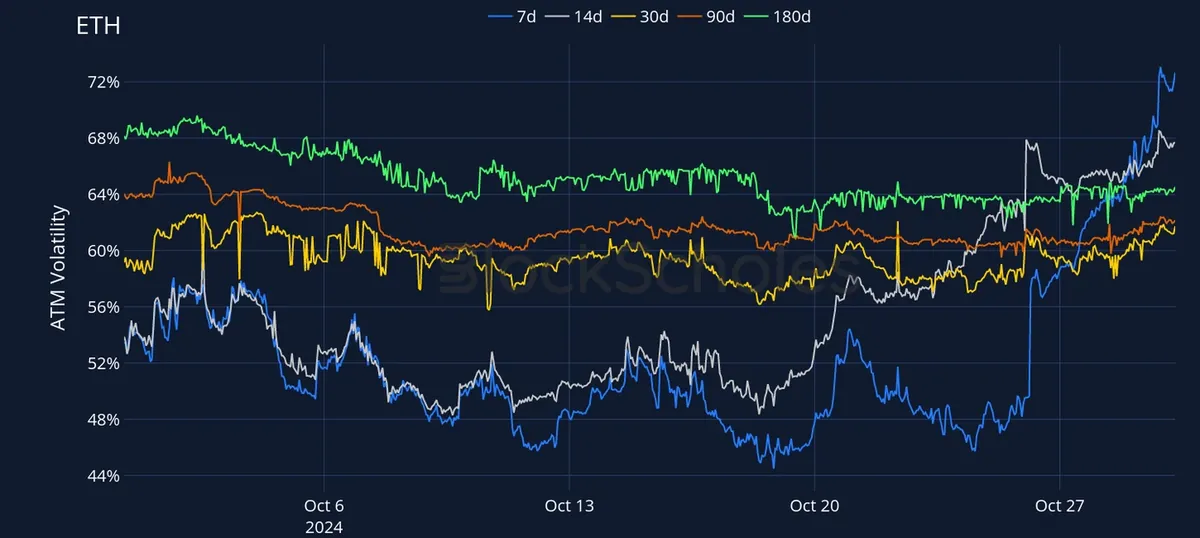
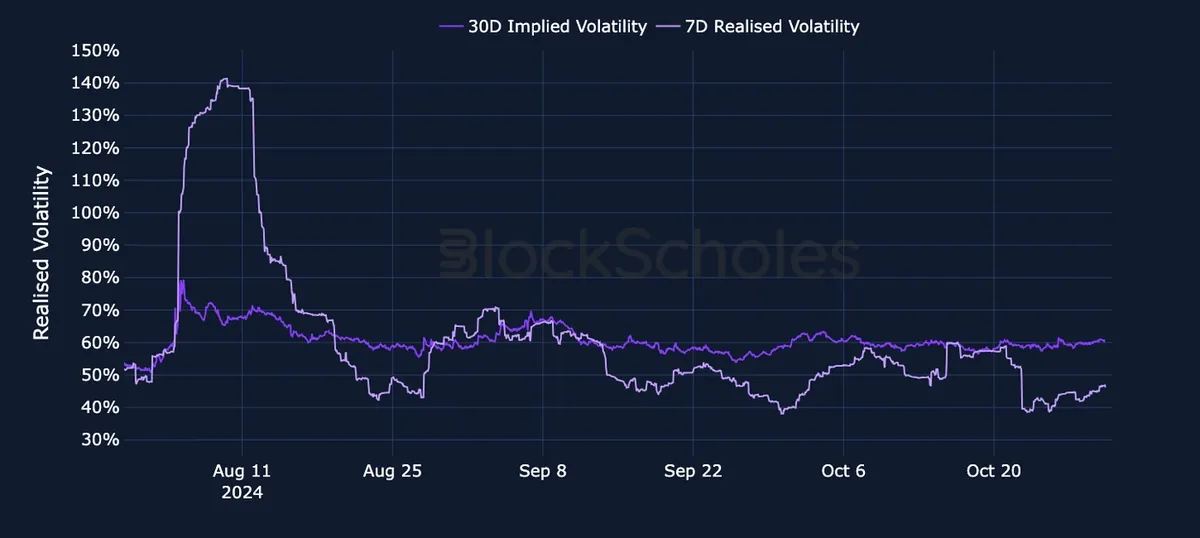
BYBIT ETH IMPLIED AND REALIZED VOLATILITY — Realized volatility remains low, despite the ETH spot rally and inversion of the term structure.
Volatility by Exchange
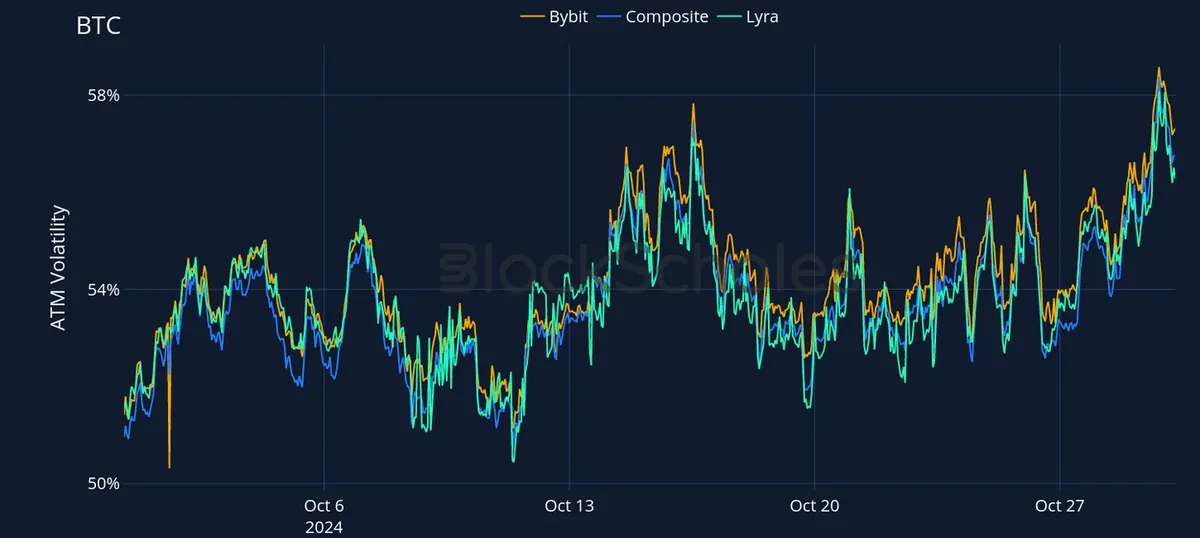
BTC, 1-Month Tenor, SVI Calibration
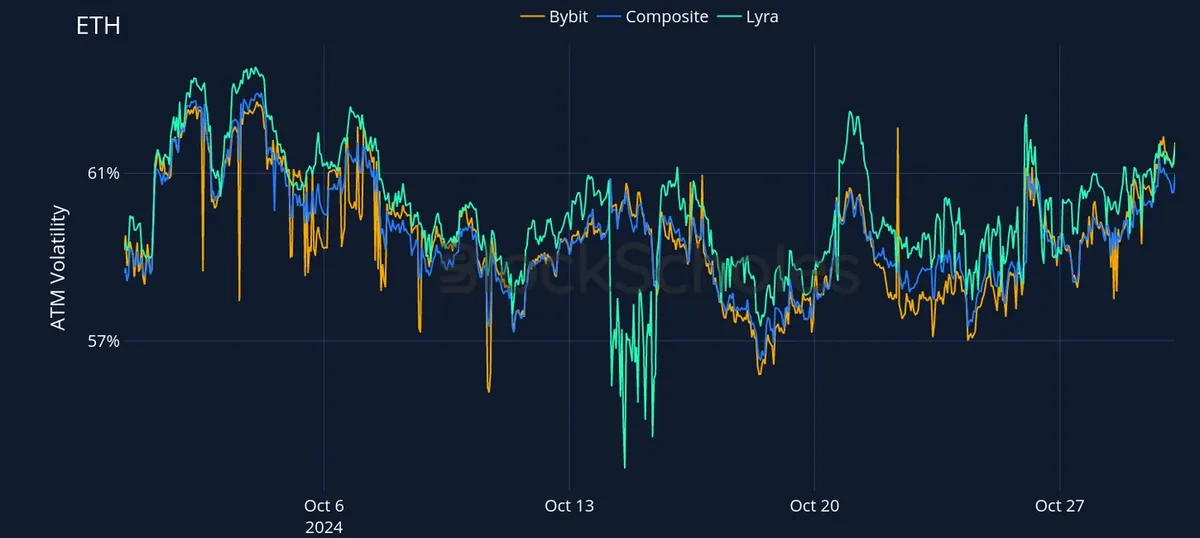
ETH, 1-Month Tenor, SVI Calibration
Bybit Volatility Surface
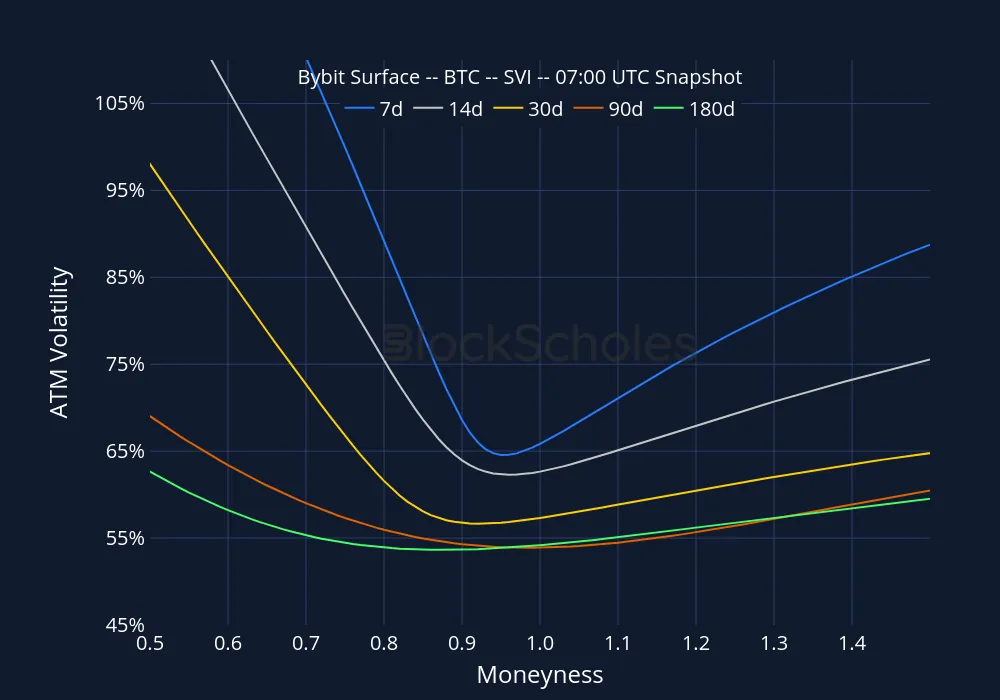
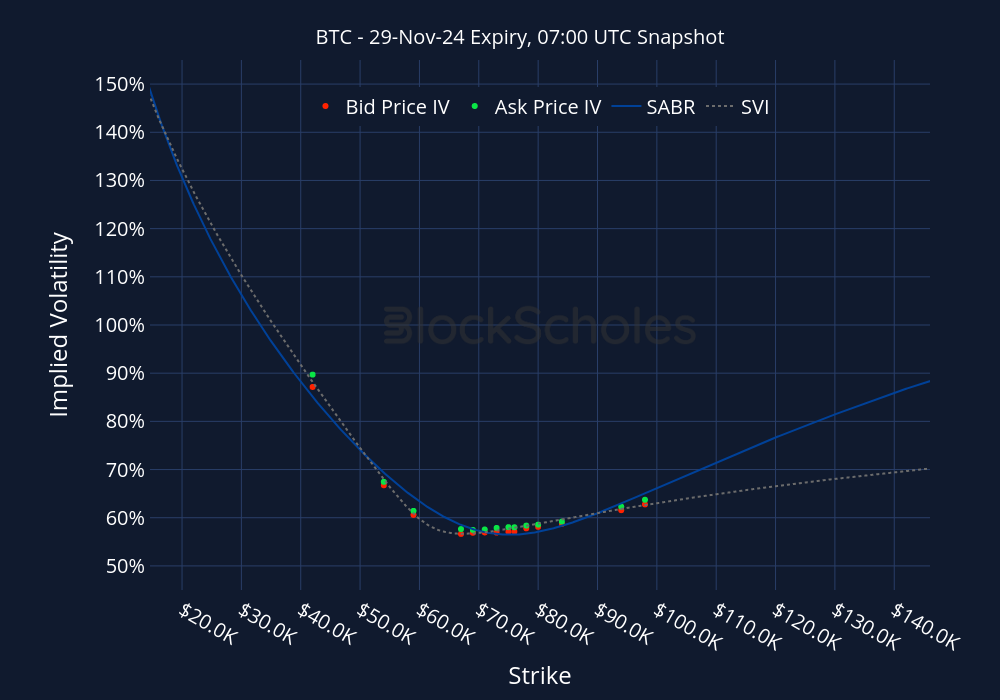
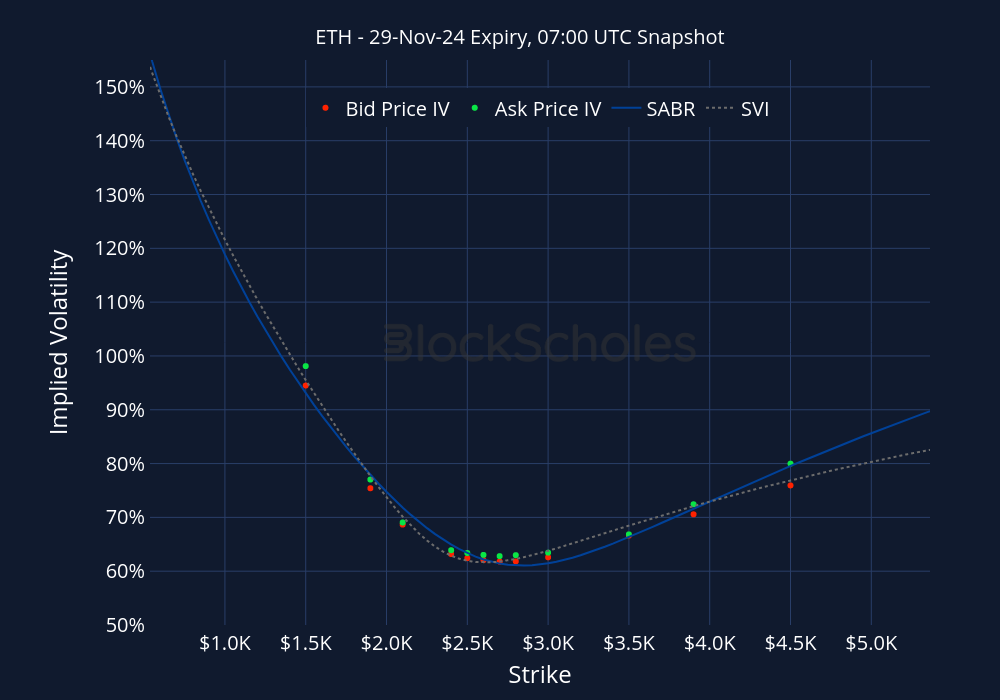
Listed Expiry Volatility Smiles