By Andrew Melville · 31 Dec 2024 · 8 MIN READ
Block Scholes x Bybit Crypto Derivatives January 3rd 2025
Far from the explosion in volatility expected by some commentators, December’s end-of-year options expiration event has resulted in a collapse in realized volatility levels back to the bottom of their December range. Perpetual swap open interest levels remained consistent throughout the event, suggesting that perp markets weren’t used to hedge a significant proportion of the delta of the expired options contrasts, perhaps explaining the lack of volatility that materialized as they expired.
Key Insights
Far from the explosion in volatility expected by some commentators, December’s end-of-year options expiration event has resulted in a collapse in realized volatility levels back to the bottom of their December range. Perpetual swap open interest levels remained consistent throughout the event, suggesting that perp markets weren’t used to hedge a significant proportion of the delta of the expired options contrasts, perhaps explaining the lack of volatility that materialized as they expired
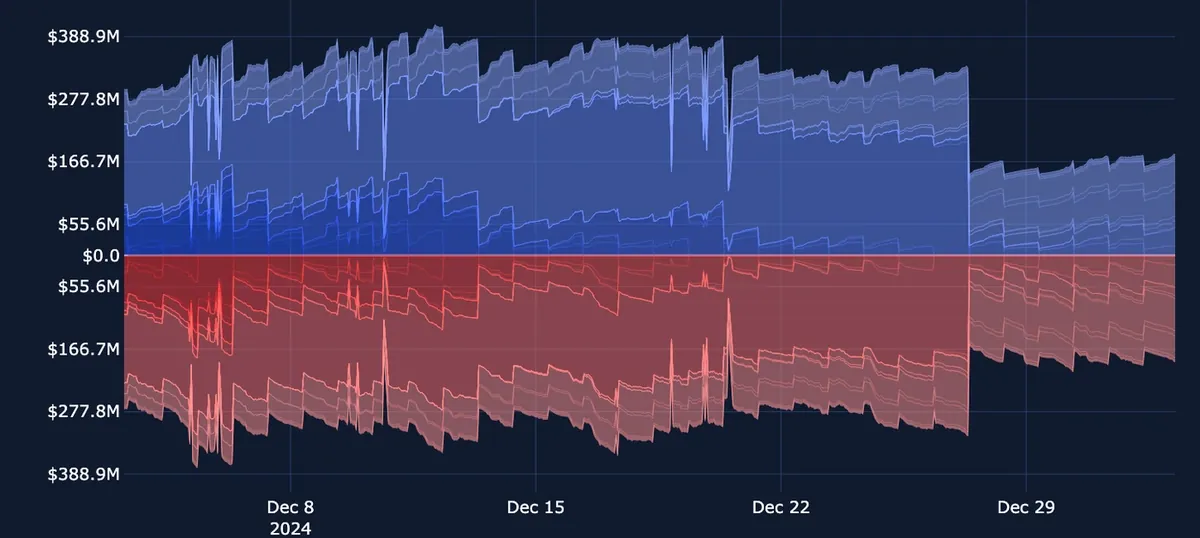
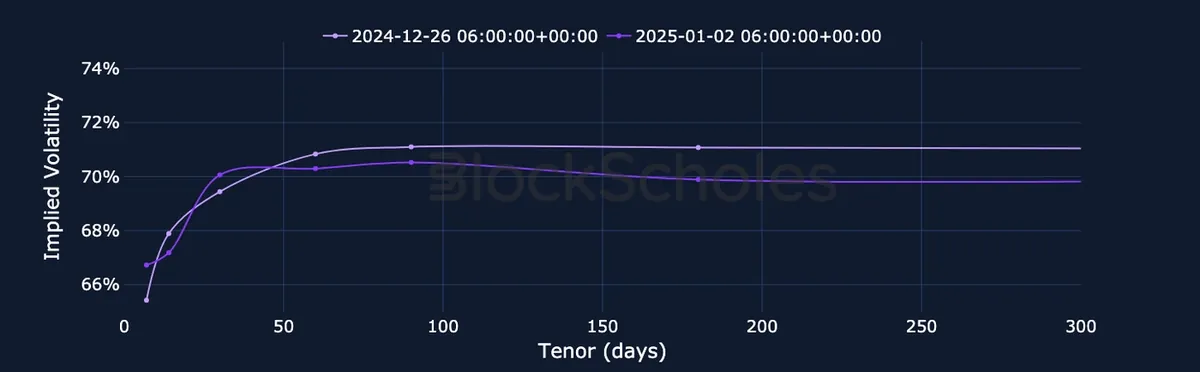
Much of the expired open interest in BTC and ETH markets hasn’t been reopened in new options positions, but the balance of open positions in calls and puts remains roughly the same as before the event. However, ETH options markets continue to price for a relatively higher level of implied volatility as compared to BTC, especially at short-tenor expirations. As a result, ETH’s term structure for at-the-money implied volatility remains flat, while BTC’s indicates a relatively cheaper level of options exposure at its front end.
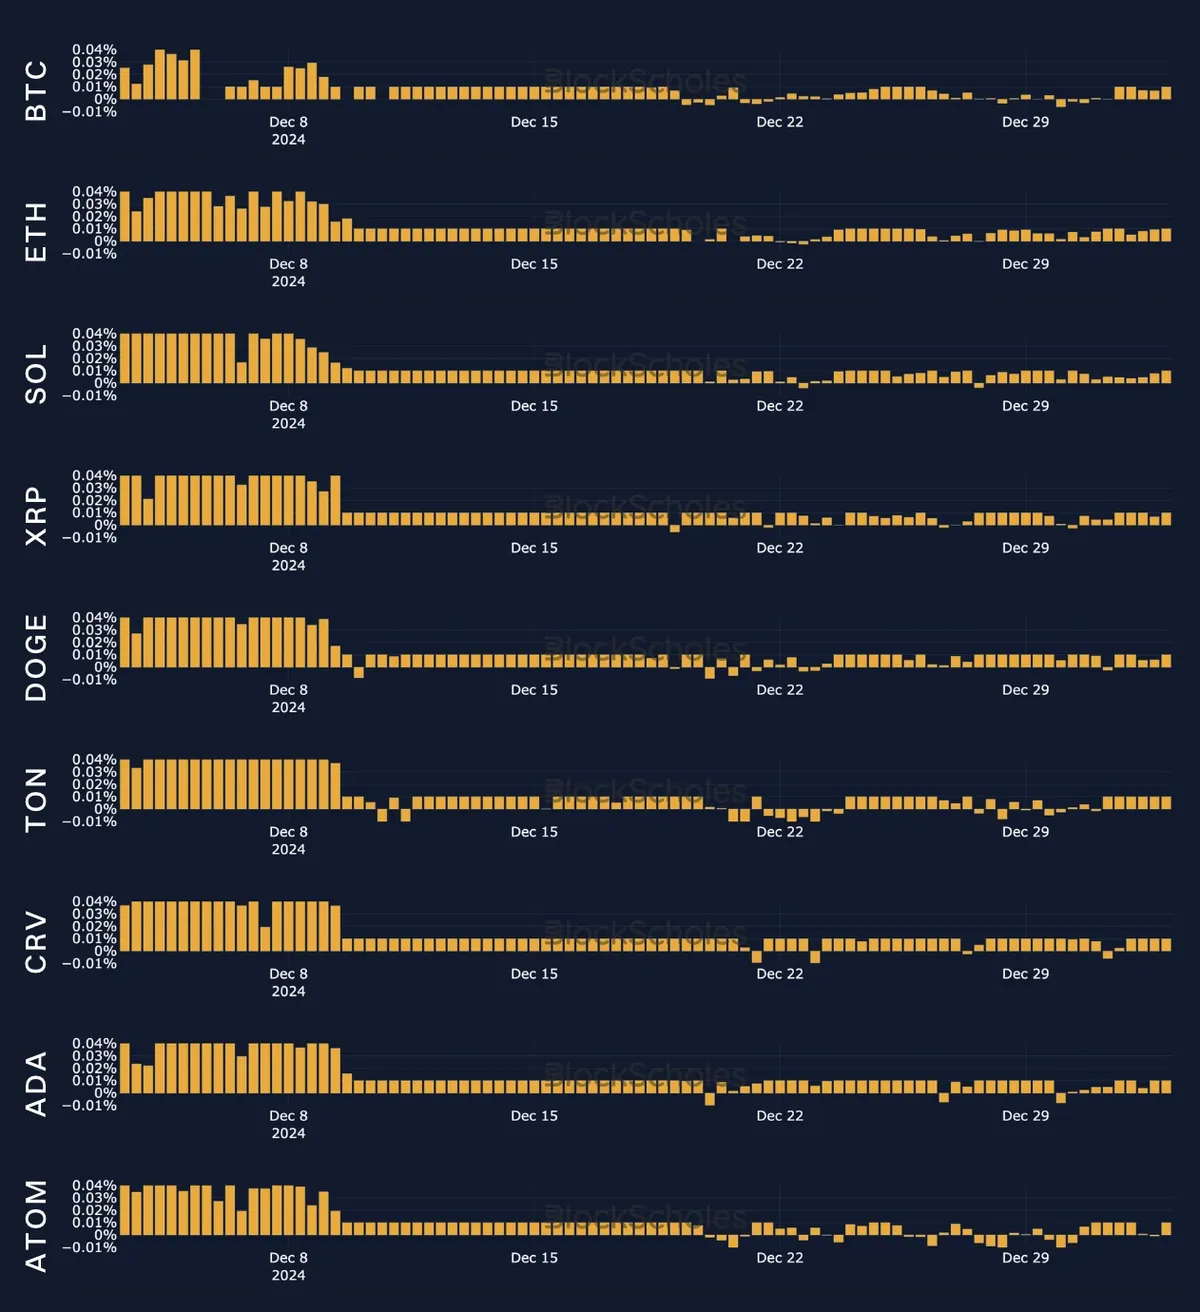
Perpetuals: With lower volatility and a lack of decisive spot movements to drive them, funding rates across almost all tokens have each responded in a similar way to each other as the market ranges together.
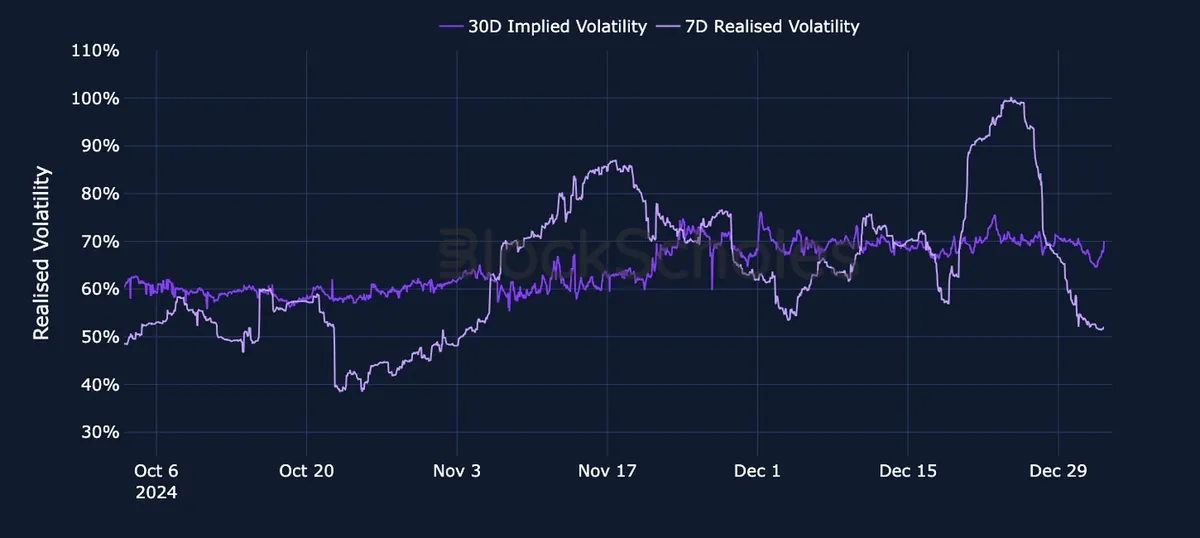
Options: BTC’s term structure is noticeably lower and steeper than ETH’s. Realized volatility levels have collapsed below levels of implied volatility following December’s end-of-year options expiration non-event.
Block Scholes BTC Senti-Meter Index
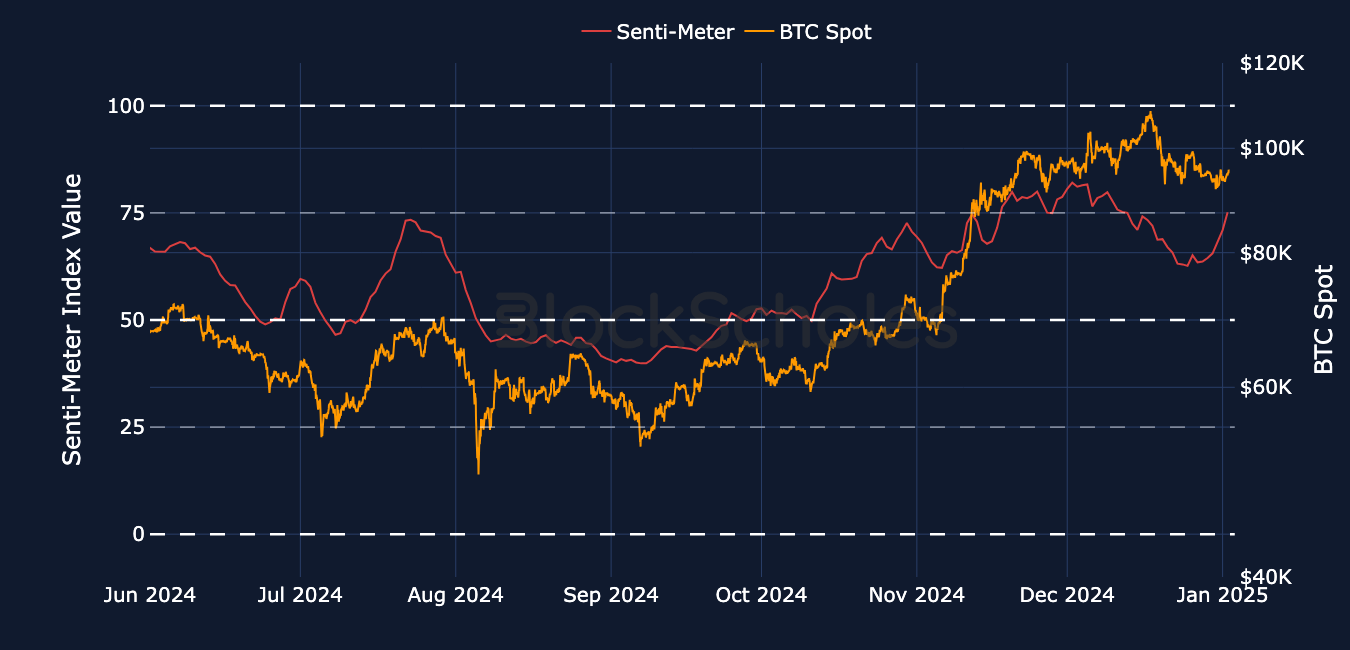
Block Scholes ETH Senti-Meter Index
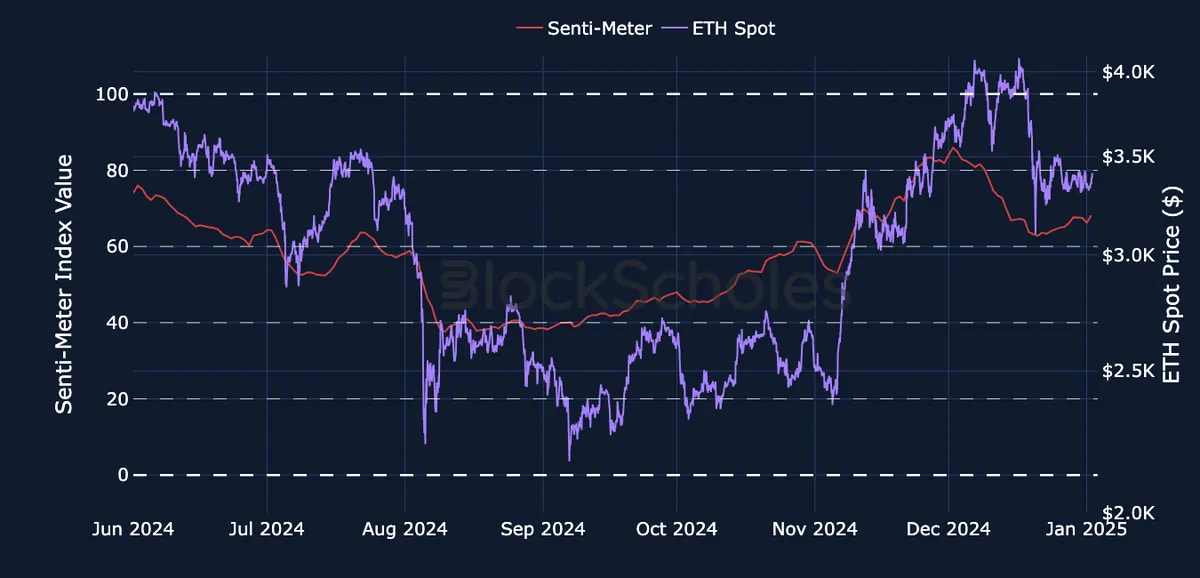
Block Scholes’ Senti-Meter index aggregates the funding rate, future-implied yield, and volatility smile skew into a single expression of sentiment in derivatives markets — see more in the methodology article here.
Macro, Tech & Regs
Macro Calendar & Recent Events
- China Bond Issuance — Dec 24, 2024 — Policymakers in China are reportedly planning to sell a record 3 trillion yuan ($411 billion) in special Treasury bonds in 2025 to strengthen fiscal policy and boost domestic consumption. This follows the PBOC’s changing stance on monetary policy from “prudent” to “moderately loose.” Stimulus from both sides could help bolster risk-asset appetite from Chinese consumers.
- Chicago PMI U.S. — Dec, 30, 2024 — The Chicago Purchasing Managers Index fell to 36.9 in December 2024 from 40.2 in November. This is well below the level of 50, indicating the 13th consecutive month of contraction in the Chicago manufacturing sector, which is often taken as a proxy for that of the entire nation.
- U.S. S&P 500 End-of-Year Performance — Dec 31, 2024 — The S&P 500 ended the year up 28%, following a 26% performance in 2023. However, the rally has largely been concentrated among only a few of the top companies in the index, which is something to watch for in 2025.
- Initial Jobless Claims— Jan 2, 2024 — Referencing the week commencing Dec. 28, 2024, jobless claims are expected to be pushed slightly up to 225,000 as compared to a previous figure of 219,000.
- U.S. Nonfarm Payroll Report — Jan 10, 2025 — The NFP report, usually available on the first Friday of every month, has been moved to next week due to the holiday season. The most recent report showed the U.S. economy adding 227,000 jobs in November. A figure close to this for December will likely raise the probability of a rate pause in January 2025.
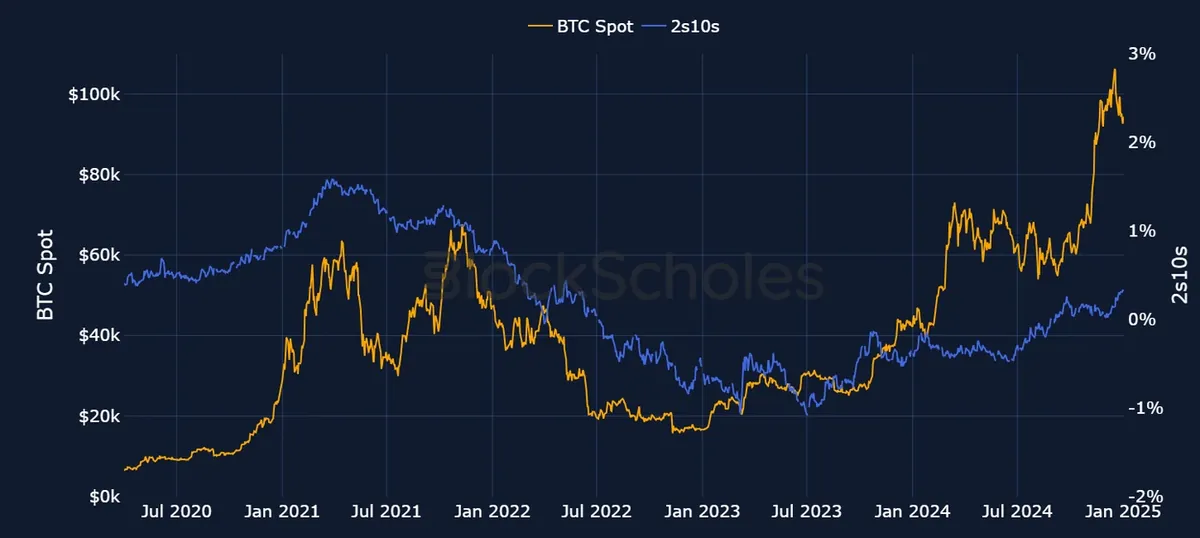
Yield Curve Steepening — Since the Federal Reserve interest rate cut in September, the 2s10s yield curve (the difference between the yield on the ten-year and two-year U.S. Treasury bonds) has been steepening, as long-end yields have been rising faster than short-end yields.
Trending News
- MicroStrategy released news of its latest acquisition (of 2,138 bitcoins at an average price of $97,837) during the period from Dec 23–29, 2024. This equates to a total cost of approximately $209M.
- XRP rallied to $2.40 (+15%), in line with a broader crypto resurgence. [Ripple’s monthly 500M escrow execution on Jan 1, 2025, included a bullish memo: “January 20 is around the corner. Donald Trump will be in the WH, and we are going to make crypto great again!"
Open Interest Remains Firm Despite Lower Volatility
Key Insights
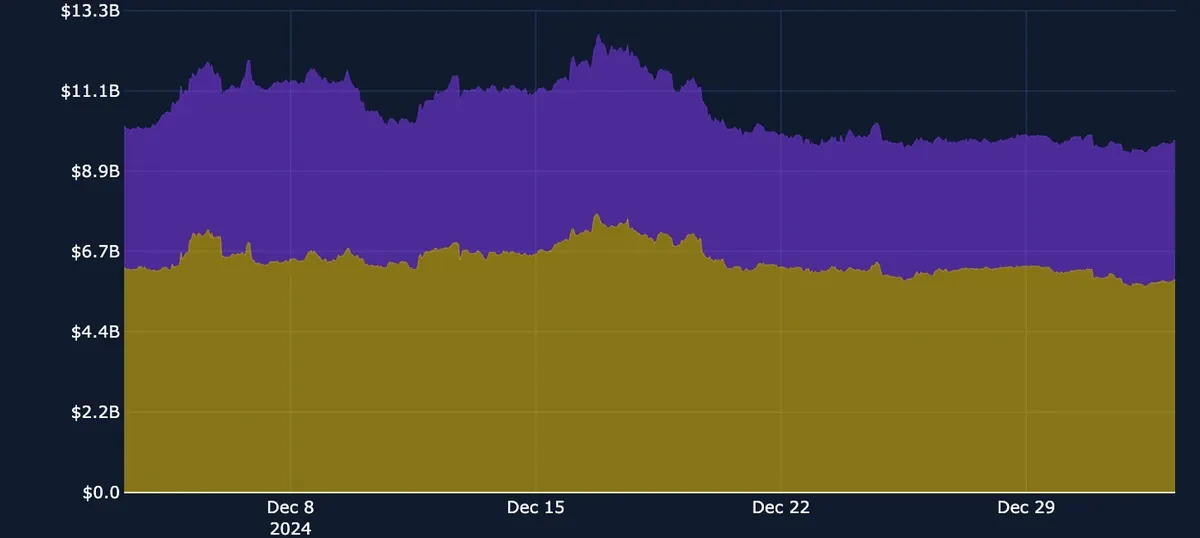
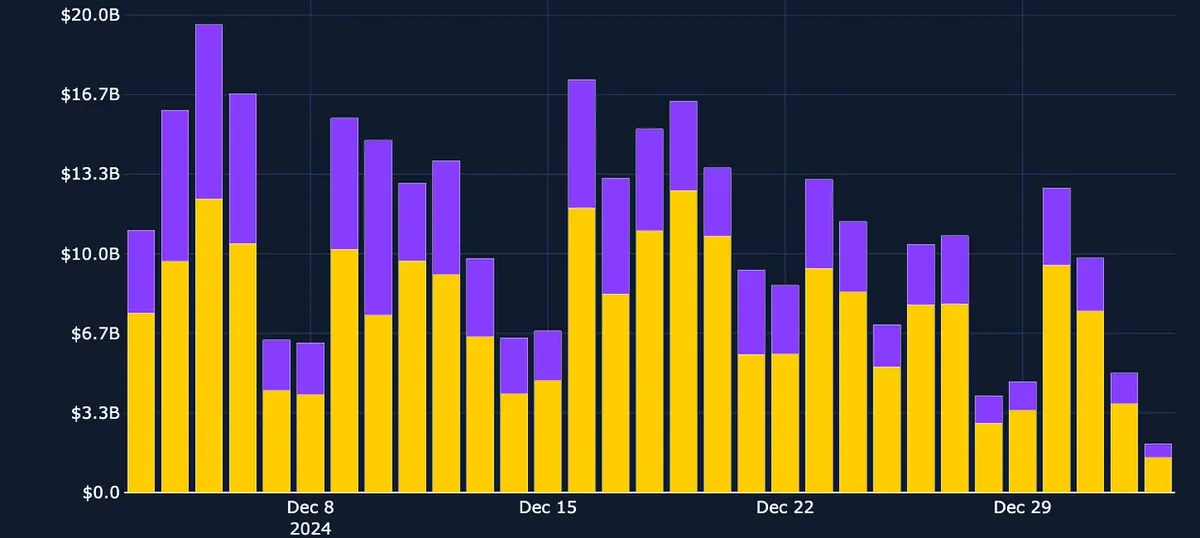
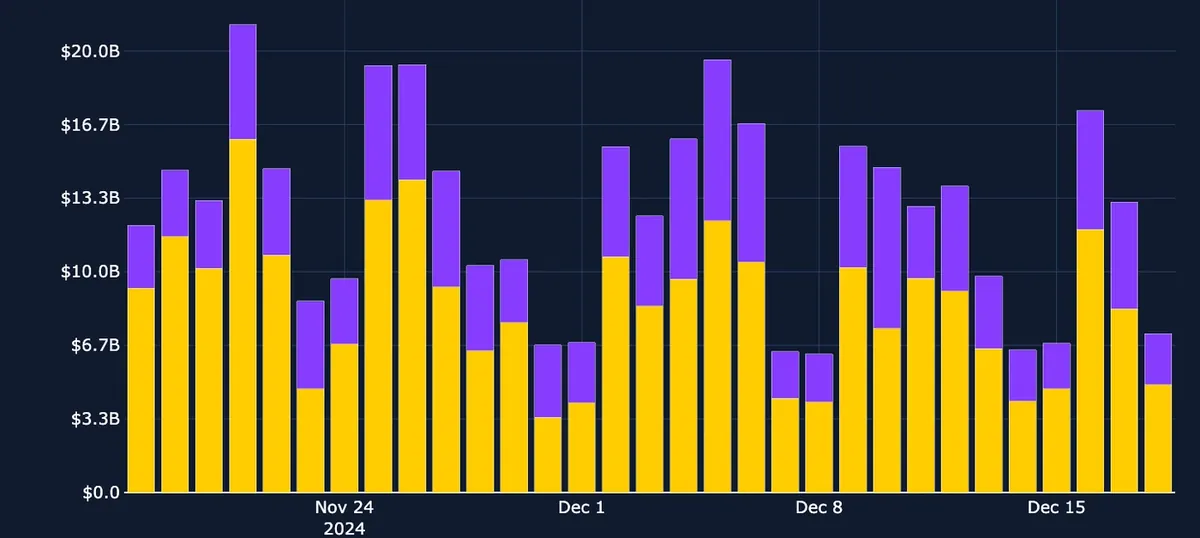
While open interest in perpetual swaps markets for both BTC and ETH has yet to regain its early December highs, levels have remained strong as December’s large end-of-year options expiration event had little impact. This indicates that these perpetual swap markets weren’t being used to hedge a significant proportion of the delta of those expiring options contracts, which may also explain the lack of volatility that the market experienced during their expiration. Instead, trade volumes have been noticeably lower during the winter holiday period, aligning with the collapse in realized volatility levels back to the bottom of their December range.
Bybit Perp BTC & ETH Open Interest — While open interest has yet to regain early December highs, it remains strong during the end-of-year options expiration.
Bybit Perp Trading Volumes — Trading Volume has been noticeably lower during the winter holiday period.
Funding Rates Range Together
As they did last week, funding rates have remained responsive to spot price movements. This is in contrast to the prevailing bullish sentiment that dominated positioning in late November and early December 2024. The lower level of realized volatility during the holiday period, as well as the non-event of the end-of-year options expiration, means that funding rates haven’t been driven by strong and decisive moves in spot prices. However, we continue to see the same clustering of similar moves in funding rates for different coins, suggesting a broader driver of market sentiment.
BTC Options
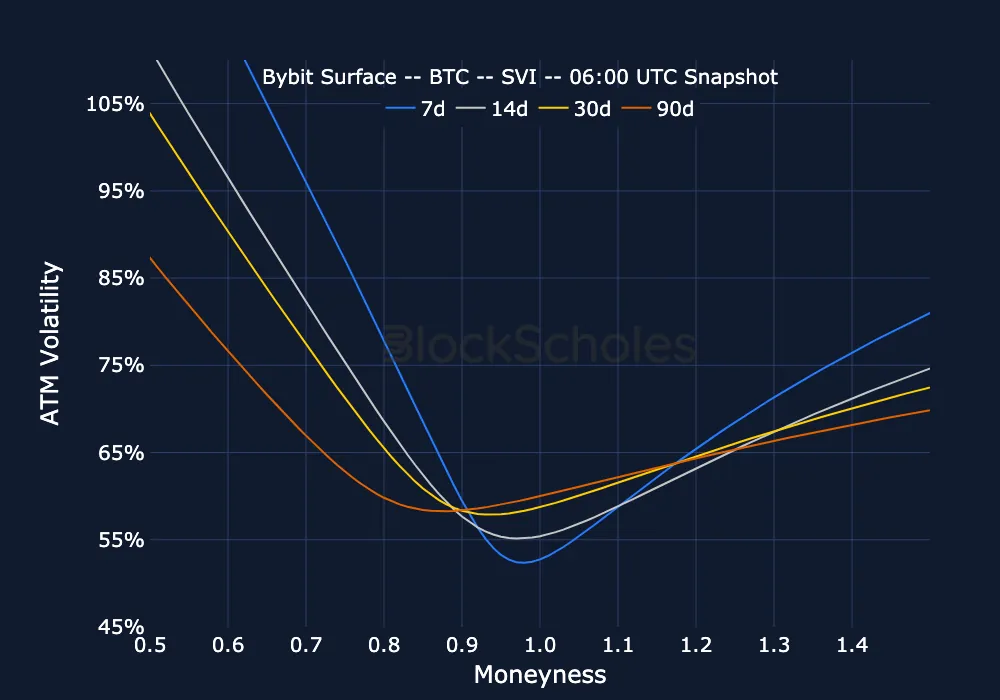
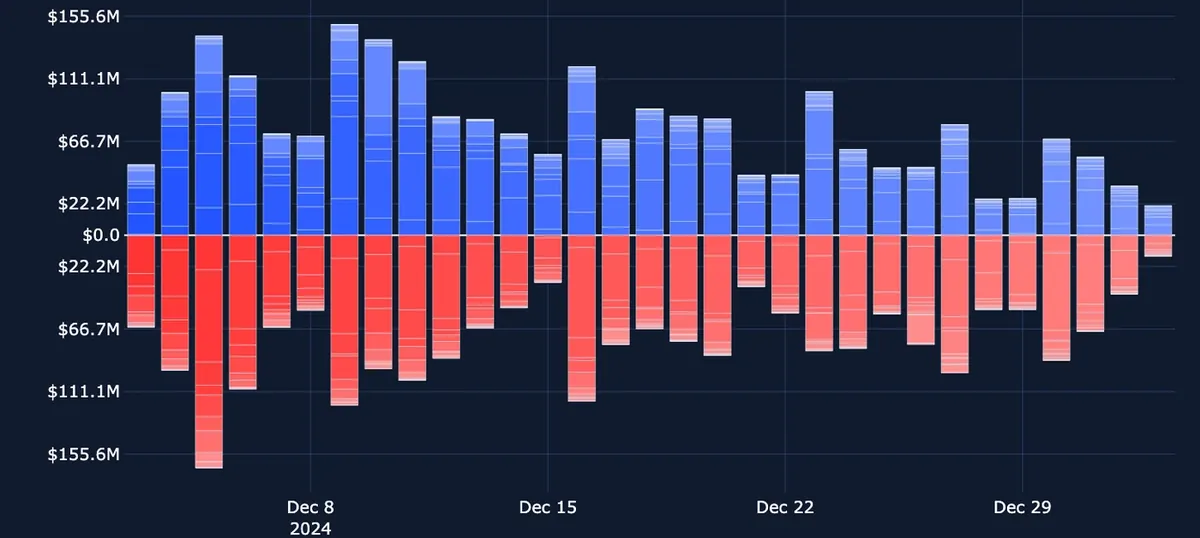
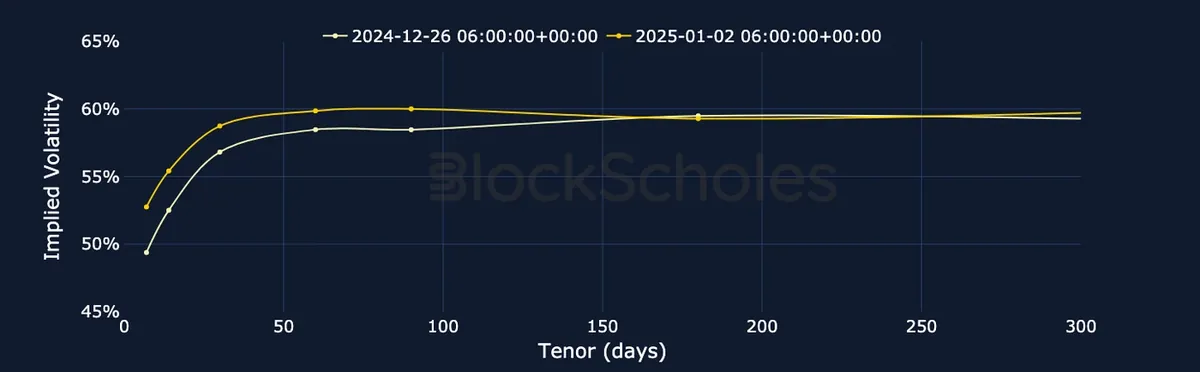
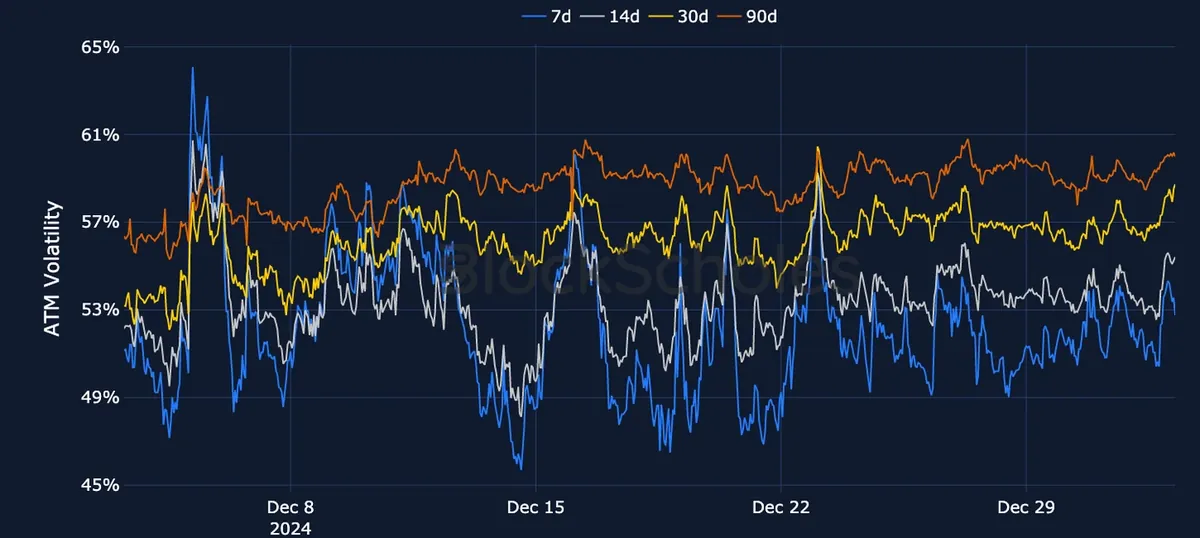
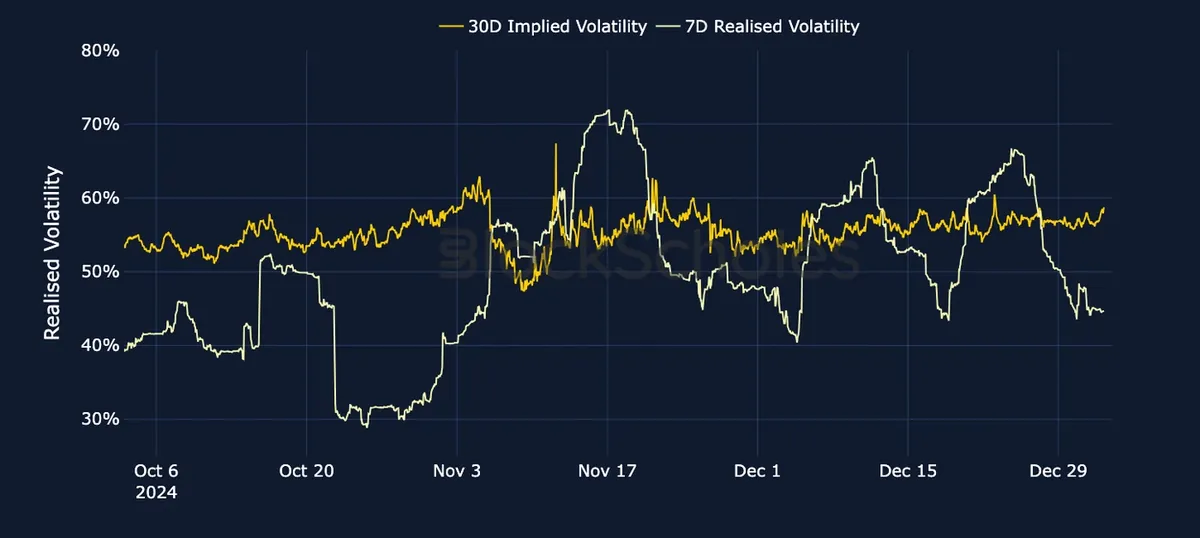
The expiration of December’s end-of-year options contracts didn’t result in an explosion of volatility, as was predicted by many commentators. Instead, realized volatility has cratered to the bottom end of its recent range. With this, the implied volatility term structure has remained steep, relative to both its own recent behavior and ETH’s term structure. Longer-dated implied volatility remains firmly locked at close to 57%, while 1-week tenor at-the-money options are trading about 5 points lower. Much of the expired open interest hasn’t yet been rolled over into new positions at the beginning of the year, and the balance between puts and calls remains as neutral as it was before the event. As a result, the positioning in BTC’s options markets is relatively neutral, without the same amount of leverage with which it began December.
BYBIT BTC OPTIONS VOLUMES
BYBIT BTC OPTIONS OPEN INTEREST
BTC’s Term Structure Remains Steep
BYBIT BTC ATM TERM STRUCTURE — The same steep term structure appears as one week ago.
BYBIT BTC SVI ATM IMPLIED VOLATILITY — The steeper term structure has been unchanged over the last week, between 49% and 60% across tenors.
BYBIT BTC IMPLIED AND REALIZED VOLATILITY — Realized volatility has fallen back to sub-45% levels, while implied volatility remains firmly locked at close to 57%.
ETH Options
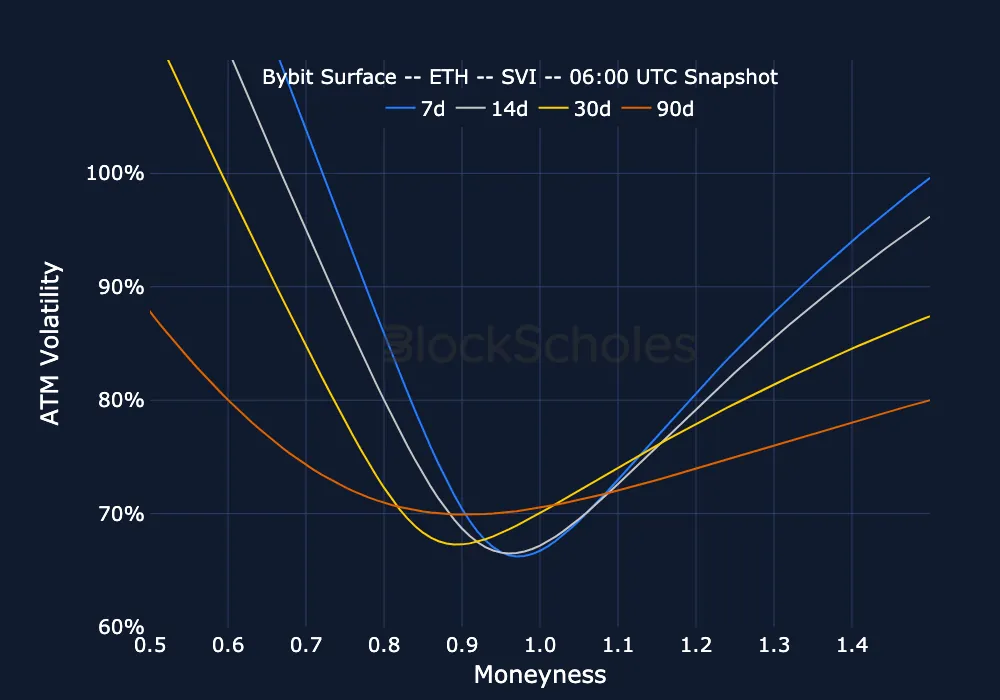
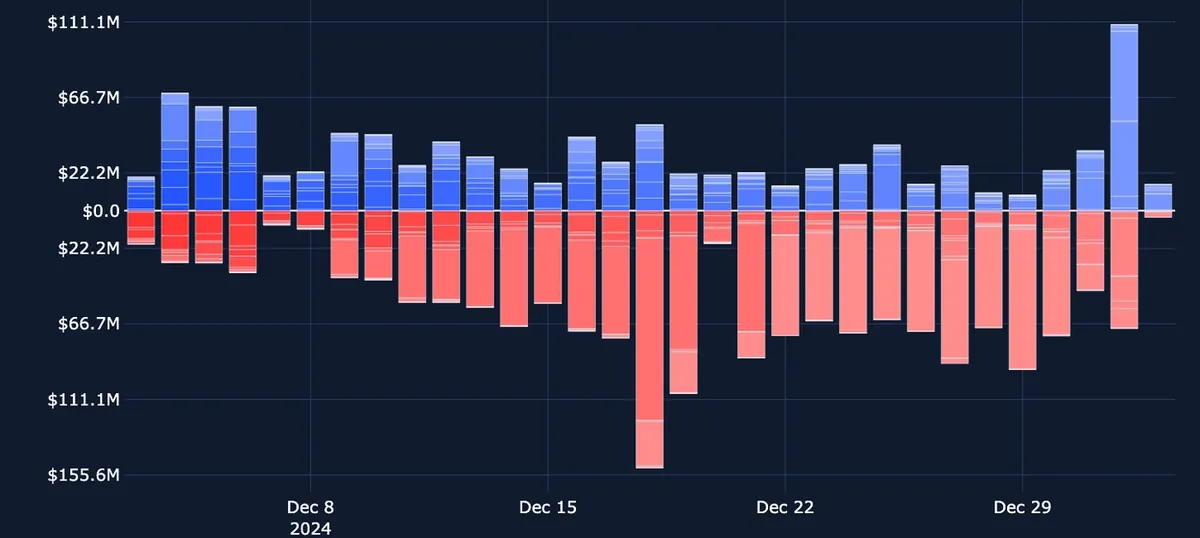
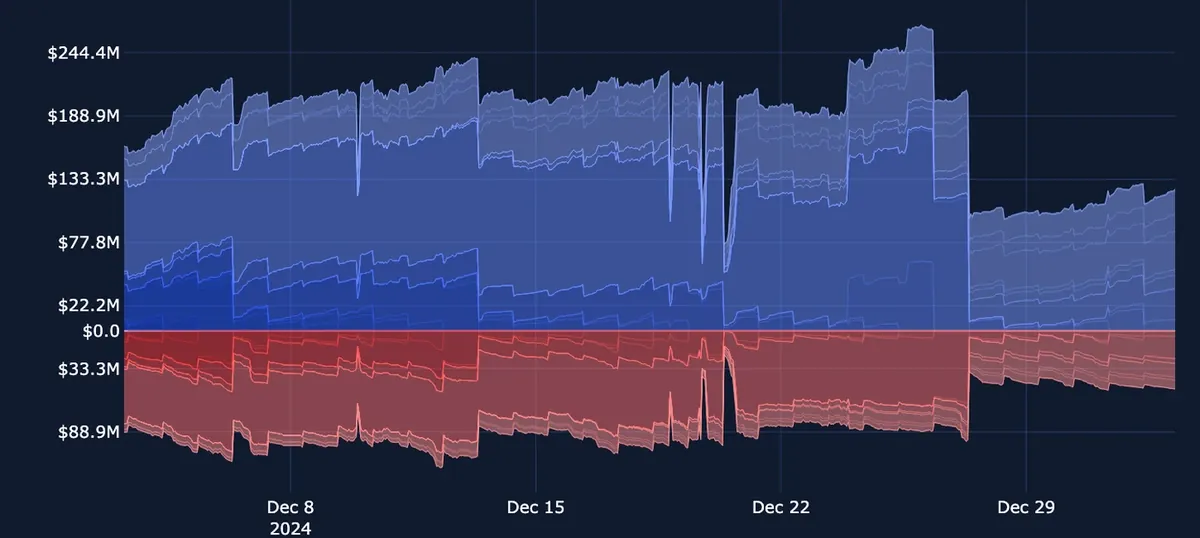
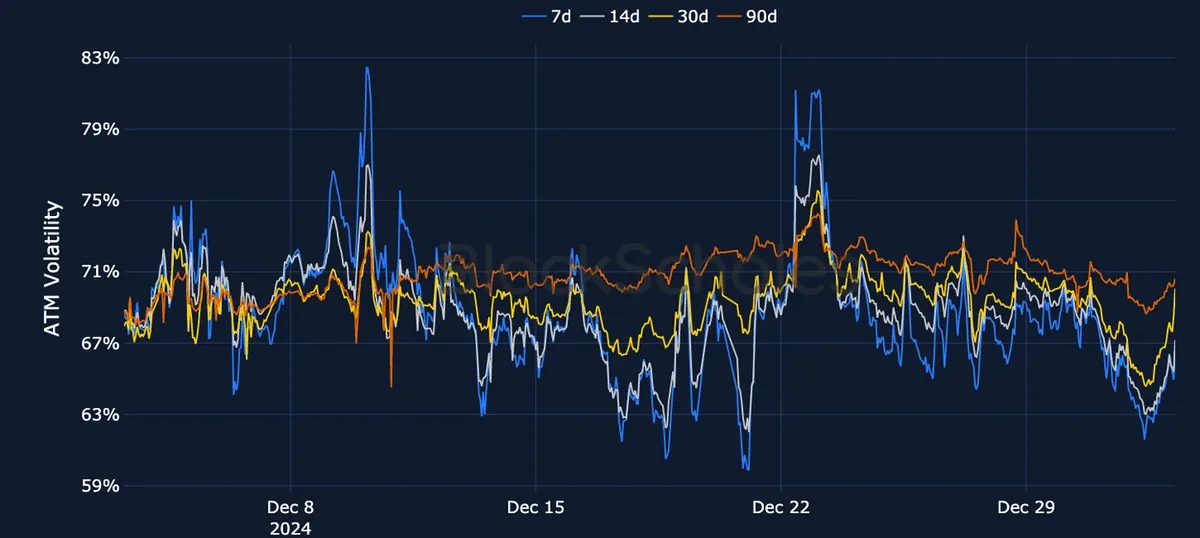
A late December 2024 spike in realized volatility didn’t sustain into the new year, and ETH’s spot price has most recently traded with a level of volatility below that of short-tenor implied volatility. Surprisingly, the term structure of implied volatility has completed a round trip of steepening and re-flattening over the past week that contrasts with BTC’s slightly steeper shape. This indicates that ETH’s options market is currently pricing for a relatively higher level of volatility in spot price movements for the short term. While the expiration of a significant proportion of the options open interest at the end of December didn’t result in a rollover of positions to later expirations, call options continue to dominate the market, and have grown throughout the beginning of 2025.
BYBIT ETH OPTIONS VOLUMES
BYBIT ETH OPTIONS OPEN INTEREST
Realized Volatility Collapses, Term Structure Remains Flat
BYBIT ETH VOLATILITY TERM STRUCTURE — The term structure has completed a round trip of steepening and re-flattening over the past week.
BYBIT ETH SVI ATM IMPLIED VOLATILITY — The term structure of ETH’s volatility has re-flattened in contrast to the steeper shape of BTC’s term structure.
BYBIT ETH IMPLIED AND REALIZED VOLATILITY — A late December 2024 spike in realized volatility hasn’t sustained into the new year.
Volatility by Exchange
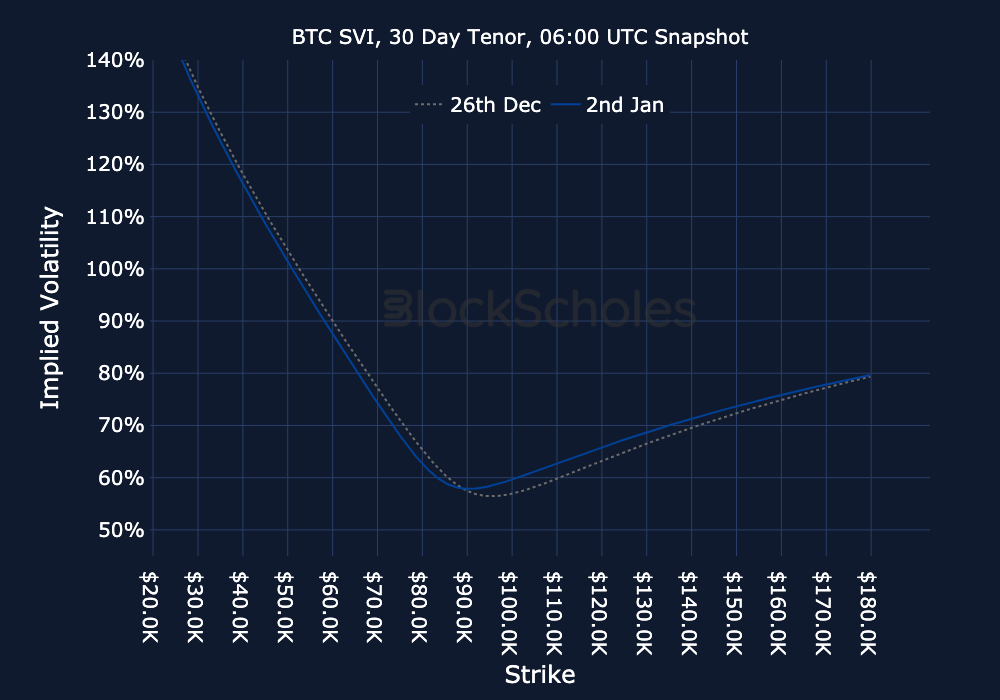
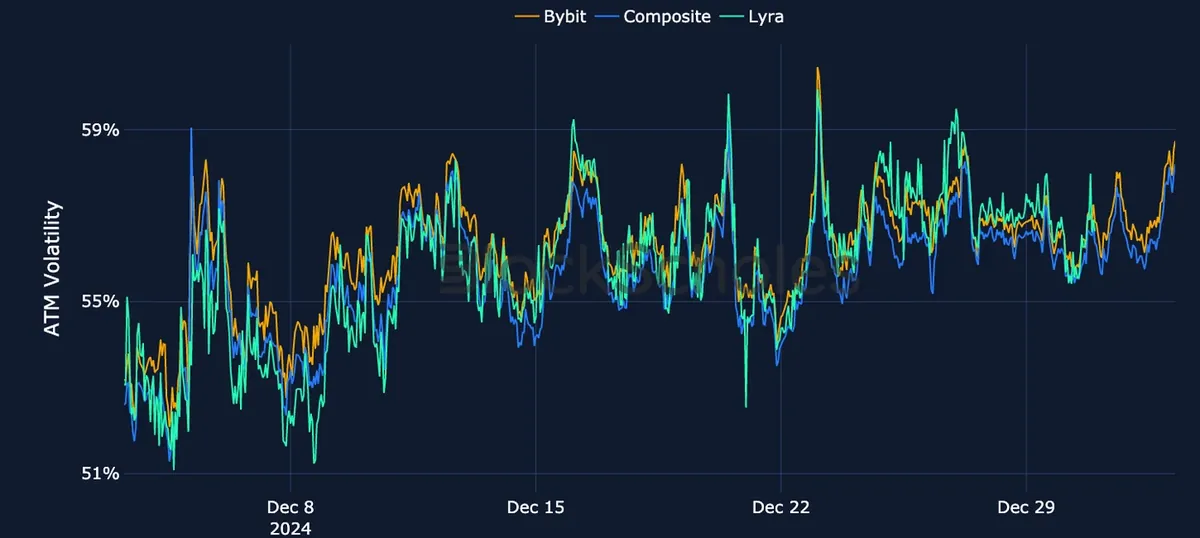
BTC, 1-MONTH TENOR, SVI CALIBRATION
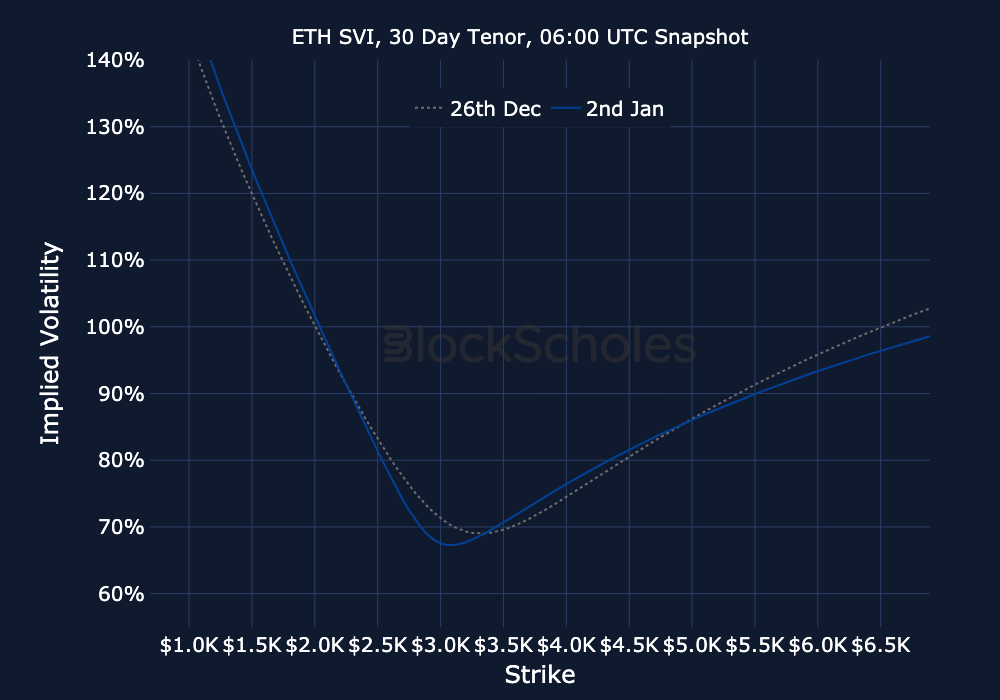
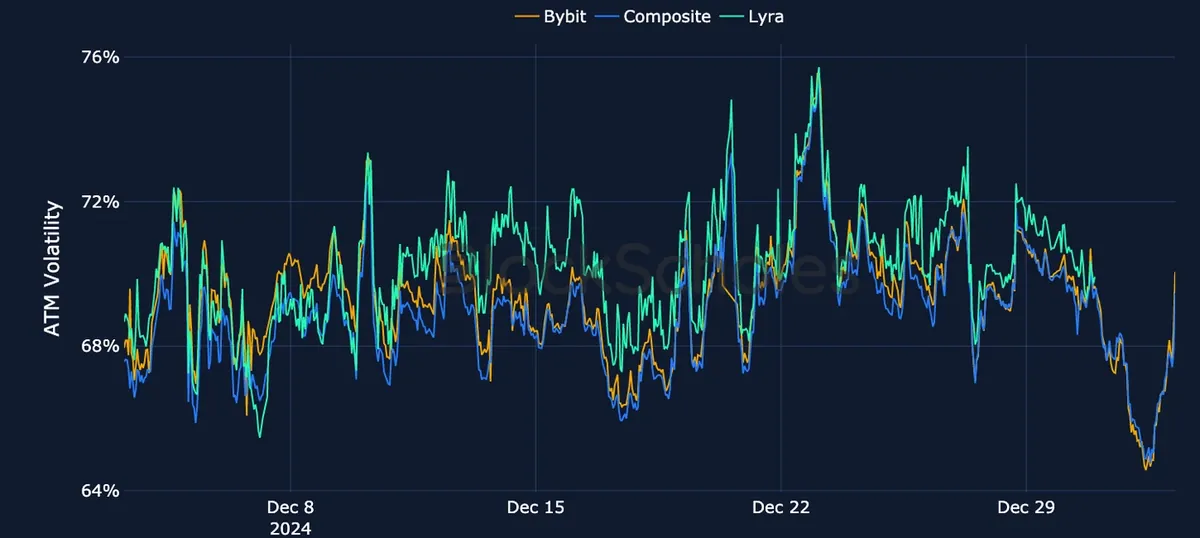
ETH, 1-MONTH TENOR, SVI CALIBRATION
Bybit Volatility Surface