By Andrew Melville · 31 Jan 2025 · 8 MIN READ
Block Scholes x Bybit Crypto Derivatives January 31st 2025
Markets experienced a significant risk-off event at the beginning of this week, as DeepSeek’s LLM announcement coincided with sharp declines in major indices and across crypto markets, despite a direct and obvious impact on the value of the crypto-asset market. Although spot markets saw a volatile selloff, open interest in perpetual swaps has remained stable, with funding rates briefly flipping negative before partially recovering. Options markets saw a surge in trading volume amid the selloff, but forward-looking volatility expectations declined. However, positioning over a longer horizon remains the same — longer dated options positions indicate a bullish sentiment.
Key Insights
Markets experienced a significant risk-off event at the beginning of this week, as DeepSeek’s LLM announcement coincided with sharp declines in major indices and across crypto markets, despite a direct and obvious impact on the value of the crypto-asset market. Although spot markets saw a volatile selloff, open interest in perpetual swaps has remained stable, with funding rates briefly flipping negative before partially recovering. Options markets saw a surge in trading volume amid the selloff, but forward-looking volatility expectations declined. However, positioning over a longer horizon remains the same — longer dated options positions indicate a bullish sentiment.
Perpetuals: The U.S. post-presidential inauguration period of persistently positive funding rates was halted by Monday’s bearish spot price action.
Options: Realized volatility has fallen back below the level of implied volatility, despite an early-week repeat of the pre-inauguration inversion of the term structure, albeit in miniature form. ETH options have retained their volatility premium over BTC options, while longer-dated volatility smiles are retaining their more bullish skew toward out-of-the-money (OTM) calls.
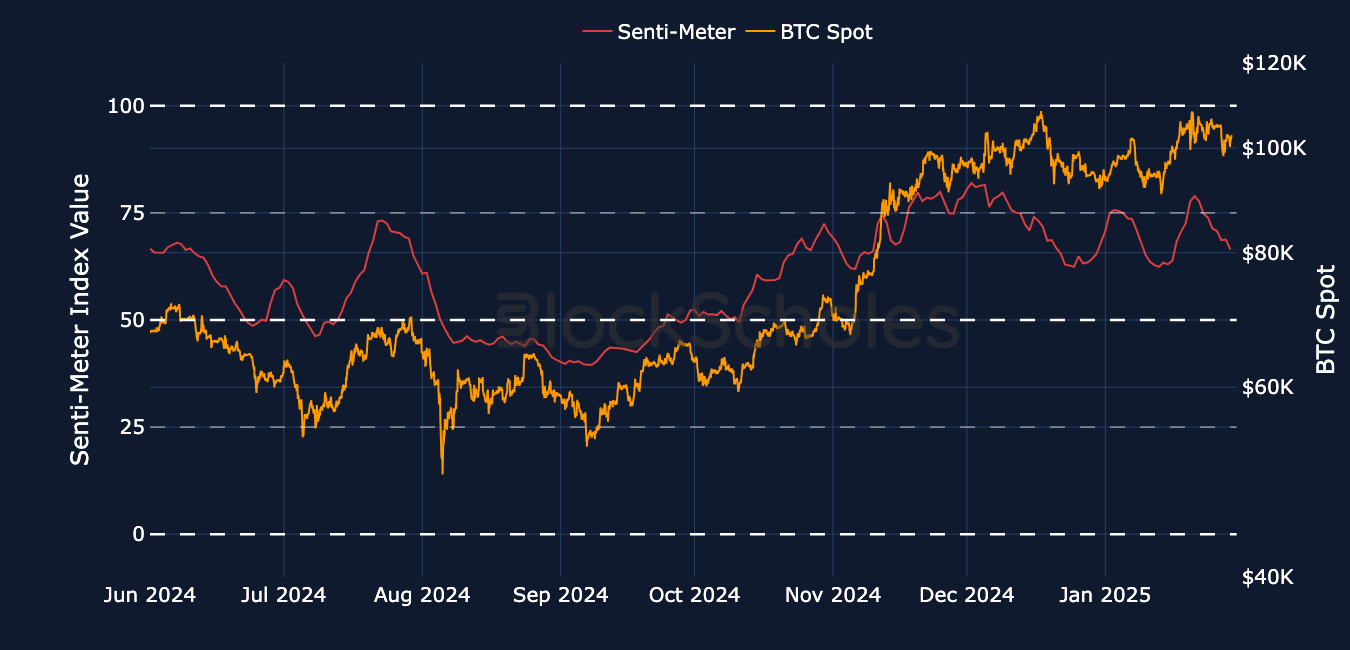
Block Scholes BTC Senti-Meter Index
Block Scholes ETH Senti-Meter Index
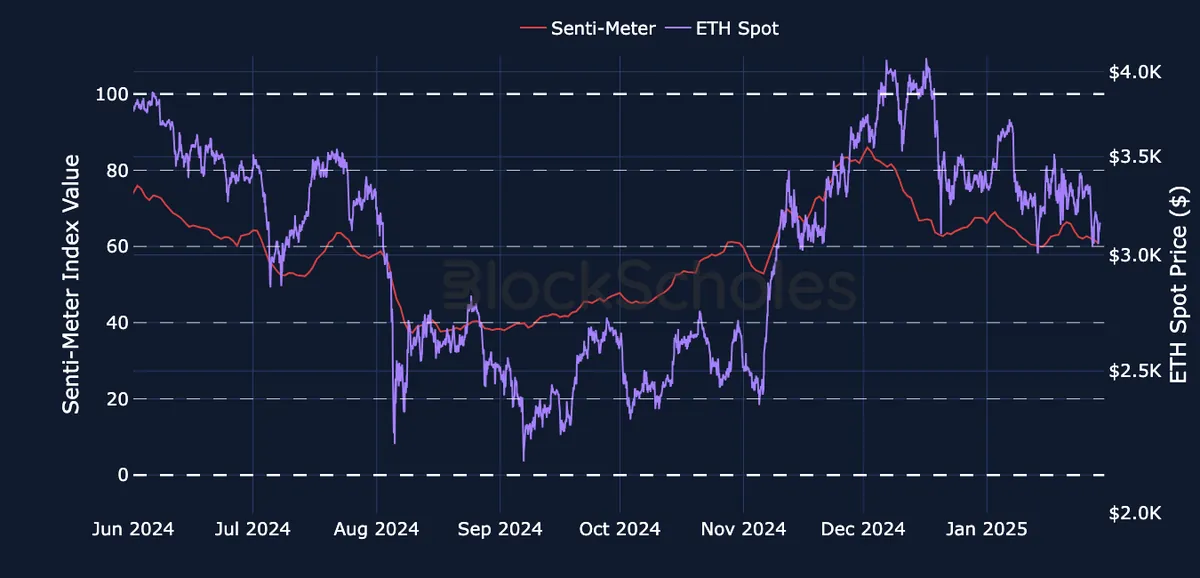
Block Scholes’ Senti-Meter index aggregates the funding rate, future-implied yield, and volatility smile skew into a single expression of sentiment in derivatives markets — see more in the methodology article here.
Macro, Tech & Regs
Macro Calendar & Recent Events
- China Purchasing Managers Index (PMI) — Jan 27, 2025 — Manufacturing PMI fell to 49.1 in January 2025, from 50.2 in December 2024 and the lowest since August 2024.
- Fed FOMC Meeting— Jan 29, 2025 — At the Fed’s first meeting of the year, FOMC members voted to keep interest rates at between 4.25%–4.5%, with the market expectation for the next rate cut in June 2025.
- ECB Monetary Meeting — Jan 30, 2025 — The ECB cut its benchmark interest rates to 2.75%, a few hours after the Eurostat data showed the Eurozone economy had not grown at all in Q4 2024.
- U.S. GDP Advanced Estimate — Jan 30, 2025 — The first estimate for Q4 annualized GDP in the U.S. is expected to show a decline in GDP growth from 3.1% in Q3 2024 to 2.7% for Q4. A figure of 2.7% for Q4 2024 will also be in line with the IMF’s estimate for annual growth in the U.S for 2025.
- U.S. PCE Inflation — Jan 31, 2025 — The Fed’s preferred inflation gauge, the PCE price index, is expected to increase to 2.5% year-over-year in January 2025, up 0.1% from the December 2025 figure.
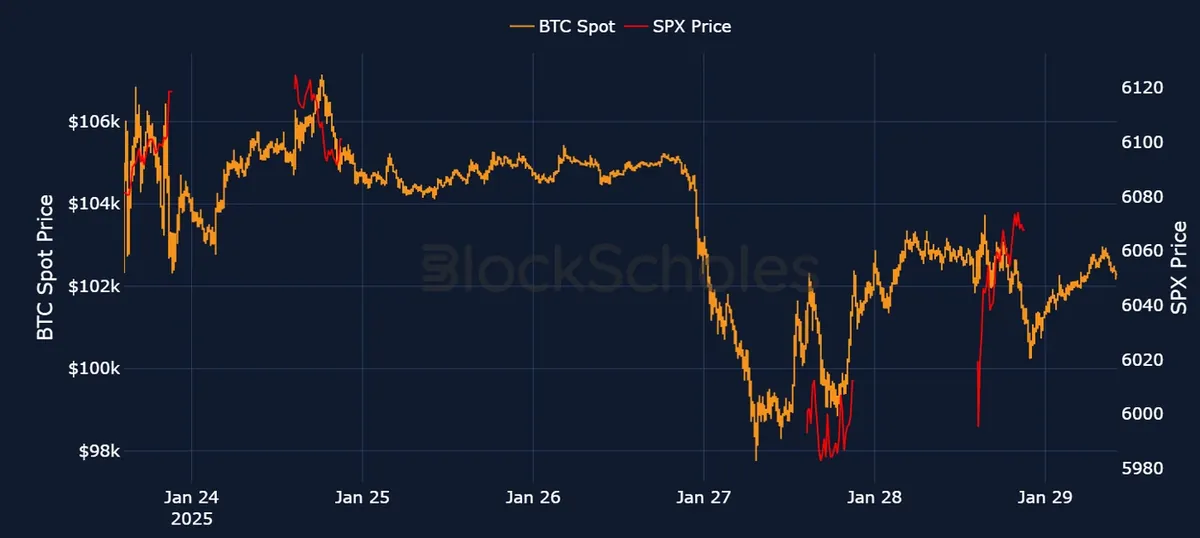
DeepSeek’s Disruptions — Only one week after the S&P 500 broke another high, the announcement of DeepSeek’s LLM resulted in a significant risk-off event in markets, as the S&P 500, Nasdaq-100 and Bitcoin fell 1.5%, 3.1%, and BTC fell below $100K.
Trending News
- Solana DEX, Jupiter, has acquired a majority stake in Moonshot, a self-custodial app where users can buy memecoins and where the $TRUMP token was initially launched.
- Japanese investment firm, Metaplanet, has announced plans to purchase 10,000 bitcoins in 2025 and 21,000 bitcoins before the end of 2026 via share issuance in a similar manner to MicroStrategy’s previous BTC funding methods.
Open Interest Consistent Despite Volatile Selloff
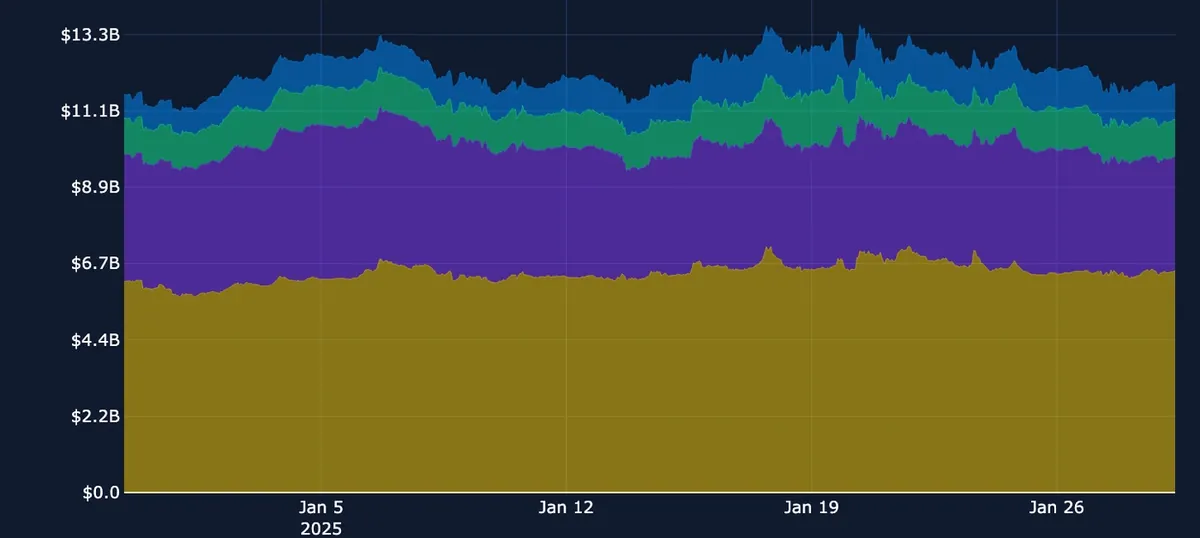
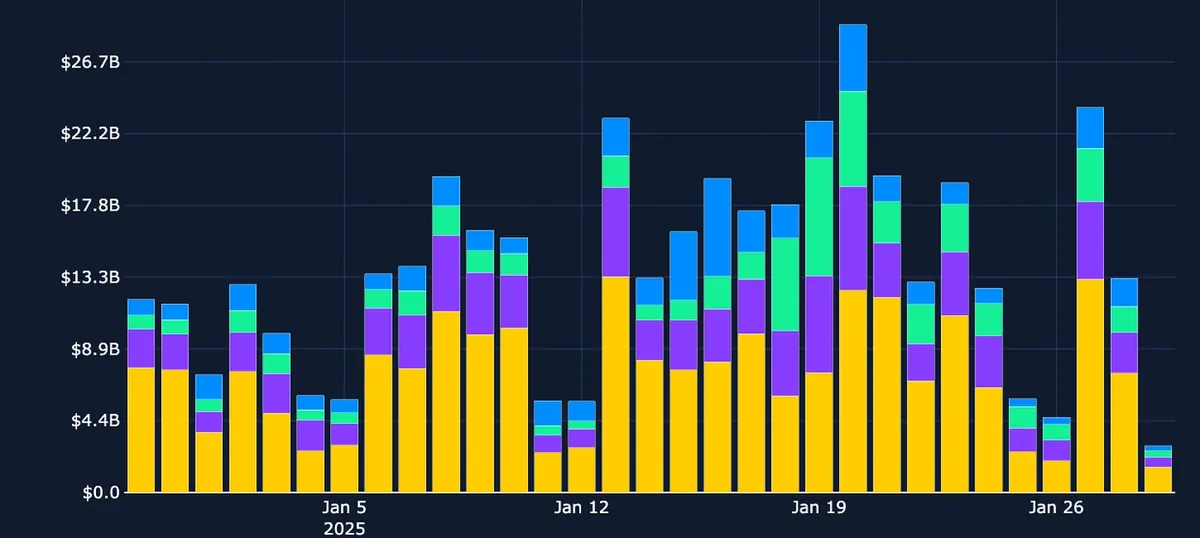
Monday’s spot sell-off inspired this week’s largest spike in perpetual swap trading activity, with a lower volume of trades booked in the following days than during last week. However, selloff in spot and the underwhelming recovery that followed haven’t yet shaken out any sizable level of open interest. Relatively low funding rates across these coins over the past month indicate that there wasn’t a significant proportion of over-leveraged long positions to be liquidated during the move after the shakeout in early December 2024 had not seen a significant proportion build back up – in fact, we have not yet seen a return to the exuberant bullishness exhibited then, despite recording new all-time high prices in BTC spot.
Bybit Perp Open Interest — Open interest remains focused on majors BTC and ETH.
Bybit Perp Trading Volumes — Trading activity is strongest near to volatile moves in spot prices, including Monday’s spot selloff.
Sell-Off Sees Funding Rates Flip
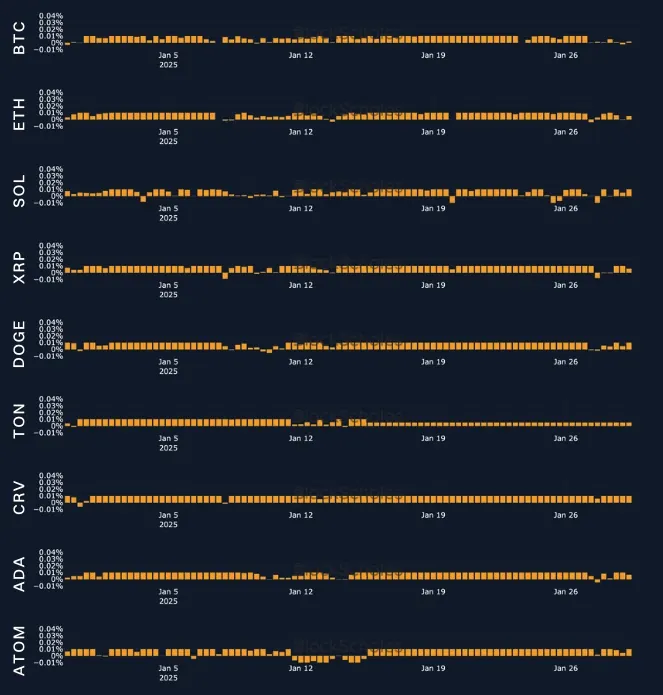
A weeklong period of positive funding rates across almost all perpetual swap markets was interrupted early this week by the global asset sell-off. In the early hours of Monday morning, funding rates in majors flipped either to 0 or negative from the positive rates they’d reported for much of the week that followed last Monday’s U.S. inauguration. However, the subsequent and underwhelming recovery in spot prices to lower highs has seen those funding rates recover somewhat, with majors BTC and ETH lagging slightly.
BTC Options
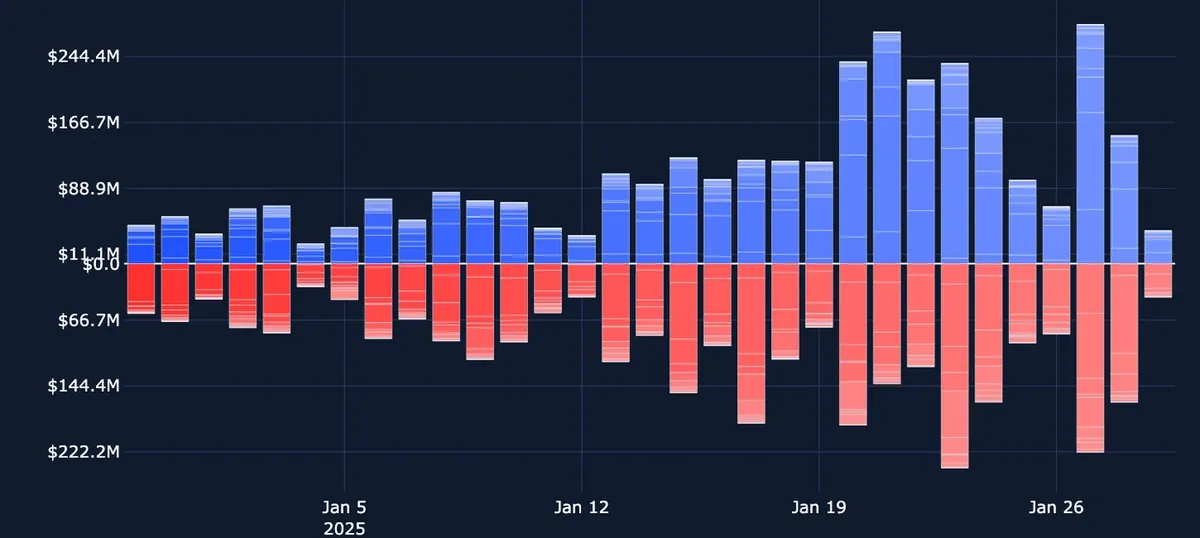
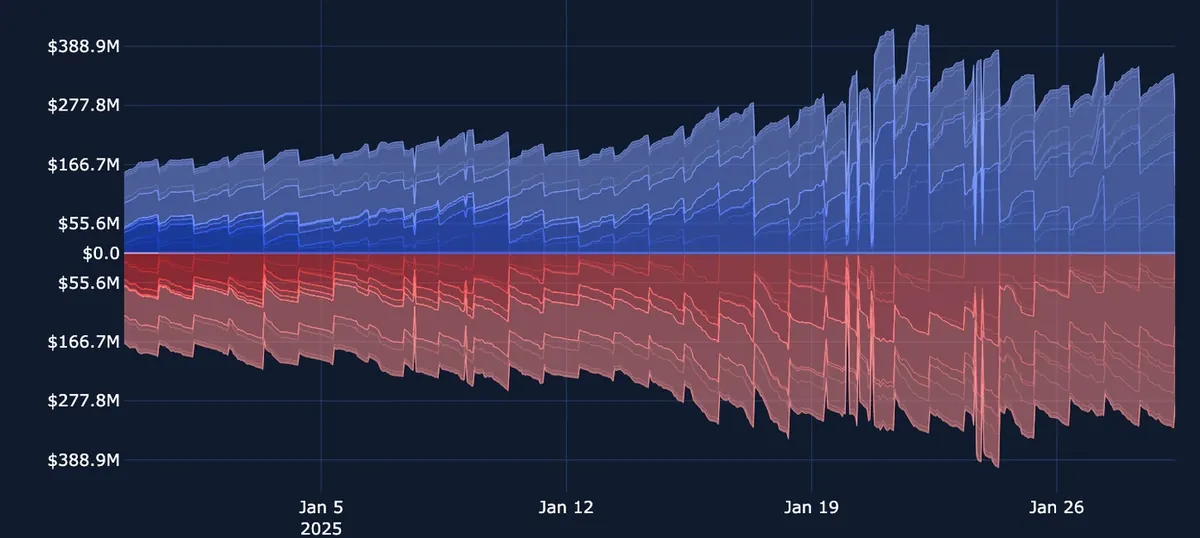
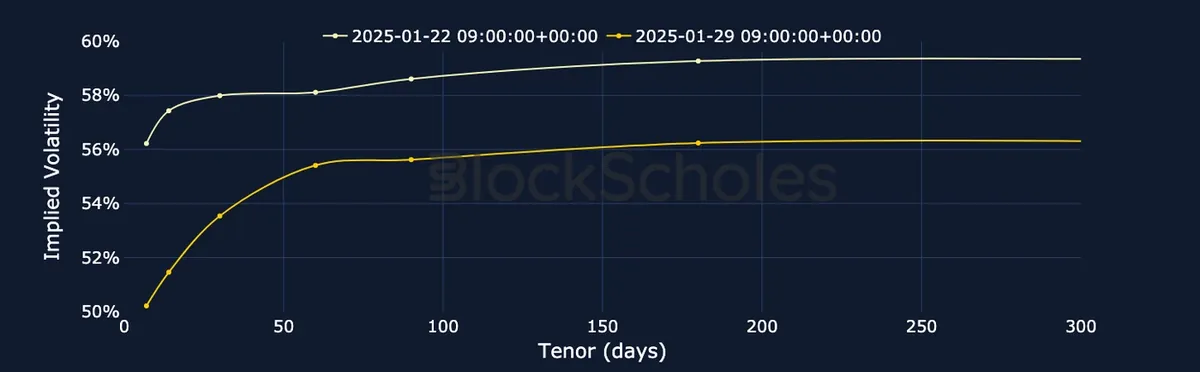
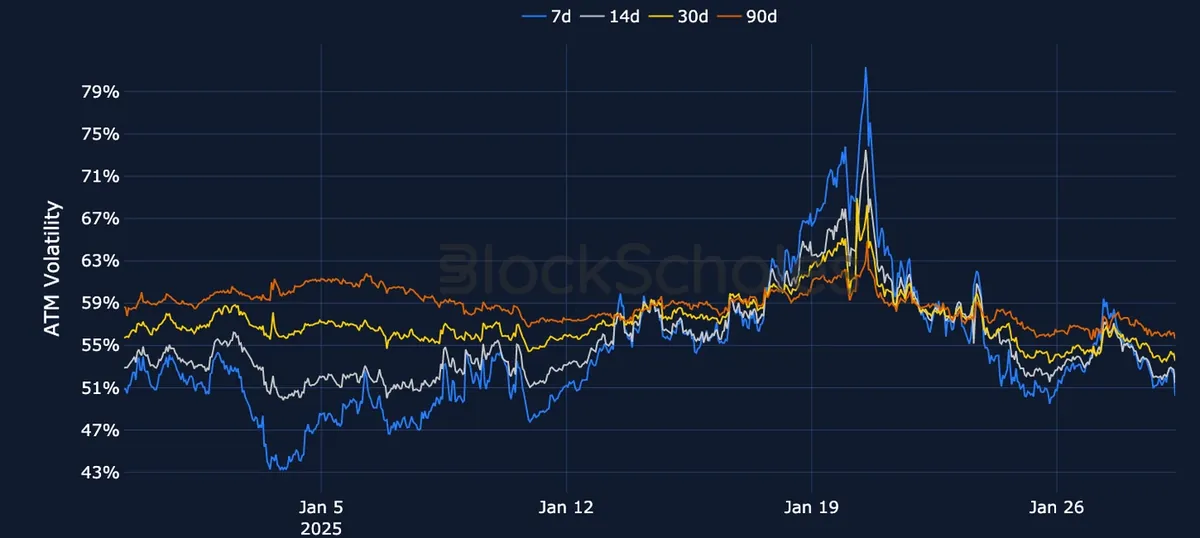
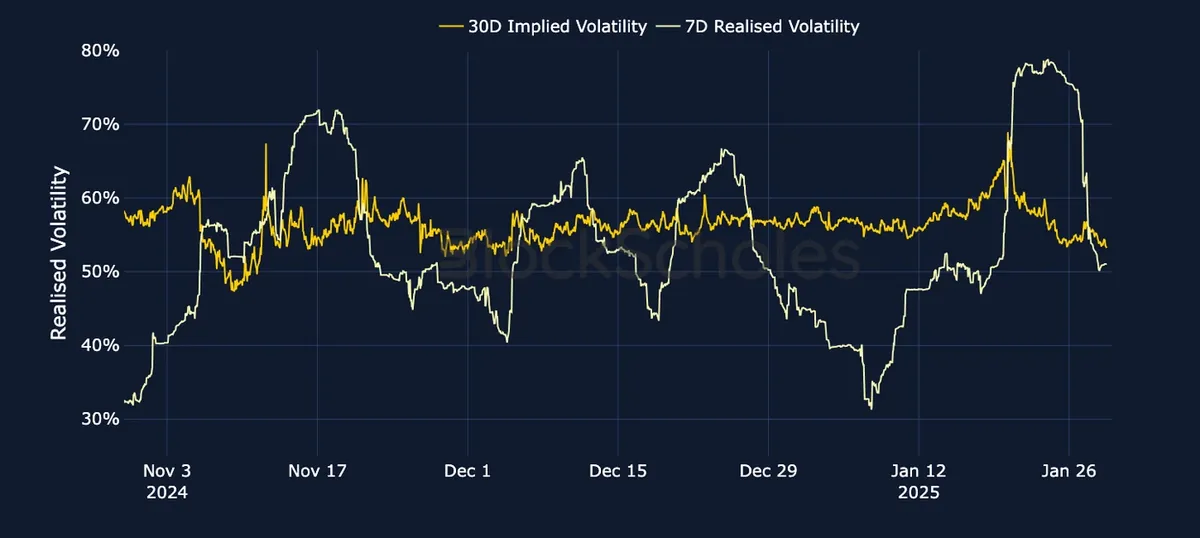
Options open interest data shows little change over the past week, aside from the expiration and reopening of short-dated optionality. This belies the largest single-day trading volumes in call options over the past month, with close to $250M in calls changing hands during the spot price sell-off. This may indicate that some of that trade volume in calls was in very short-dated expirations, which expired very soon after – which we see some evidence of in the chart of open interest – but need not necessarily directly result in a net change in the level of open interest. The increase in trade volume ultimately did little to raise volatility levels, as both realized and implied volatility have fallen over the past week. The resulting positioning has been split between short-tenor and longer-tenor volatility smiles. Short-tenor options are trading with lower volatility and a neutral skew, while longer-dated volatility smiles are trading with increased volatility expectations and a persistently bullish skew toward OTM calls — as they have for much of the post-election period.
BYBIT BTC OPTIONS VOLUMES
BYBIT BTC OPTIONS OPEN INTEREST
Volatility Expectations Were Disappointed
BYBIT BTC ATM TERM STRUCTURE — Front-end volatility is now trading at the same levels as in the week before the inauguration.
BYBIT BTC SVI ATM IMPLIED VOLATILITY — Volatility pricing continues to trend downward across the term structure, despite the early-week flattening.
BYBIT BTC IMPLIED AND REALIZED VOLATILITY — Despite the early-week sell-off, BTC’s realized volatility has fallen back below implied volatility levels at a 1-month tenor.
ETH Options
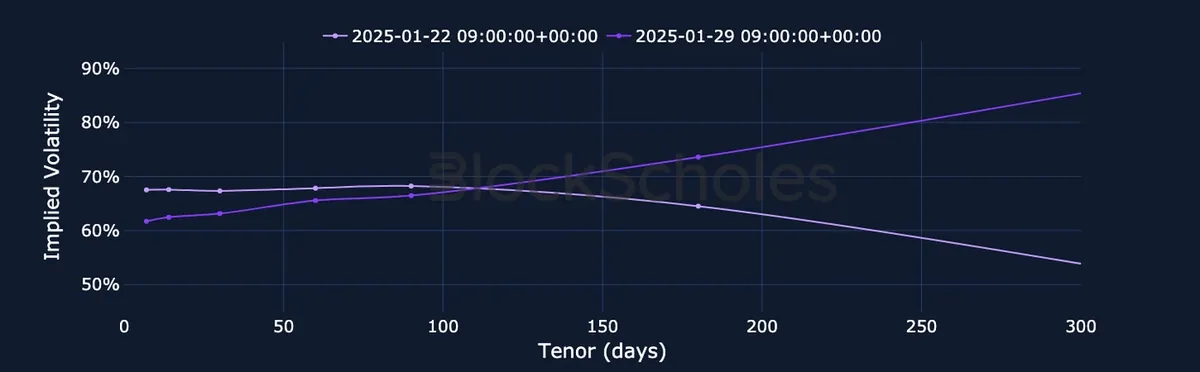
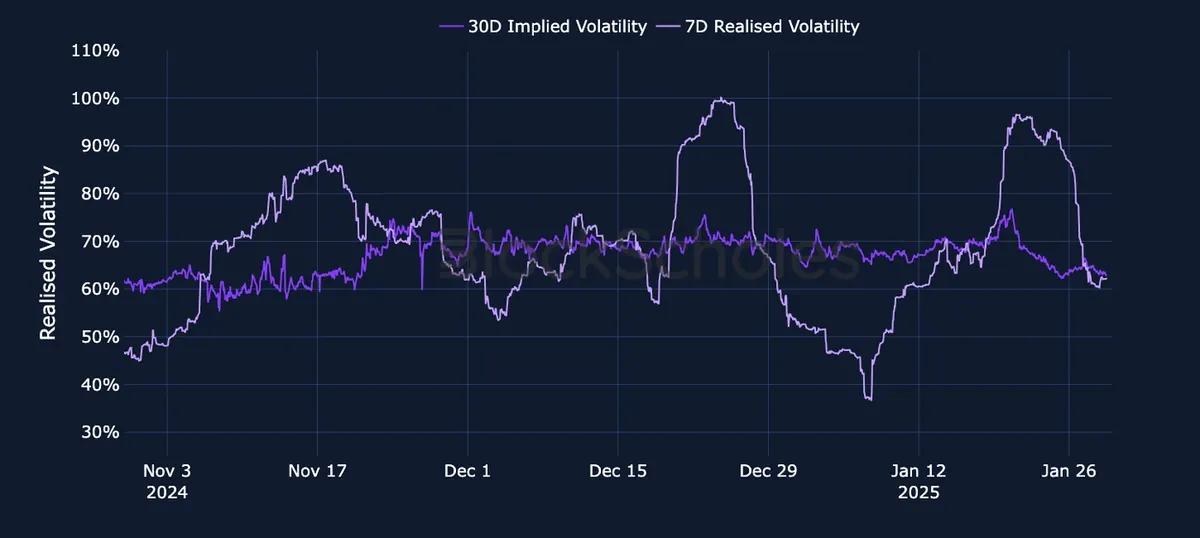
Trading volume in ETH options over the past week has been at its strongest levels within the past month. Whereas late December 2024 and early January 2025 were dominated by persistently stronger activity inputs, the latest data show a much more active calls market. However, open interest data remains decisively tilted toward calls. The spot sell-off in global markets at the beginning of the week saw short-tenor ETH volatility smiles briefly lose their skew toward calls, along with a miniature repeat of the inversion of the volatility term structure that we saw ahead of the inauguration last week. ETH’s subsequent spot recovery wasn’t as strong as BTC’s, and ETH options have retained their higher volatility levels.
BYBIT ETH OPTIONS VOLUMES
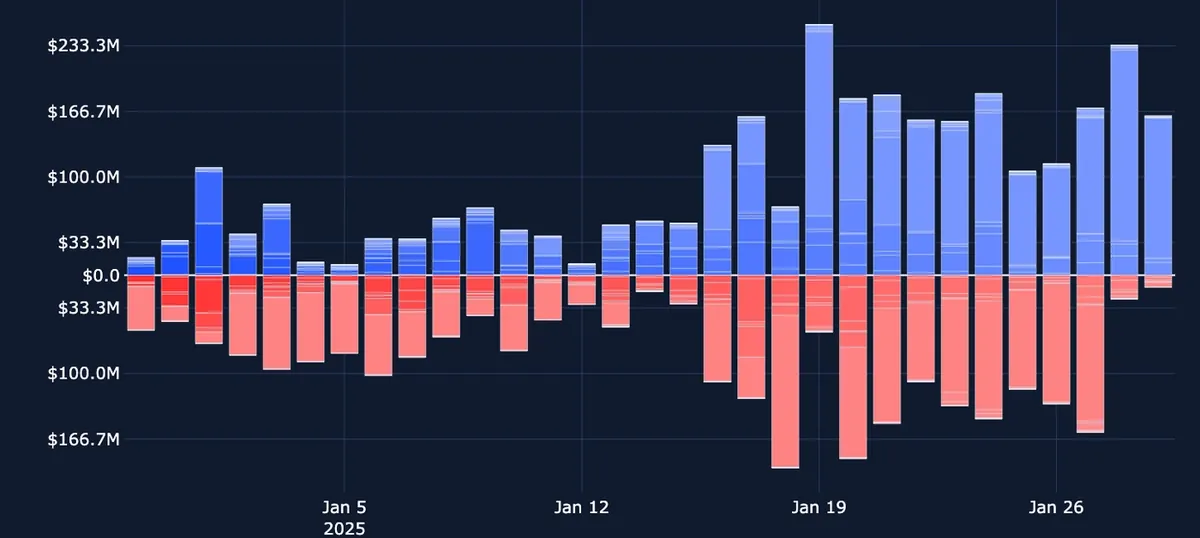
BYBIT ETH OPTIONS OPEN INTEREST
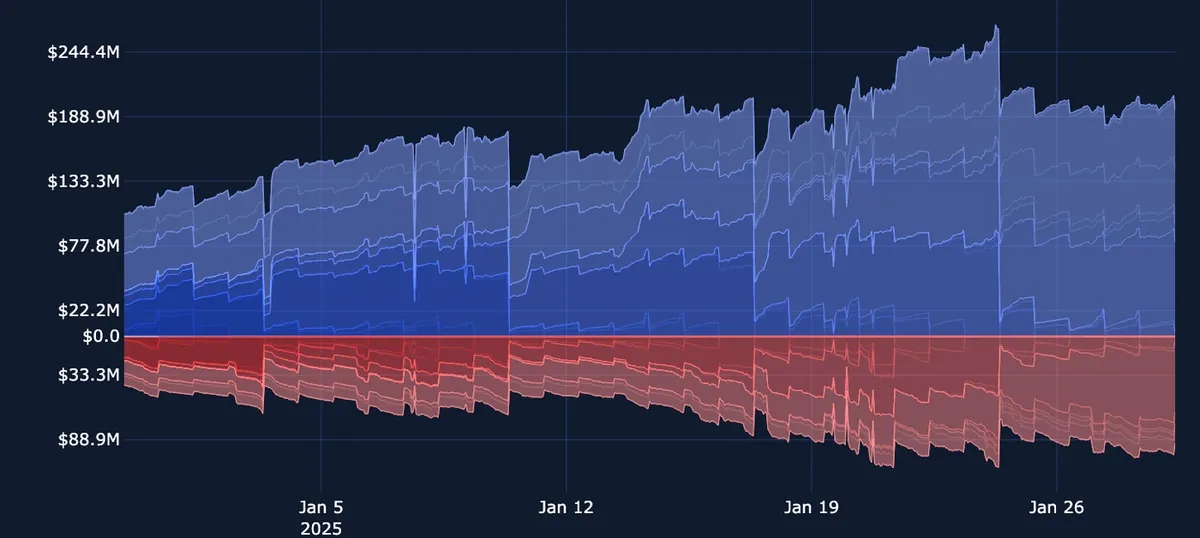
Another Inversion During Spot Movements
BYBIT ETH VOLATILITY TERM STRUCTURE — Longer-dated volatility has outperformed, currently trading at a premium to short-dated options.
BYBIT ETH SVI ATM IMPLIED VOLATILITY — BTC’s fall alongside major U.S. equity names midweek saw a miniature repeat of the inauguration volatility inversion.
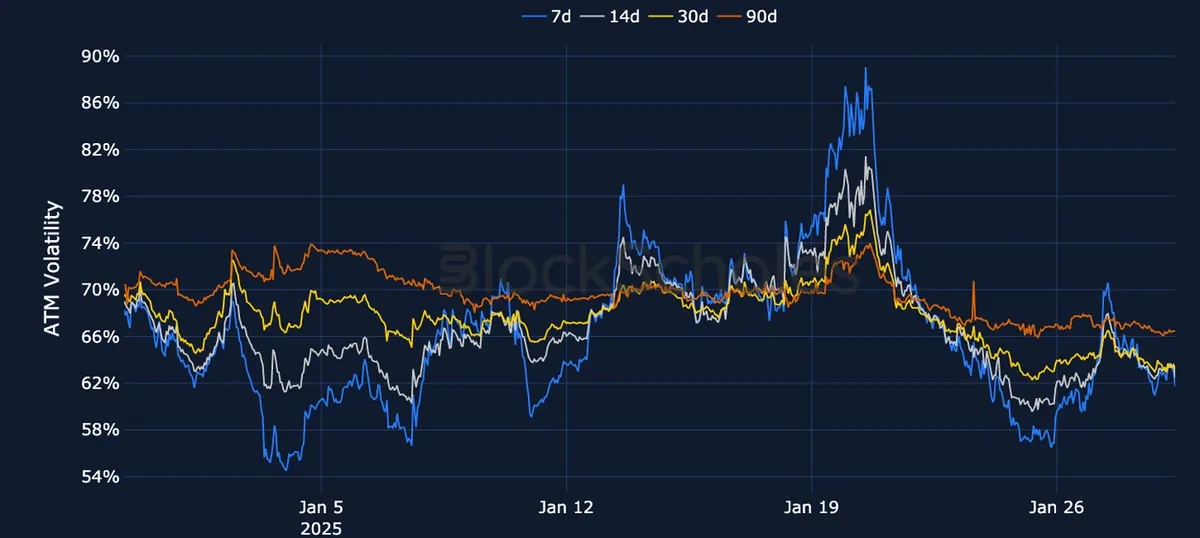
BYBIT ETH IMPLIED AND REALIZED VOLATILITY — Inauguration-inspired volatility was short-lived, as realized volatility once again fell.
SOL Options Positioning Unchanged
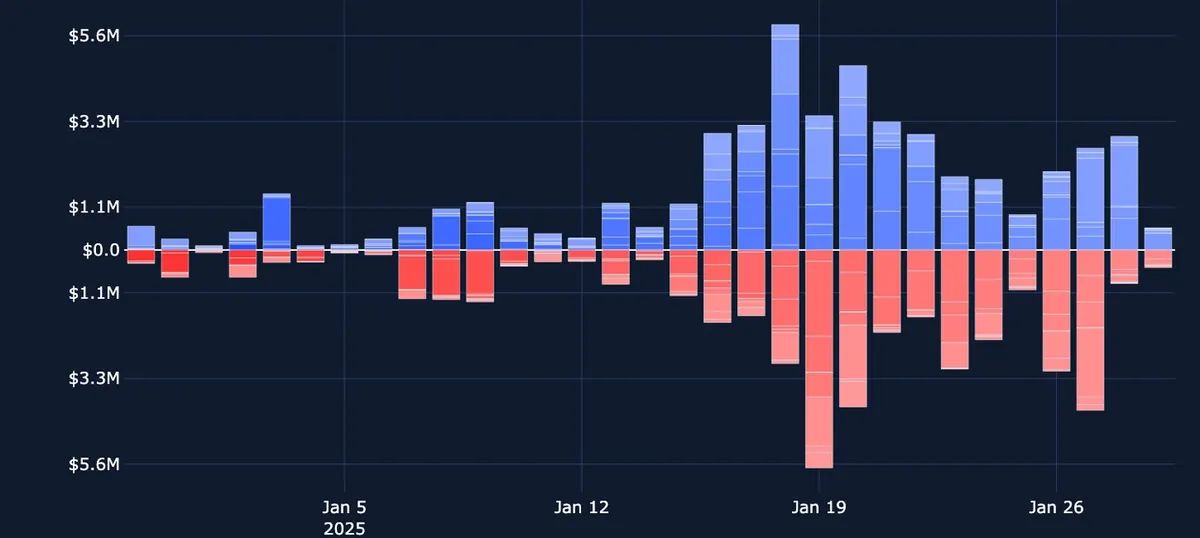
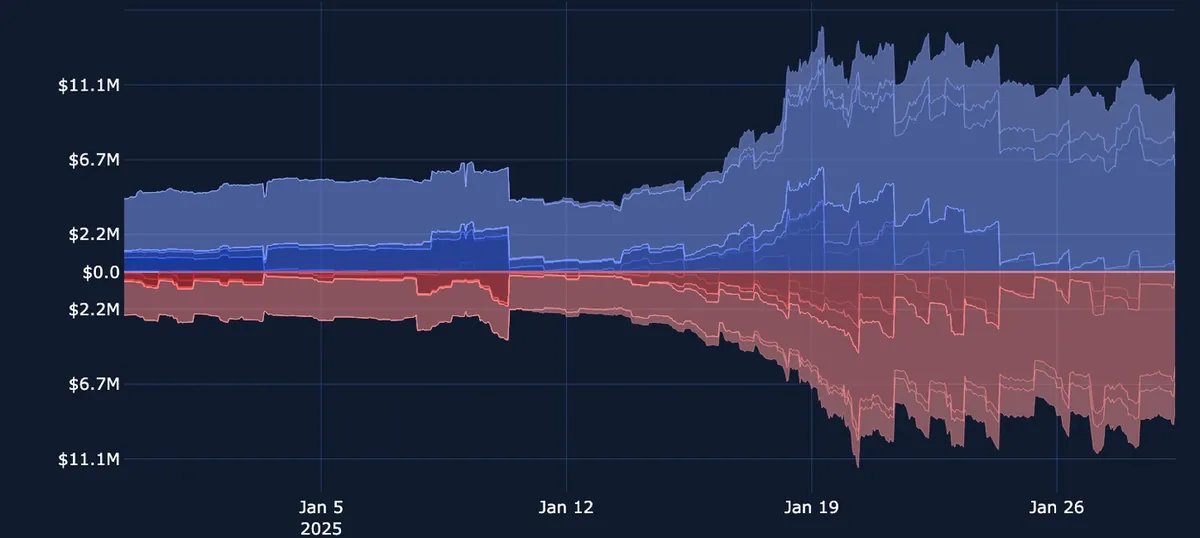
After the sharp rally in spot price that resulted from the launch of two presidential meme coins last week, Solana's spot price has pulled back alongside the broader crypto market. However, this hasn’t resulted in a drastic reversal of the positioning that we saw open during the rally. Open interest in puts and calls remains at its higher levels, and trading activity elevated above its pre-rally levels. The stable levels of put options that were opened during the move are most likely indicative of protective put buying intended to hedge profitable long positions in other instruments.
BYBIT SOL OPTIONS VOLUMES
BYBIT SOL OPTIONS OPEN INTEREST
Bullish Skew at Longer Tenors
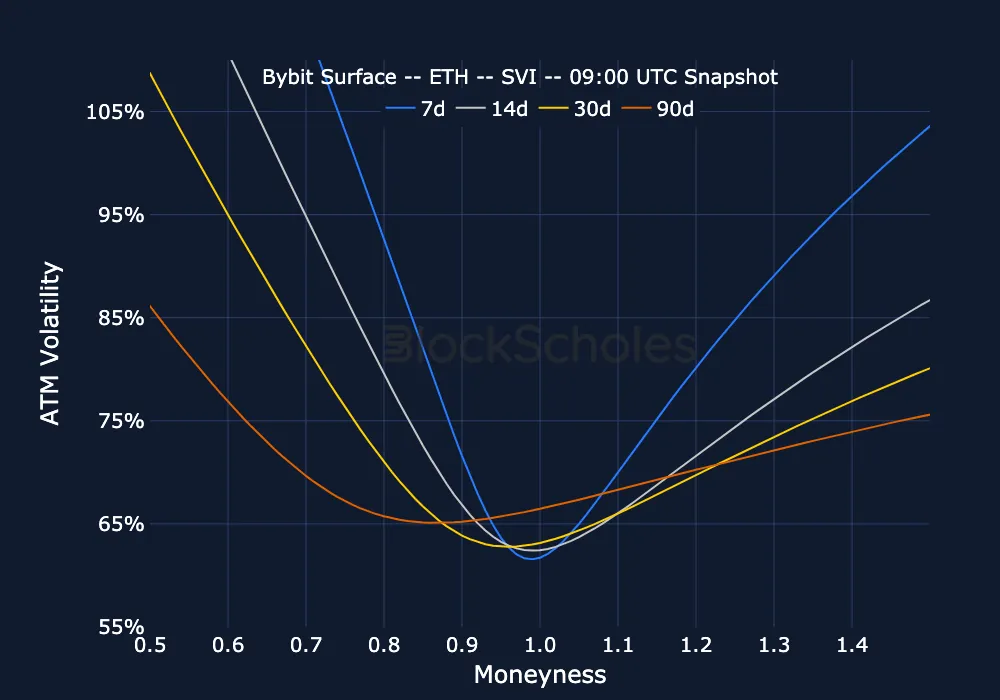
One week on from an inaugural speech that was disappointingly bereft of new crypto policy, options markets continue to price for a more bullish outlook over a longer horizon, compared to expectations in the short term. BTC’s 3-month tenor volatility smiles have traded with a much stronger skew towards calls than shorter-tenor volatility smiles, as have ETH’s. This is a persistent positioning that we’ve seen for much of the past month, and it continues a divergence between long and short investment horizons. Shorter tenors, however, have moved closer to neutral levels following the early-week sell-off in spot price, but haven’t flipped toward puts as they did earlier this month.
BYBIT BTC 25-delta Call-Put Skew
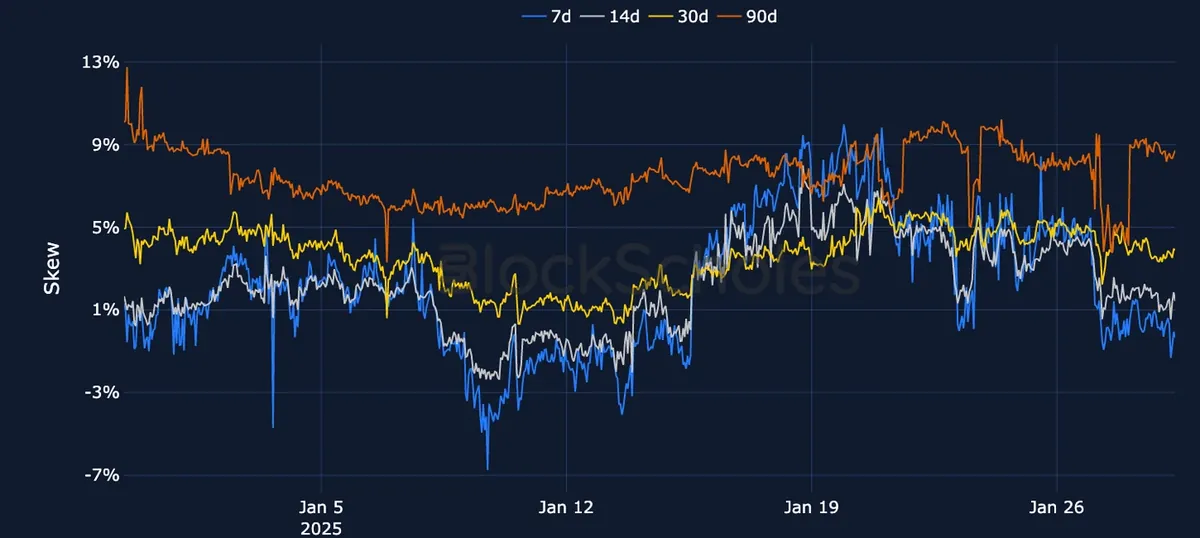
BYBIT ETH 25-delta Call-Put Skew
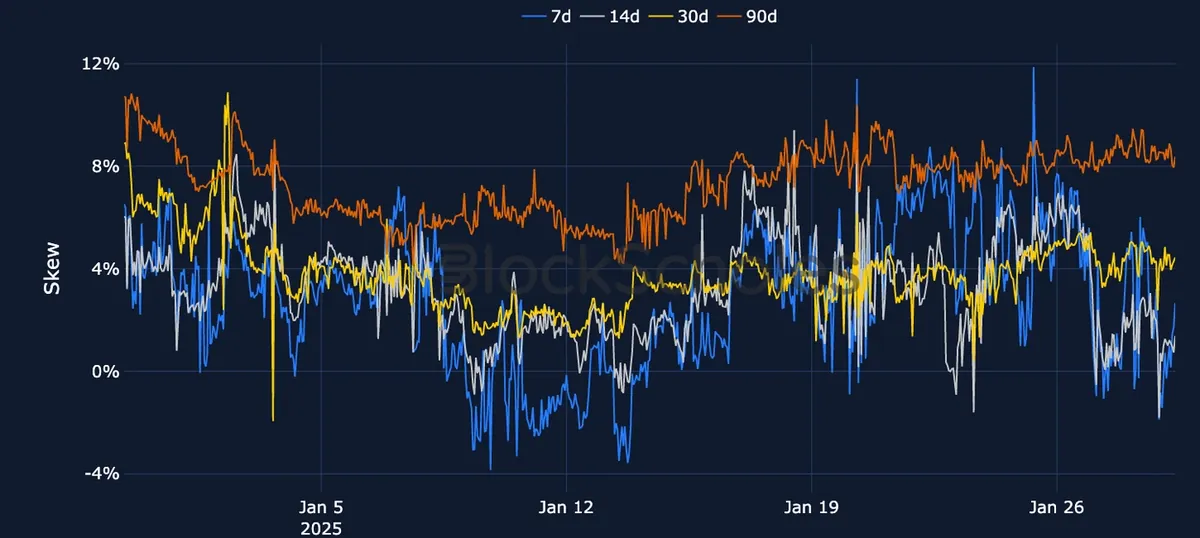
Volatility by Exchange
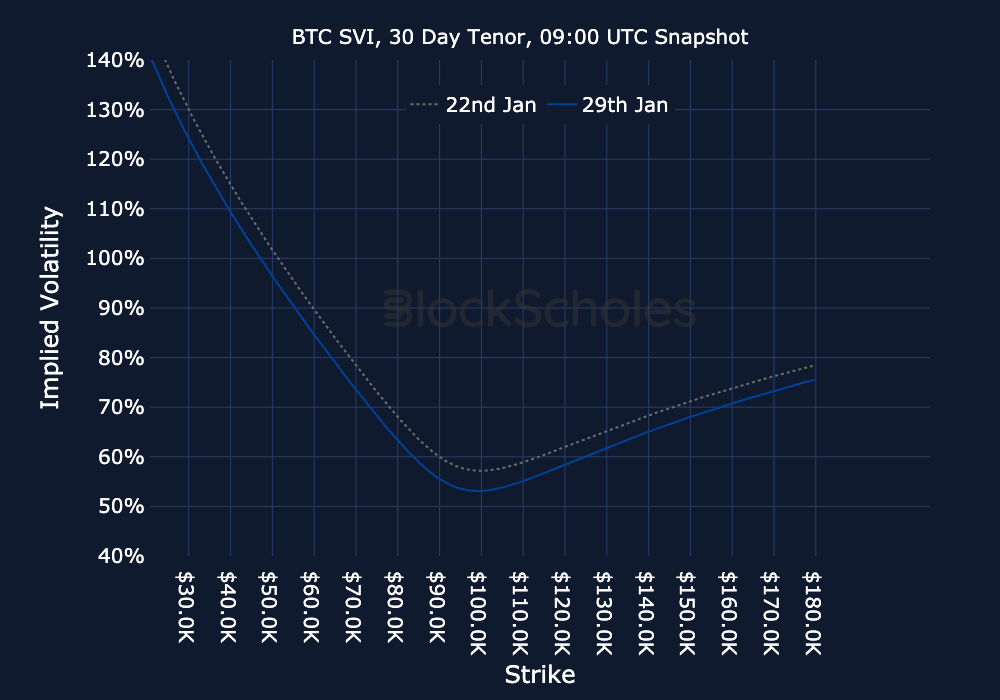
BTC, 1-MONTH TENOR, SVI CALIBRATION
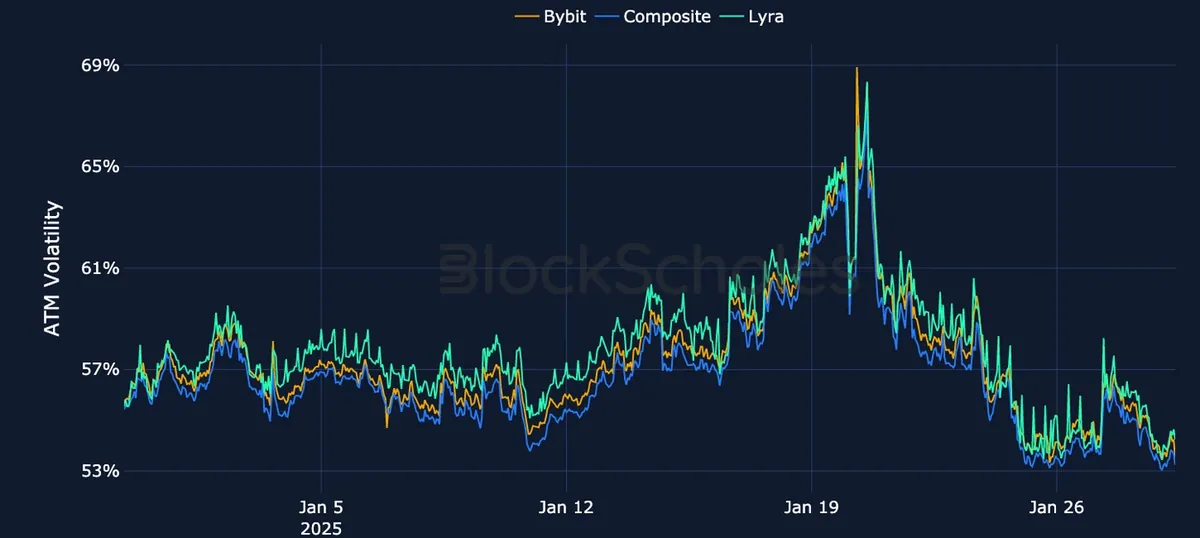
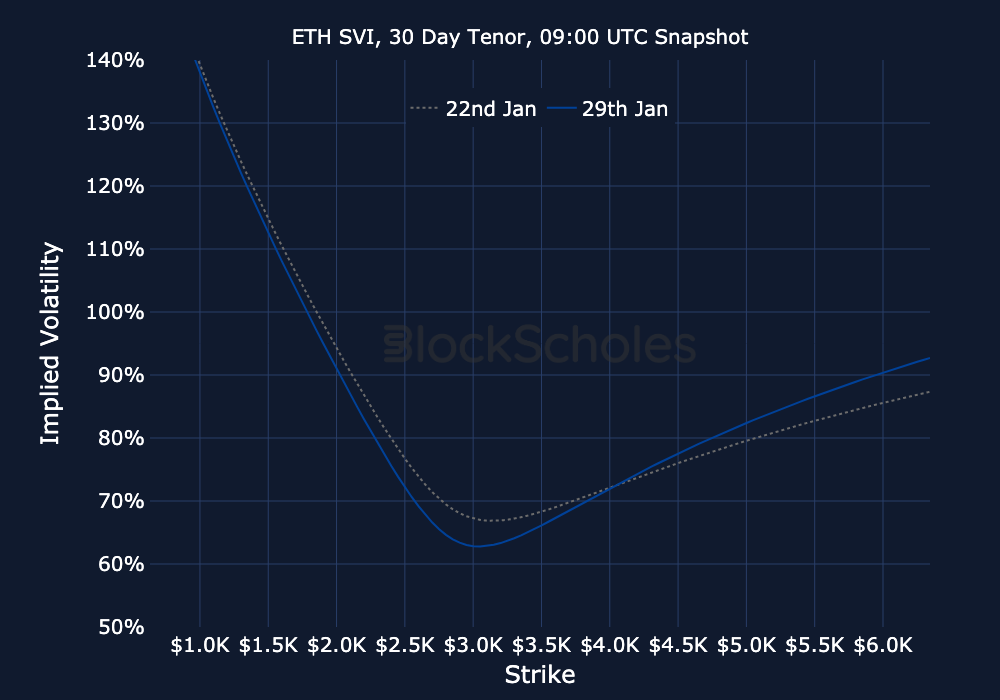
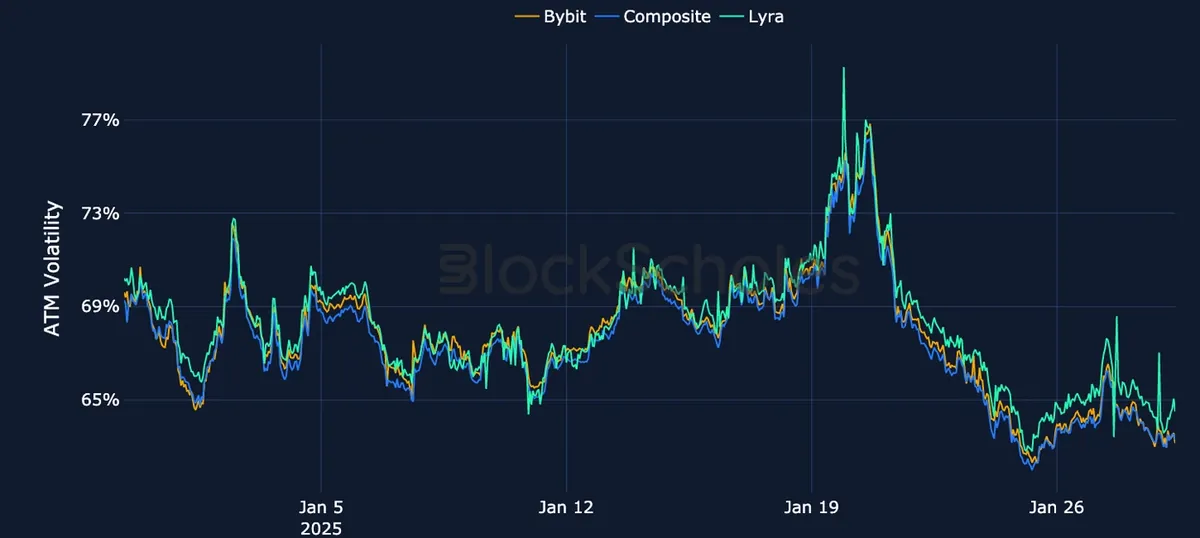
ETH, 1-MONTH TENOR, SVI CALIBRATION
Bybit Volatility Surfaces
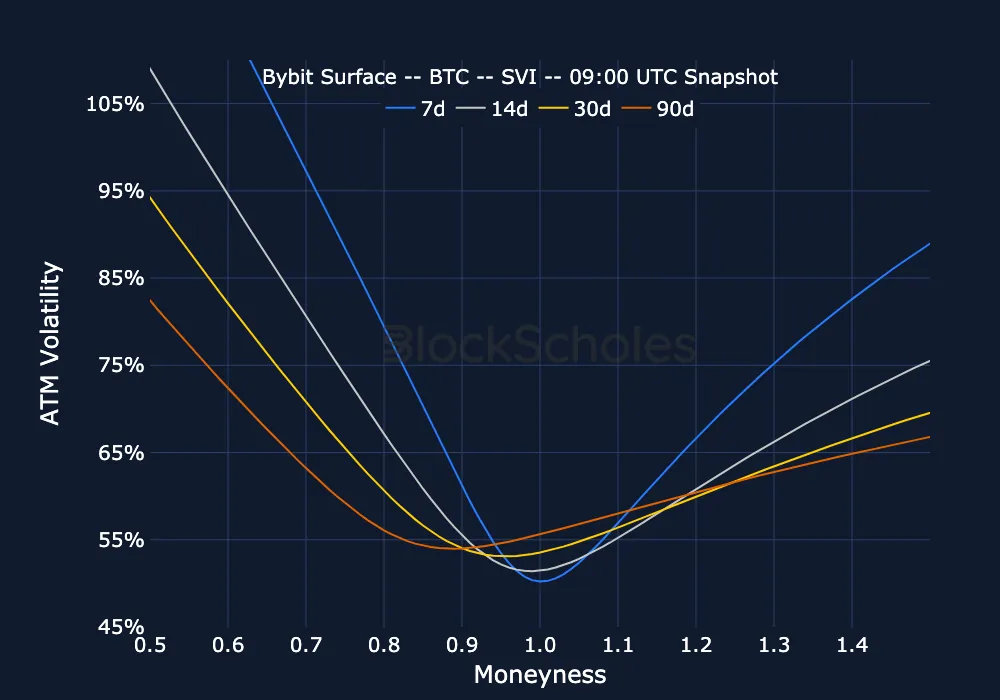
Constant Maturity Smiles