By Andrew Melville · 04 Apr 2025 · 8 MIN READ
Block Scholes x Bybit Crypto Derivatives April 6 2025
As markets finally approach the day of tariffs that US president Donald Trump has dubbed America’s “Liberation Day,” crypto continues its macro-sensitive spot volatility. That volatility has seen BTC drop from its $88K local high to $82K, as President Trump showed signs that his reciprocal tariffs would not spare any country, though notably, the tariffs do not apply to Russia or North Korea. Implied volatility has exploded and since eased. Other derivatives markets metrics show BTC and ETH volatility smile skews remain significantly skewed towards puts, though slightly higher than the recent levels reached, which were last seen in March 2023.
Key insights
As markets finally approach the day of tariffs that US president Donald Trump has dubbed America’s “Liberation Day,” crypto continues its macro-sensitive spot volatility. That volatility has seen BTC drop from its $88K local high to $82K, as President Trump showed signs that his reciprocal tariffs would not spare any country, though notably, the tariffs do not apply to Russia or North Korea. Implied volatility has exploded and since eased. Other derivatives markets metrics show BTC and ETH volatility smile skews remain significantly skewed towards puts, though slightly higher than the recent levels reached, which were last seen in March 2023.
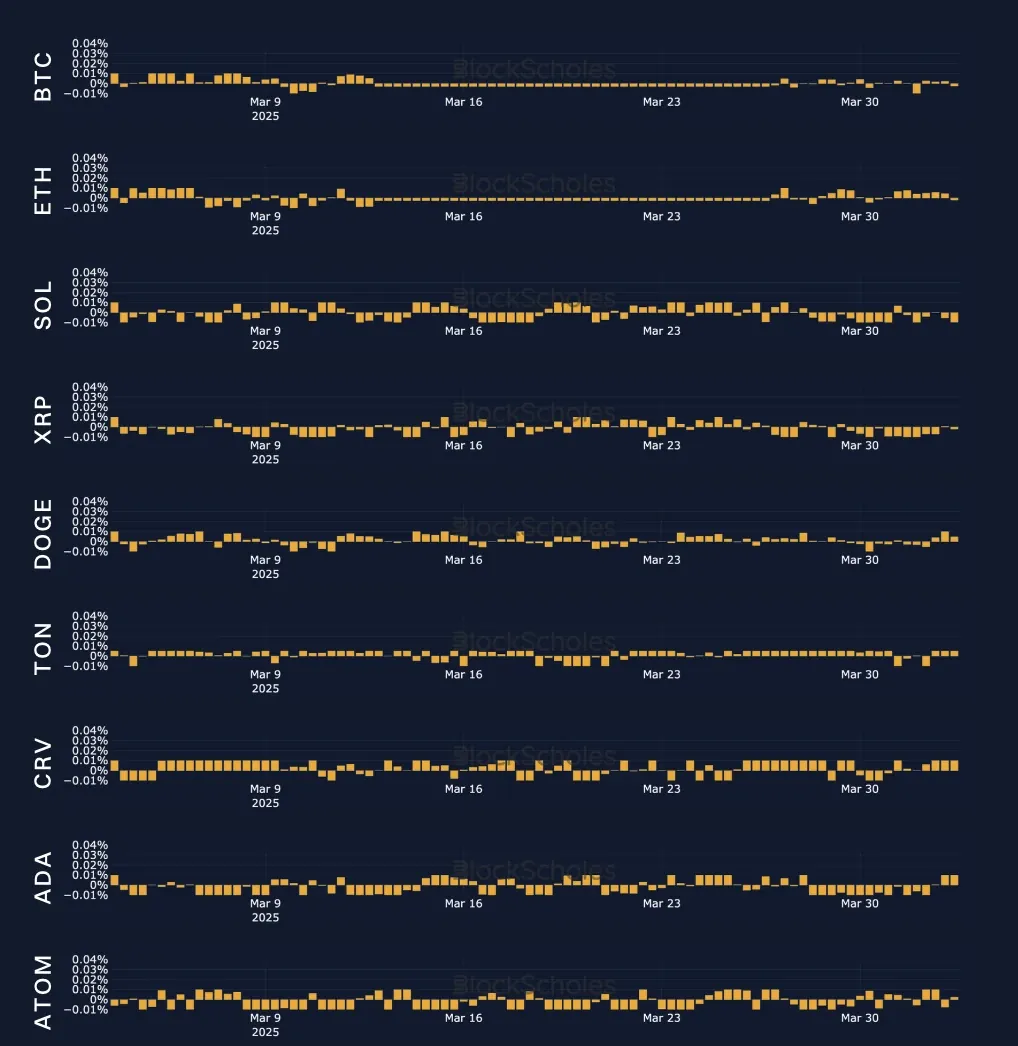
Perpetuals: Funding rates for BTC have been mostly neutral, an indication of an unwillingness to pay a premium to express a meaningful position in both directions, while funding rates for ETH have been more consistently positive.
Options: Implied volatility levels have dropped from their explosive highs earlier in the week, with BTC’s term structure now flat, while ETH’s remains inverted.
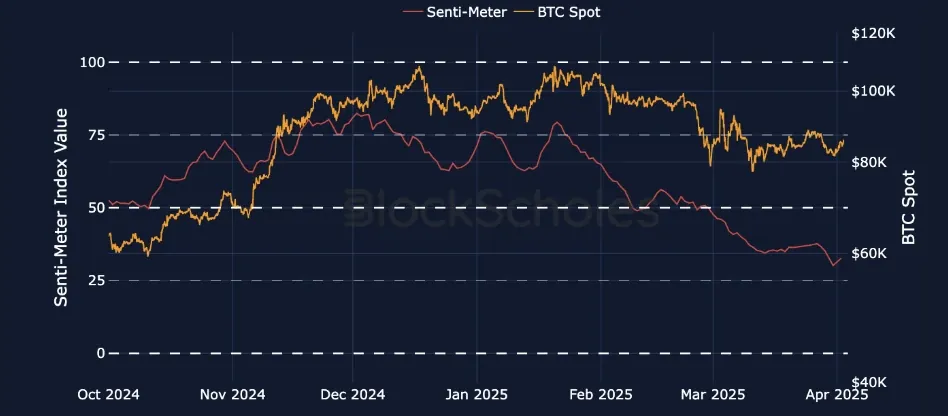
Block Scholes BTC Senti-Meter Index
Block Scholes ETH Senti-Meter Index
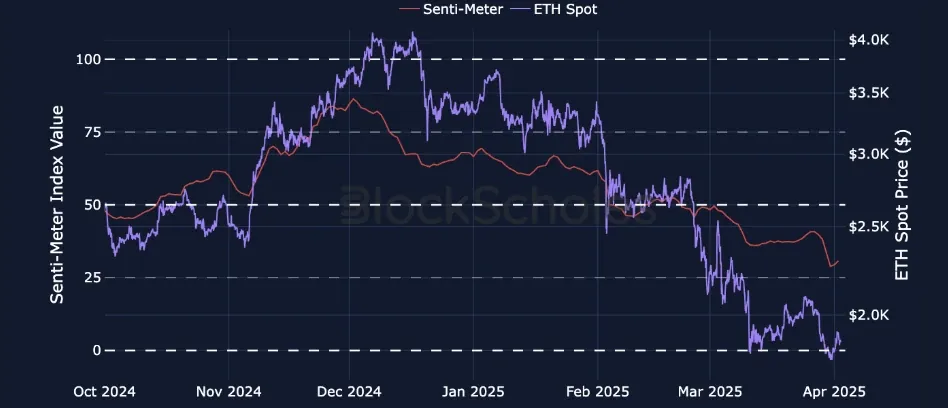
Block Scholes’s Senti-Meter Index aggregates the funding rate, future-implied yield and volatility smile skew into a single expression of sentiment in derivatives markets. See more in the methodology article here.
Macro, tech & regs
Macro calendar & recent events
- S&P Global Manufacturing PMI for US — Apr 1, 2025 — The S&P’s Manufacturing PMI reading fell to 50.2 in March, from 52.7 in February, just above the value indicating an expansion. According to the report, “tariffs were the most cited cause of factory input costs rising in March.”
- Euro area inflation flash estimate — Apr 1, 2025 — Headline inflation is expected to fall from 2.3% in February to 2.2% in March, according to Eurostat’s flash estimate for March.
- US JOLTS — Apr 1, 2025 — The JOLTS report showed the number of job openings in the US for February fell to 7.568M against an expected 7.66M. This was lower than the January figure, which was revised upward by 22,000 jobs to 7.762M.
- Japan household spending — Apr 4, 2025 — Household spending in Japan is expected to increase 0.7% over the month from February to March, following a 4.5% contraction in the previous month.
- US nonfarm payrolls — Apr 4, 2025 — The most important labor market report, the NFP report, showed nonfarm payroll employment increased by 228K, far more than the 138K expected.
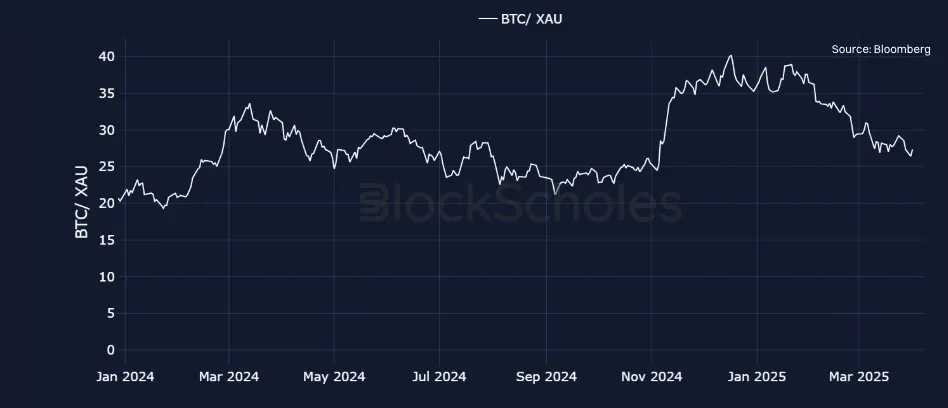
Gold bullion & BTC — Since the US election, prices for BTC and gold have moved in opposite directions. After initially rallying, BTC is now down over 20% from its January all-time high, while gold has rallied past $3,000/oz.
Trending news
- Strategy recently purchased 22,048 bitcoins for a total cost of $1.92B, bringing their total holdings to 528,185 BTC at an average price of $67,458. This is their sixth-largest BTC purchase to date.
- Stablecoin issuer Circle has filed for an IPO in the US, targeting a listing on the NYSE under the ticker CRCL. The USDC issuer is reportedly aiming for a valuation of up to $5B.
Open interest remains firm
Key insights
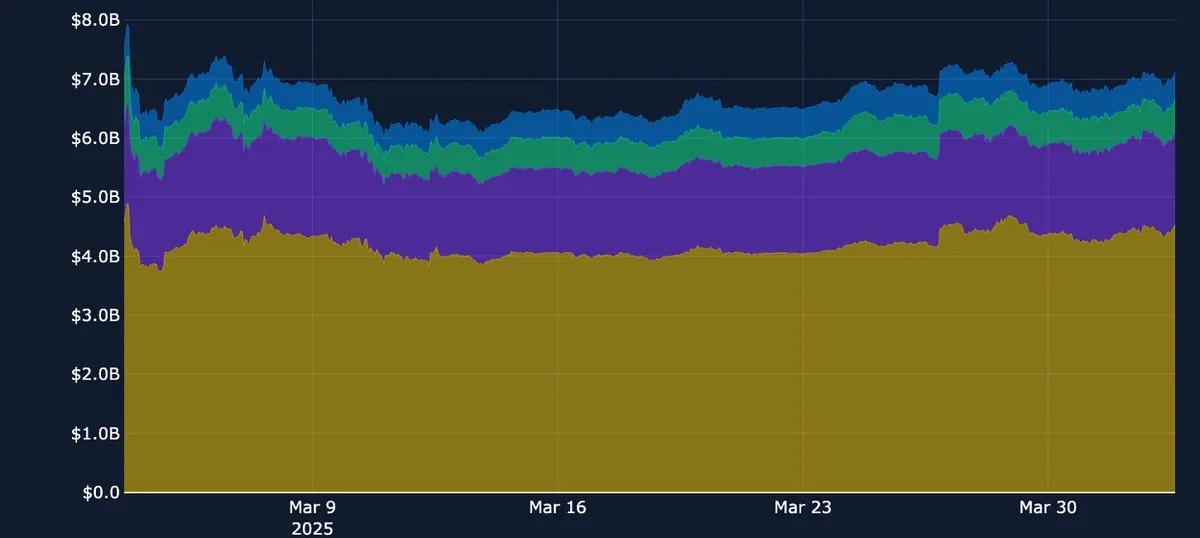
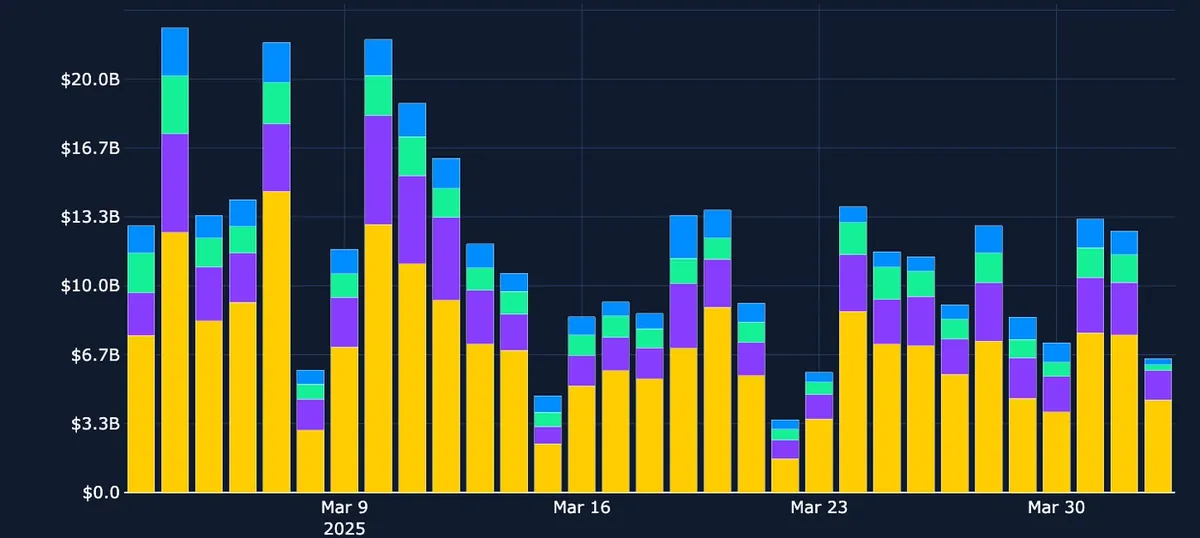
The slight spike in open interest that followed BTC’s reclaiming of $88K last week has, for the most part, held up this week. Perp OI hasn’t significantly fallen, despite BTC dropping to $82K on Monday morning as markets approached the week of the much anticipated American “Liberation Day” of tariffs. The risk-off sentiment that has characterized many of the weeks before it continues and, with it, BTC continues to dominate the open interest landscape. As usual, trade volumes are exhibiting quieter weekend activity but have also held up since Monday, with $13B continuing to act as the apparent ceiling of total trade volumes since mid-March 2025.
Bybit Perp Open Interest — The modest pickup in open interest following BTC’s brief recovery last week has held up through the early parts of this week.
Bybit Perp Trading Volumes — As BTC’s spot price has ranged from $82–88K, trading volumes have remained lower than at the start of the month.
Funding rate sentiment less clear
BTC funding rates have barely made any meaningful upside moves this week, with traders seemingly unwilling to pay a premium for long exposure. Similarly, short positions aren’t prepared to rule out an upside move. This may be a reflection of the market deciphering whether Trump’s “Liberation Day” reciprocal tariffs may indeed end up being less protectionist and aggressive than expected. ETH funding rates, on the other hand, have been more consistently positive — a sharp contrast to the negative rates seen in SOL perpetuals. Other altcoin funding rates continue to vary from positive to negative, as we saw last week, without any meaningful directional sentiment, despite their spot prices moving up slightly over the week.
BTC options
Key insights
As crypto asset spot prices have continued to move with a high correlation to macro-sensitive assets, the start of the week brought another explosion in short-tenor implied volatility for both BTC and ETH. The sell-off from last week continued into this week as Trump stated his reciprocal tariffs would “start with all countries” (although they clearly did not).
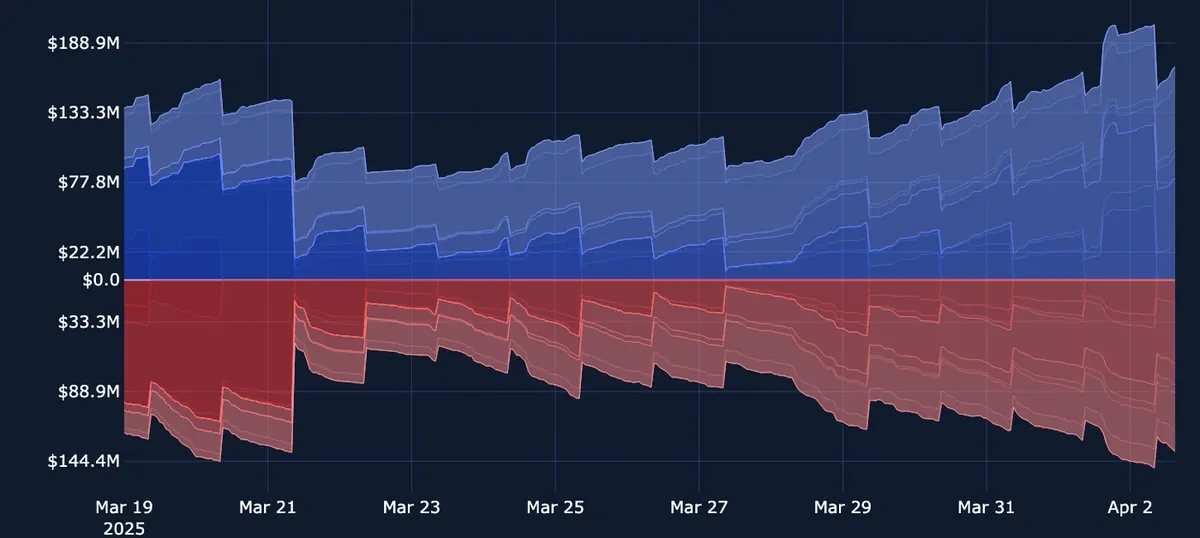
However, BTC’s front-end volatility quickly fell back below longer-end maturities. With it, short-dated volatility smiles briefly held a level of skew toward OTM puts that was last seen during the US banking crisis in March 2023. Contracts that expired at the end of March appear to have been reopened, with calls still dominating the majority of positions.
BYBIT BTC OPTIONS VOLUMES
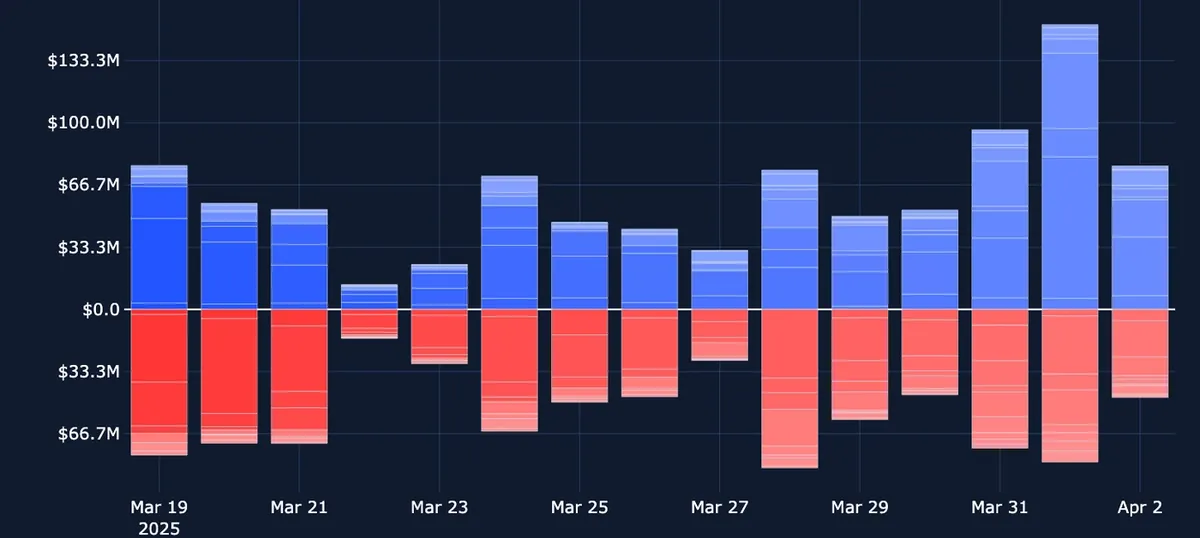
BYBIT BTC OPTIONS OPEN INTEREST
BTC volatility is back on the rise
BYBIT BTC ATM TERM STRUCTURE — After momentarily inverting at the start of the week, BTC’s term structure is now flat.
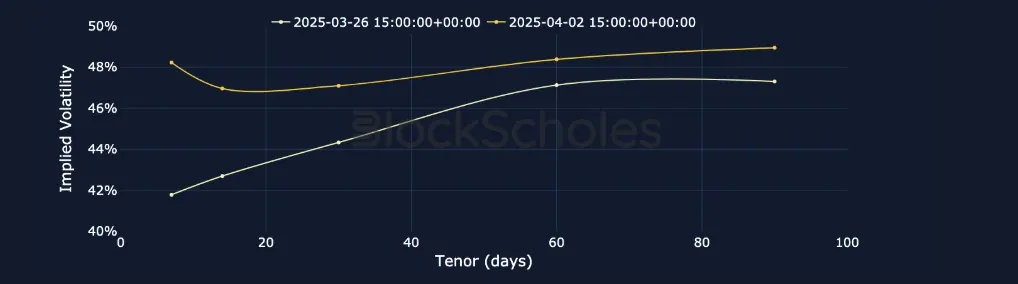
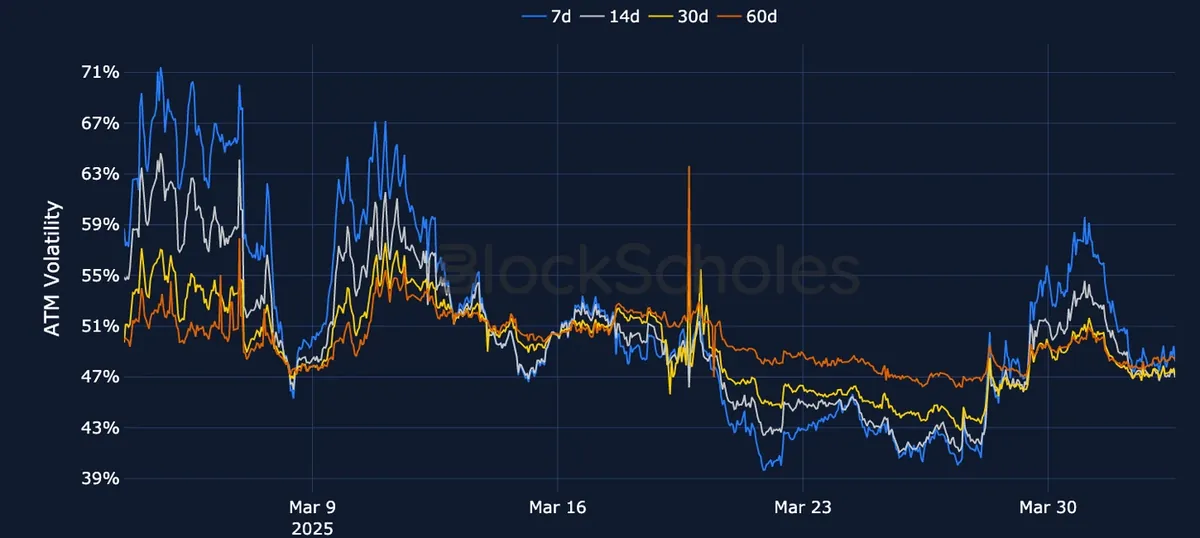
BYBIT BTC SVI ATM IMPLIED VOLATILITY — Implied volatility levels have exploded, with short-dated volatility smiles holding their strongest skew toward OTM puts since the US banking crisis in March 2023.
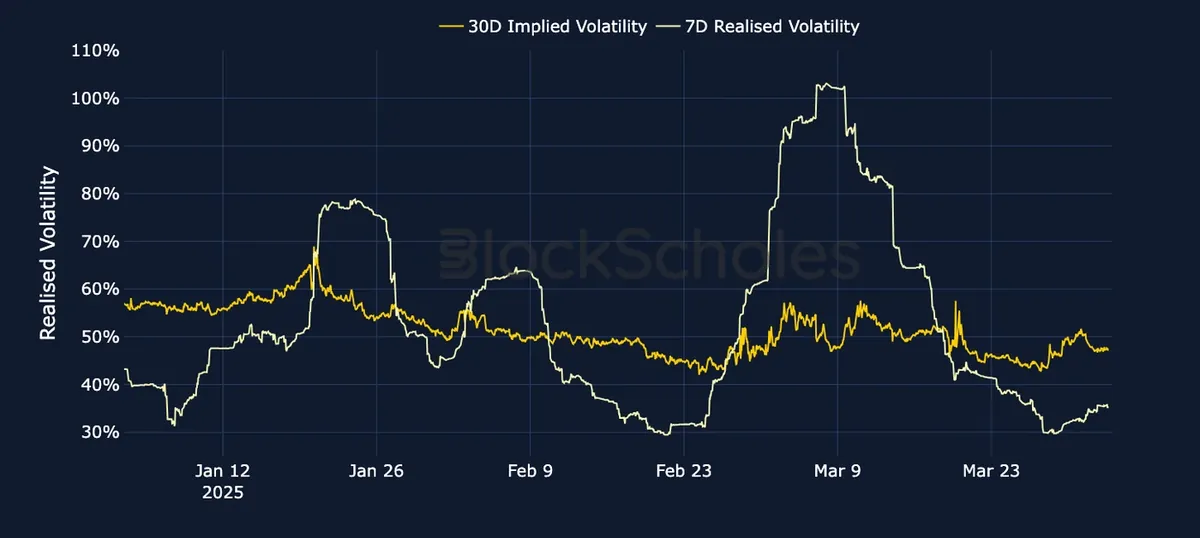
BYBIT BTC IMPLIED AND REALIZED VOLATILITY — Realized volatility spiked once more at the end of March, and is now trading just over 10 points lower than implied volatility.
ETH options
Key insights
USDT-denominated ETH options volumes have trended upward relative to last week. Short-tenor implied volatility levels exploded upwards once more at the start of the week alongside volatile moves in spot before quickly tempering back down. ETH has since maintained its term structure inversion, whereas BTC quickly flattened. Calls are only slightly dominating open interest, though demand for put options indicate that traders aren’t willing to bet that the worst is over for ETH just yet — despite news that the network successfully tested its Pectra upgrade on all testnets, with April 30 set as a provisional Mainnet launch date.
BYBIT ETH OPTIONS VOLUMES
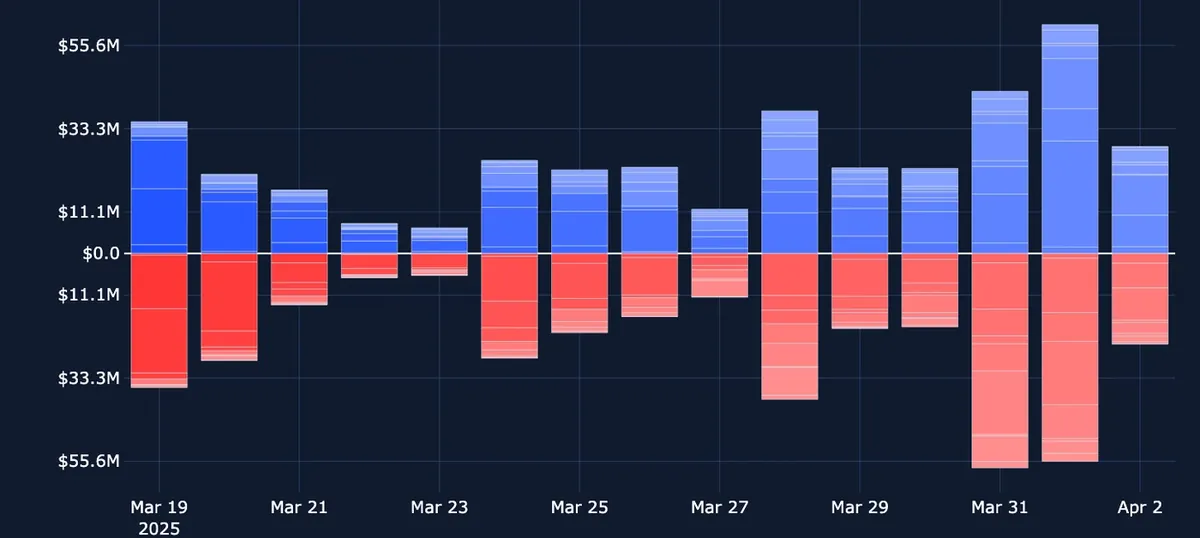
BYBIT ETH OPTIONS OPEN INTEREST
Continued spot volatility re-inverts the term structure
BYBIT ETH VOLATILITY TERM STRUCTURE — ETH’s term structure is distinctly inverted, with front-end volumes 10 points higher than at last week’s snapshot.
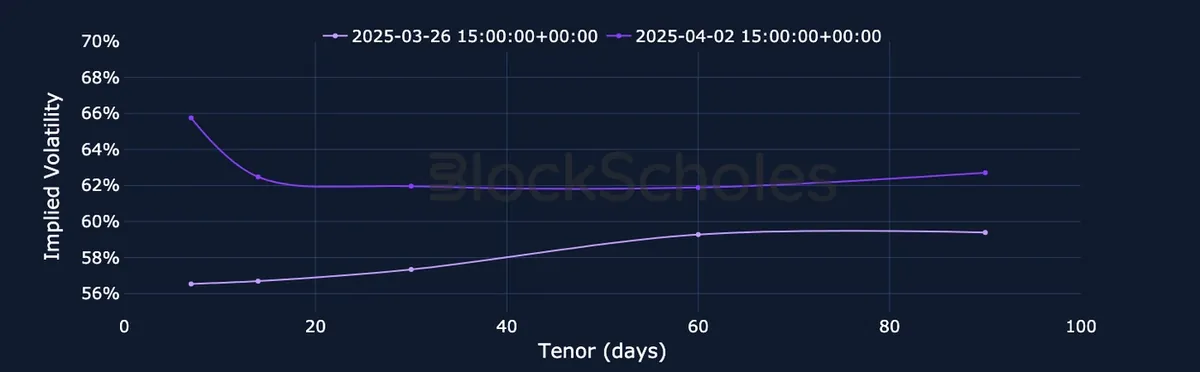
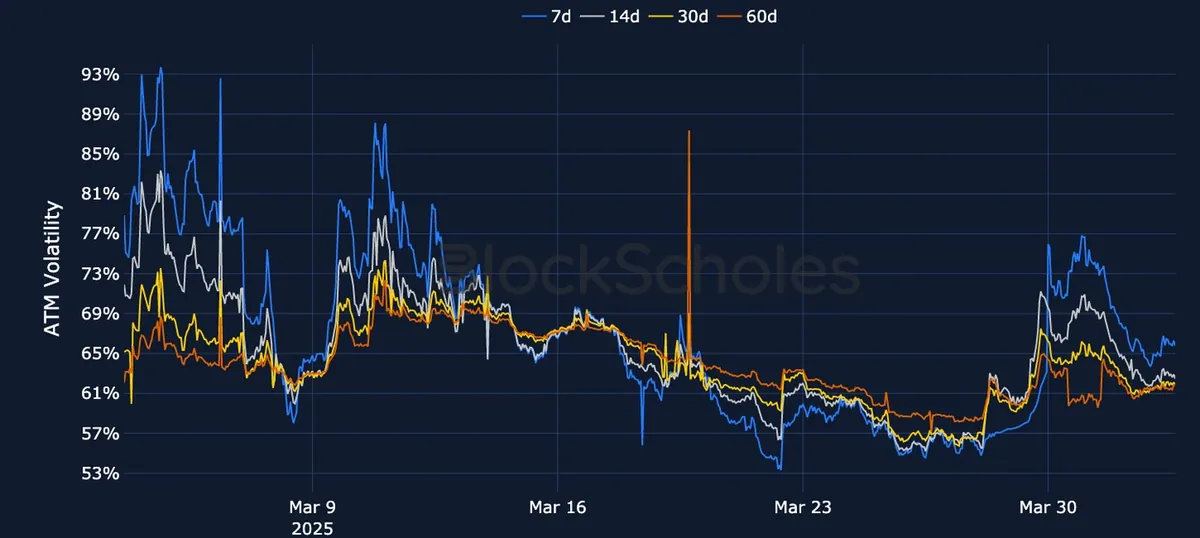
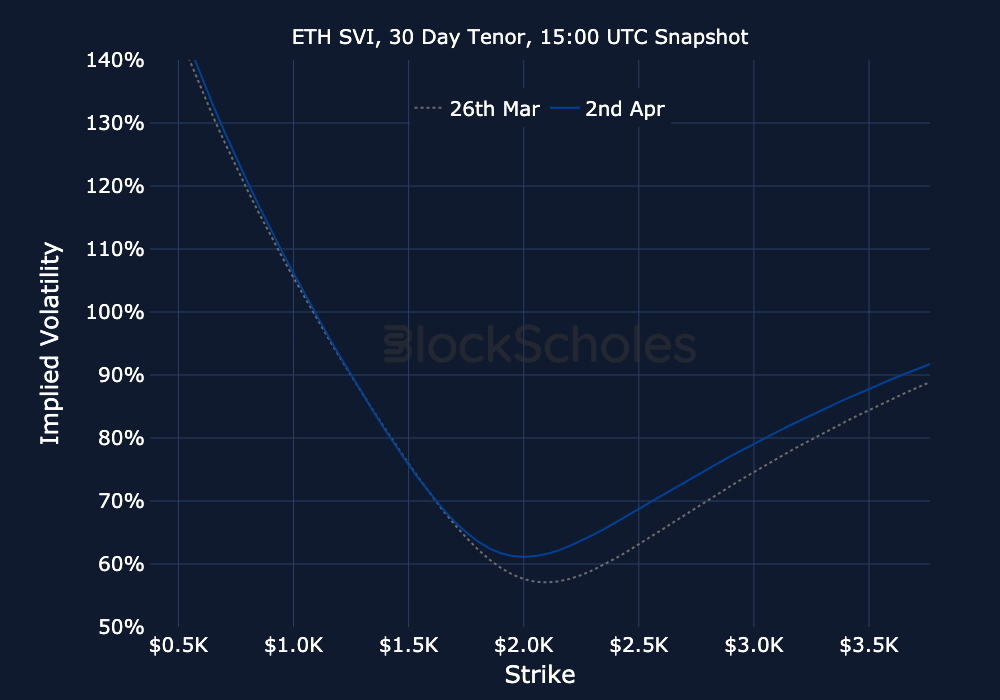
BYBIT ETH SVI ATM IMPLIED VOLATILITY — April has continued March’s inversions of the term structure as spot price continues to trade sub-$2,000.
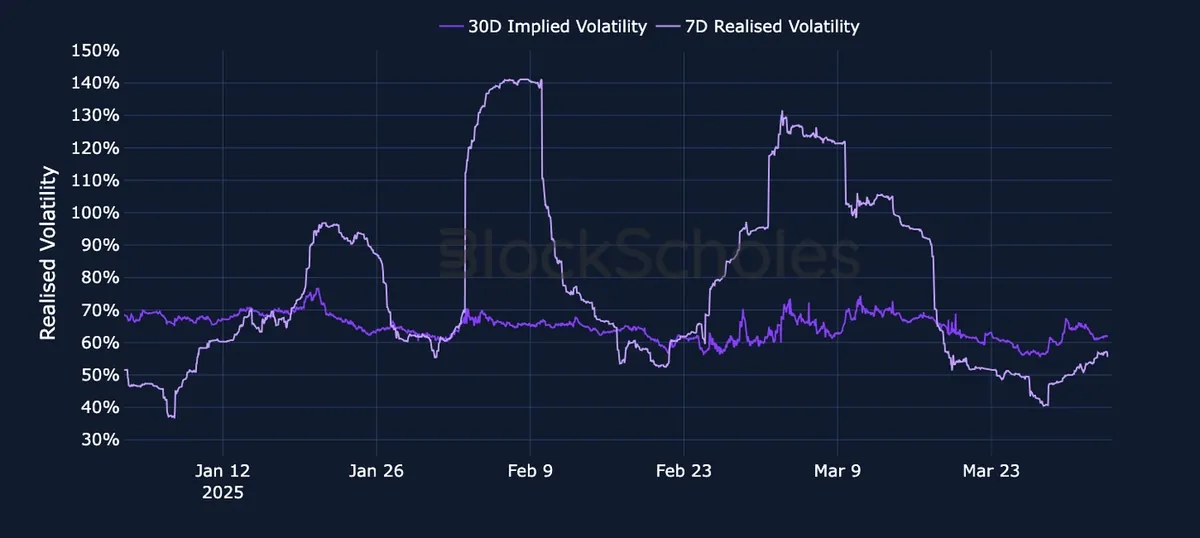
BYBIT ETH IMPLIED AND REALIZED VOLATILITY — As with BTC, realized volatility for ETH has bounced off its lows and is only slightly below implied levels.
SOL options
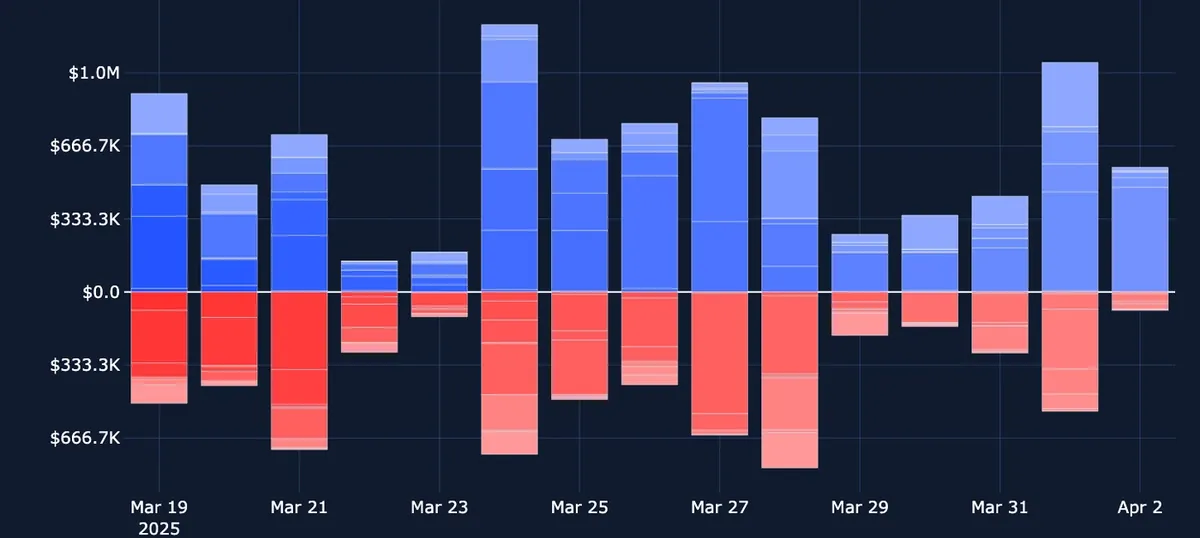
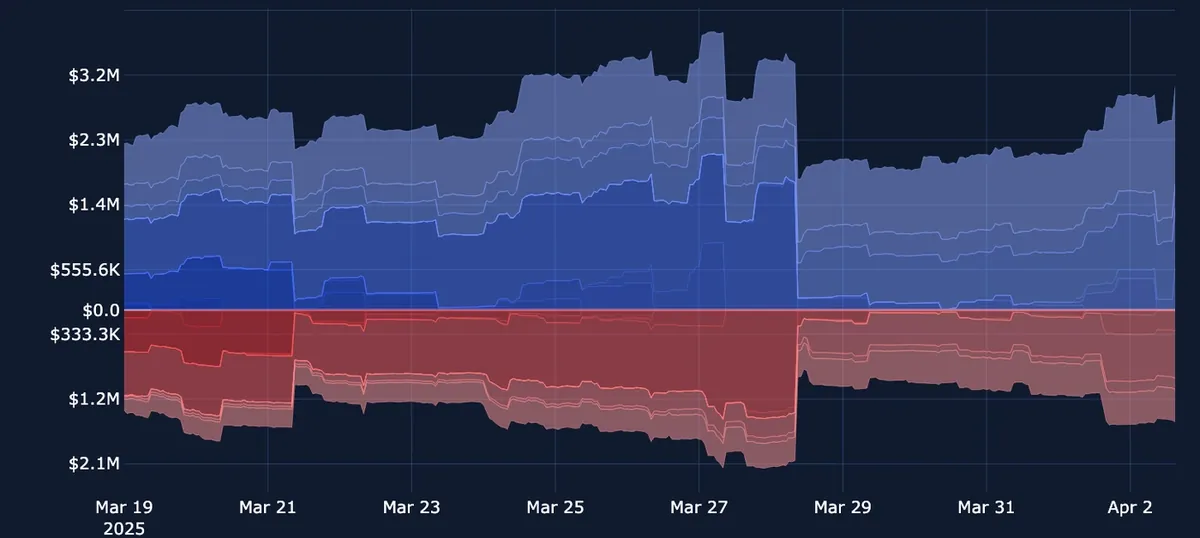
SOL options are still the lowest being traded among our other majors (BTC and ETH), although this week has seen a material increase in call options, which have firmly dominated options volume and open interest. Following the Mar 28, 2025 expirations, many contracts weren’t reopened, as the notional size of call contracts has dropped from over $3.2M to closer to $2.5M. Nevertheless, we’ve seen a small increase in the notional size of open put options — perhaps as traders grapple with a continued slide from the January all-time high of $250.
Volatility by exchange
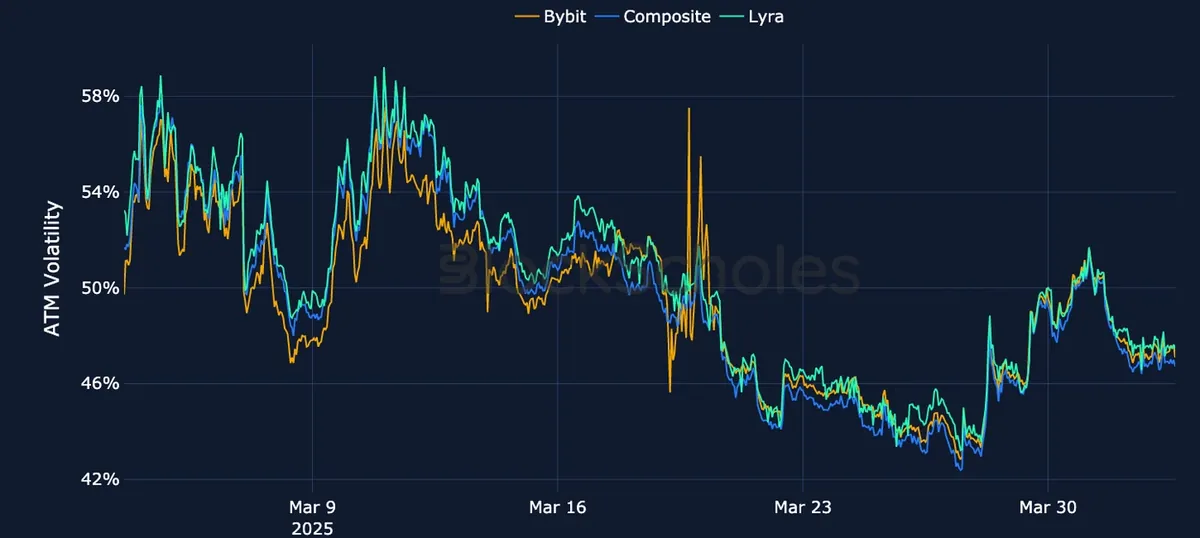
BTC, 1-MONTH TENOR, SVI CALIBRATION
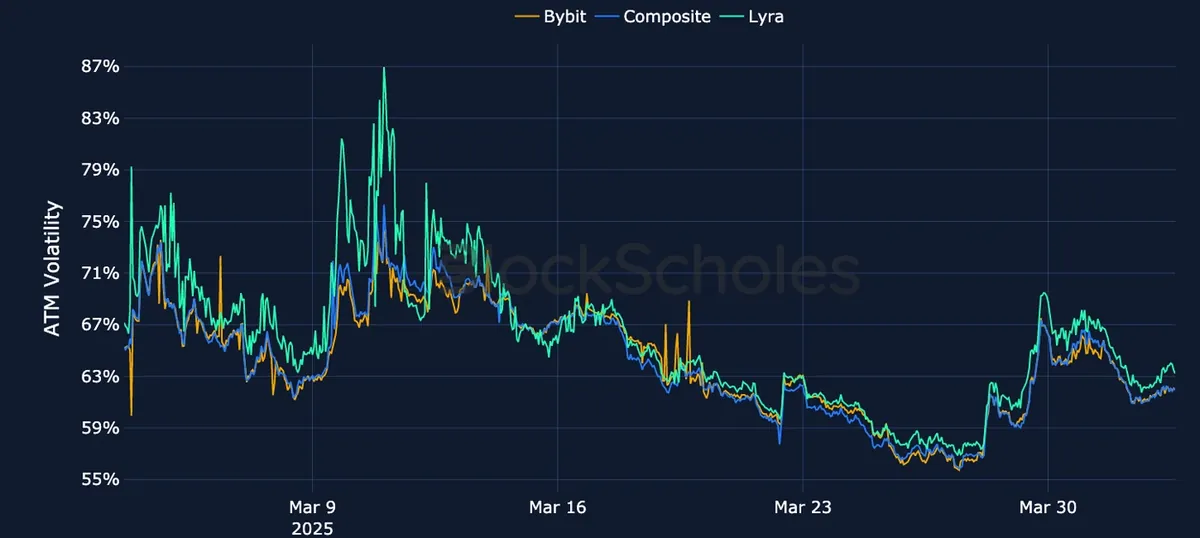
ETH, 1-MONTH TENOR, SVI CALIBRATION
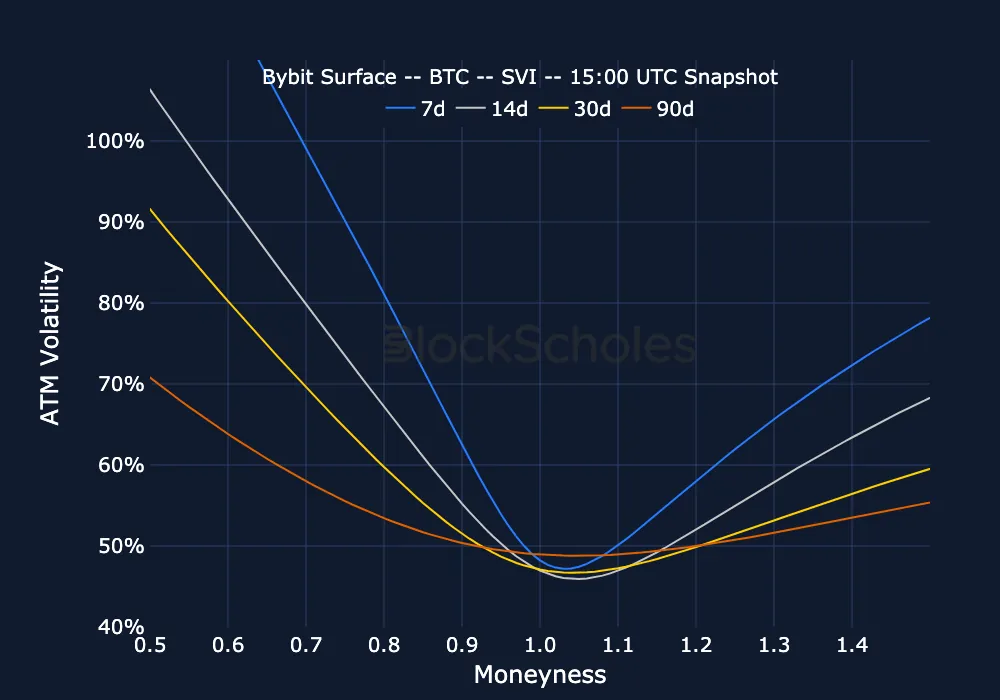
Bybit volatility surface
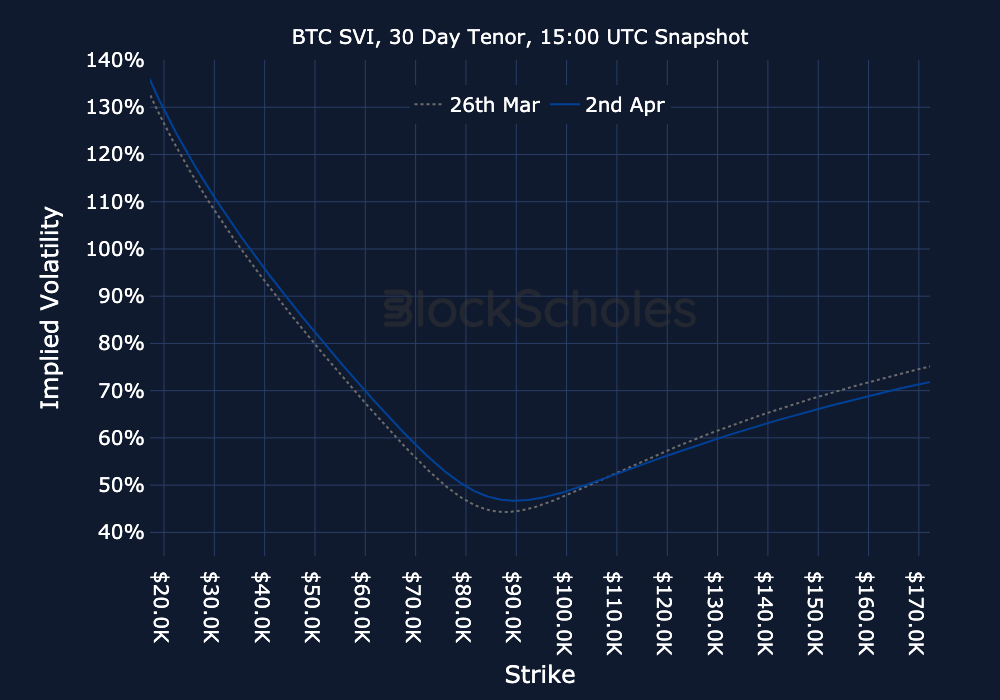
Constant maturity smile
Data & Methodology
Data Acquisition, Composition & Timeline
Open interest and trading volume data are sourced “as is” from the Bybit exchange platform API exclusively, and as such do not represent a comprehensive picture of the sum of trading activity across all derivatives markets or exchanges. The data visualized in this report consists of hourly and daily snapshots, recorded over the previous 30 days. Daily (hourly) snapshots of trade volume record the total sum of the notional value of trades recorded in the 24H (1 hour) period, beginning with the snapshot timestamp.
If not explicitly labeled as derived from another exchange, the input instrument prices to all derivatives analytics metrics in this report are sourced from the appropriate endpoints of Bybit’s public exchange platform API. In the event that data is labeled or referred to as representing the market on another exchange source, that data is sourced from the appropriate endpoint of each respective exchange’s public API.
Macroeconomic charts and data are sourced “as is” from the Bloomberg Terminal. Exchange data is sourced “as is” from publicly available exchange APIs. Block Scholes makes no claims about the veracity of public third-party data.
Open Interest & Volume Dollar Denomination
After acquisition of underlying-denominated raw data for open interest and trading volume on the Bybit exchange platform from Bybit’s API endpoint, equivalent dollar-denominated figures are calculated using the concurrent value of Block Scholes’s Spot Index for the relevant underlying asset.
Block Scholes’s Spot Index represents the aggregate Spot mid-price for a given currency across the top five CEXs by volume (with USD-quoted markets). It considers the proportion of total volume in the instrument on the exchange, as well as the deviation of a data point from those on other exchanges.
Block Scholes–Derived Analytics Metrics
Futures prices are used for Block Scholes’s futures-implied yields calculation services in order to derive the constant-tenor annualized yields displayed in the Futures section of this report.
Options prices are used for Block Scholes’s implied volatility calculation services in order to calibrate volatility surfaces, from which all derivatives volatility analytics displayed in the BTC Options and ETH Options sections of this report are calculated. Volatility smiles are constructed by calibrating to mid-market prices observed in Bybit options markets. As part of the calibration process, prices go through rigorous filtration and cleaning steps, which ensures that the resulting volatility surface is arbitrage-free and has exceptional fit to the market observables.